Hard Work Lies ahead for Lebanon on Road to IMF Aid Deal as Banks Reject Rescue Plan

An anti-government protester scuffles with Lebanese army soldiers in the town of Zouk Mosbeh, north of Beirut, Lebanon, April 27, 2020. (AP)
TT

Hard Work Lies ahead for Lebanon on Road to IMF Aid Deal as Banks Reject Rescue Plan

An anti-government protester scuffles with Lebanese army soldiers in the town of Zouk Mosbeh, north of Beirut, Lebanon, April 27, 2020. (AP)

With a rescue plan that will form the basis of talks for IMF aid finally in place, Lebanon must now enact painful steps and work out how it distributes the costs, with the country’s banks likely to be particularly hard hit.

The Lebanese government signed a request for assistance from the International Monetary Fund (IMF) on Friday in what Prime Minister Hassan Diab’s office described as “a historic moment in the history of Lebanon”.

Although economists and diplomats welcomed the plan as a critical first step, many were skeptical that ambitious proposals to cut public sector spending and overhaul the banking sector could be enacted after years of political wrangling.

“This means the onset of serious negotiations with the IMF so this is very important and good news because it removes a lot of uncertainty. Having said that, the issue in Lebanon has always been one of execution,” ex-economy minister Nasser Saidi said of the 53-page plan passed on Thursday.

The plan sets out tens of billions of dollars in financial system losses and tough measures to claw Lebanon out of a crisis that has seen its currency crash, unemployment soar, the country default on its sovereign debt and protests on the streets.

“We have taken the first step on the path of saving Lebanon from the deep financial gap; and it would be difficult to get out of it without efficient and impactful help,” Diab’s office said in Friday’s statement.

A rapid slide in the Lebanese pound, which has lost more than half its value since October, has sparked renewed unrest, with a demonstrator killed in riots targeting banks that have frozen savers out of US dollar deposits.

Beirut hopes that with an IMF program in hand, foreign donors will release about $11 billion pledged at a Paris conference in 2018 which was tied to long-stalled reforms.

“Implementation is the hard bit, and Lebanon has consistently failed on this. Progress will only be possible with that, on the basis of greater political and public consensus,” a Western diplomat told Reuters.

The plan, which calls for an additional $10 billion in external support over five years, also forms the backbone of talks with foreign bondholders that have yet to start and several Lebanese dollar bonds notched up their best daily gains on Friday in more than a month.

Lebanon said in March that it was defaulting on Eurobonds totalling $31 billion to preserve cash for vital imports.

“In large part it’s a big PR move for the government as there was a feeling that the government was starting to lose control of the narrative. This plan shows they’re really trying to work towards something,” Nafez Zouk, emerging markets strategist at Oxford Economics, said.

Blow to banks

A central plank of the plan is imposing financial sector losses of roughly $70 billion, which will be covered in part by a shareholder bail-in and cash taken from large depositors.

With measures such as recovering stolen assets abroad, this could take years while some economists say the plan places too heavy a burden on a banking sector that has helped finance decades of large state budget deficits.

“This is basically a takeover of the banking sector by the state. I don’t understand how this will restore confidence,” said Nassib Ghobril, chief economist at Byblos Bank. “When you go this way, where is lending going to come from?”

Marwan Mikhael, head of research at Blominvest Bank, said it was unfair to make banks pay such a high cost for years of government borrowing that led to the default and broader crisis.

“The government doesn’t have the money to bail out the banks ... so here they want the banks to rescue the government.”

The Lebanese Banking Association said Friday it would in “no way” endorse the rescue plan, saying it wasn’t even consulted on it “despite being key part of any solution.”

“Domestic bank restructuring will further destroy confidence in Lebanon both domestically and internationally,” it said in a statement.

The plan will likely deter investment in the economy, thereby, hindering any recovery prospects, it added.

The association called the plan's revenue and expenditure measures "vague" and not backed by a precise timeline for implementation, and said it did not address inflationary pressures that could lead to hyperinflation.

It urged MPs to reject it, in part because it violated private property, and said it would soon present a plan of its own that could restore growth.


Oil Prices Fall on Easing Fears Over Saudi Supply Disruption

FILE PHOTO: Vessels near the Strait of Hormuz, as seen from Musandam, Oman, September 2, 2026. REUTERS/Stringer/File Photo
TT

Oil Prices Fall on Easing Fears Over Saudi Supply Disruption

FILE PHOTO: Vessels near the Strait of Hormuz, as seen from Musandam, Oman, September 2, 2026. REUTERS/Stringer/File Photo

Oil prices fell 2% on Friday, extending losses for a third straight session as easing concerns over Saudi supply disruptions outweighed anxiety about a widening of conflict across the Middle East.

Brent crude futures fell by $2.14, or 2%, to $102.68 a barrel by 0806 GMT. US West Texas Intermediate futures fell $1.83, or 1.8%, to $100.08, Reuters reported.

Benchmark Brent prices are on track for their first weekly loss in three.

Prices climbed to close to four-month highs earlier in the week after sources said crude loadings ⁠at Saudi Arabia's Red Sea export hub of Yanbu had been suspended and Riyadh cancelled some deliveries to Europe after its East-West pipeline was damaged in an attack last week.

However, prices have cooled since on reports that Saudi Arabia was seeking to restore about half the capacity of its East-West oil pipeline within days.

Saudi Arabia has sold about 60 million barrels of crude from its Gulf port of Ras Tanura inside the Strait of Hormuz for loading via ship-to-ship transfer at the Omani port of Sohar this month and next, multiple trade sources said on Friday.

The rebound in Saudi Aramco's exports from inside the Gulf to between 1 million to 1.5 million barrels per day on average, similar to or slightly higher than August's levels, has cooled global oil prices as it could make up for some of the ⁠volume lost at its port of Yanbu.

Chinese and South Korean refiners are among the top buyers of the spot supplies, while some volumes will be going to India and Japan, said the sources, who spoke on condition of anonymity.

"Recent efforts ‌to restore Saudi export capacity have reduced some of the immediate supply ‌anxiety," said Priyanka Sachdeva, head of market insights at Phillip Nova.


ECB's Lagarde Keeps Door Open to Early Exit

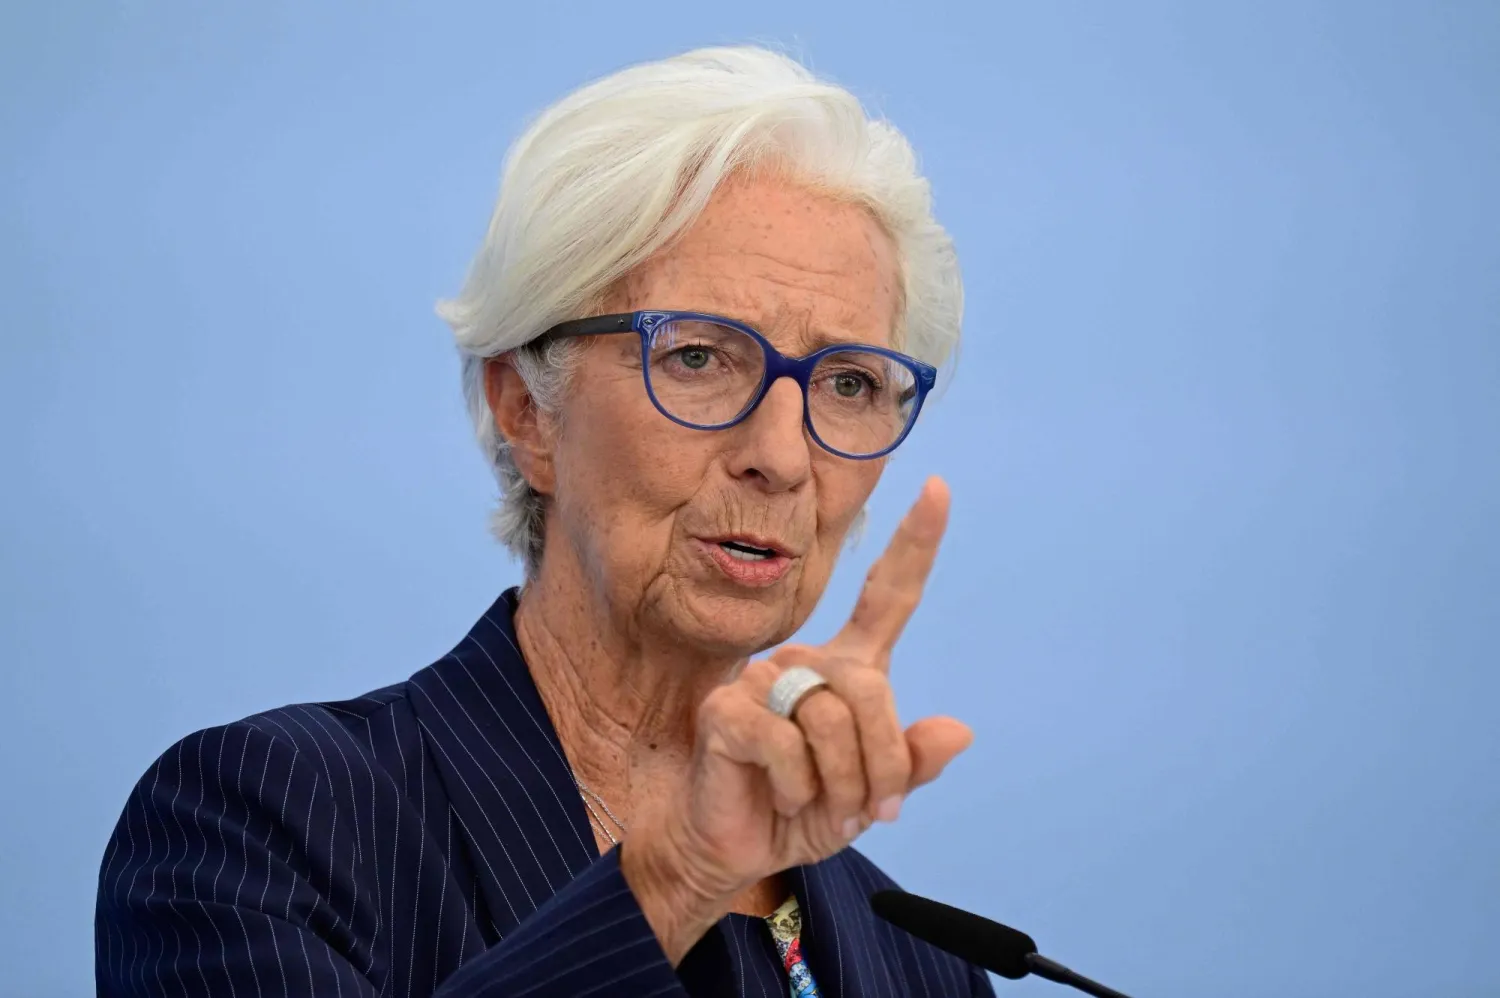
European Central Bank (ECB) President Christine Lagarde addresses a press conference after a meeting of the Governing Council of the European Central Bank (ECB) in Berlin on September 10, 2026. (Photo by John MACDOUGALL / AFP)
TT

ECB's Lagarde Keeps Door Open to Early Exit

European Central Bank (ECB) President Christine Lagarde addresses a press conference after a meeting of the Governing Council of the European Central Bank (ECB) in Berlin on September 10, 2026. (Photo by John MACDOUGALL / AFP)

European Central Bank President Christine Lagarde on Friday kept the door open to leaving her post early, replying "we'll see" when asked if she would remain in the position until her term ends ‌in October 2027.

"I ‌leave in ‌2027," ⁠Lagarde told Irish ⁠national broadcaster RTE in response to a question on rumors of her early resignation that have persisted for most ⁠of this year.

When asked ‌if ‌that meant October 2027, ‌Lagarde replied: "We'll see."

"What I ‌can tell you at this point is that whatever the time, it will be ‌handled in the most professional way as ⁠it should ⁠be," she added.

Sources told Reuters this week that France would back Dutchman Klaas Knot to succeed Lagarde as part of a bargain in which a French candidate would be picked for chief economist.


5 Countries Want Smaller Growth of Next EU Budget, Spain Offers Ideas

FILE PHOTO: European Union flags flutter outside the European Commission headquarters in Brussels, Belgium April 29, 2026. REUTERS/Yves Herman/File Photo
TT

5 Countries Want Smaller Growth of Next EU Budget, Spain Offers Ideas

FILE PHOTO: European Union flags flutter outside the European Commission headquarters in Brussels, Belgium April 29, 2026. REUTERS/Yves Herman/File Photo

Germany, Denmark, Finland, the Netherlands and Austria said on Friday the European Union's budget for 2028-2034 must be "several hundred billion euros" smaller than the €2 trillion proposed by the European Commission, drawing battle lines before EU budget talks come to a head in the next three months.

The leaders of the five countries, among the biggest net contributors to the budget, wrote in a joint op-ed in Politico that EU taxpayers ⁠cannot keep paying ⁠more to pay for both old and new priorities.

"It (the budget) is too focused on subsidies and transfers allocated largely in advance, leaving too little room for what Europe urgently needs: common investment in security and defense, competitiveness, innovation, and the fight against irregular migration," the five leaders said.

Net beneficiaries of the EU budget are concerned that ⁠would reduce EU funds for farmers and for equalizing standards of living between the poorer and richer regions of Europe -- a major political concern before parliamentary elections next year in France, Italy, Spain, Poland, Greece, Finland, Slovakia and Estonia.

The European Commission has proposed the budget should amount to €2 trillion or 1.26% of EU Gross National Income (GNI), of which some 168 billion, or 0.11% of GNI, is to service the EU's borrowing for the post-pandemic recovery fund. The five leaders called the proposed nominal increase of around 60% over the 2021-2027 budget "simply not ⁠realistic."

"This is ⁠why we call for a balanced cut to the Commission’s proposal of several hundred billion euros," Reuters quoted them as saying.

To help find a solution, Spain proposed to change the repayment schedule of part of the EU post-pandemic borrowing, linking it to economic growth and spreading it out over a longer period. This, according to Spanish Economy Minister Carlos Cuerpo, would free up some €70 billion.

"An annual payment of about 0.06% of EU GDP would retire the debt by 2058, the deadline agreed by member states," Cuerpo said.

EU governments will discuss the next EU budget at summits in October, November and December in an effort to get a deal before the end of the year.