OPEC: Move to Cut Oil Output Was Unanimous to Prevent Crisis

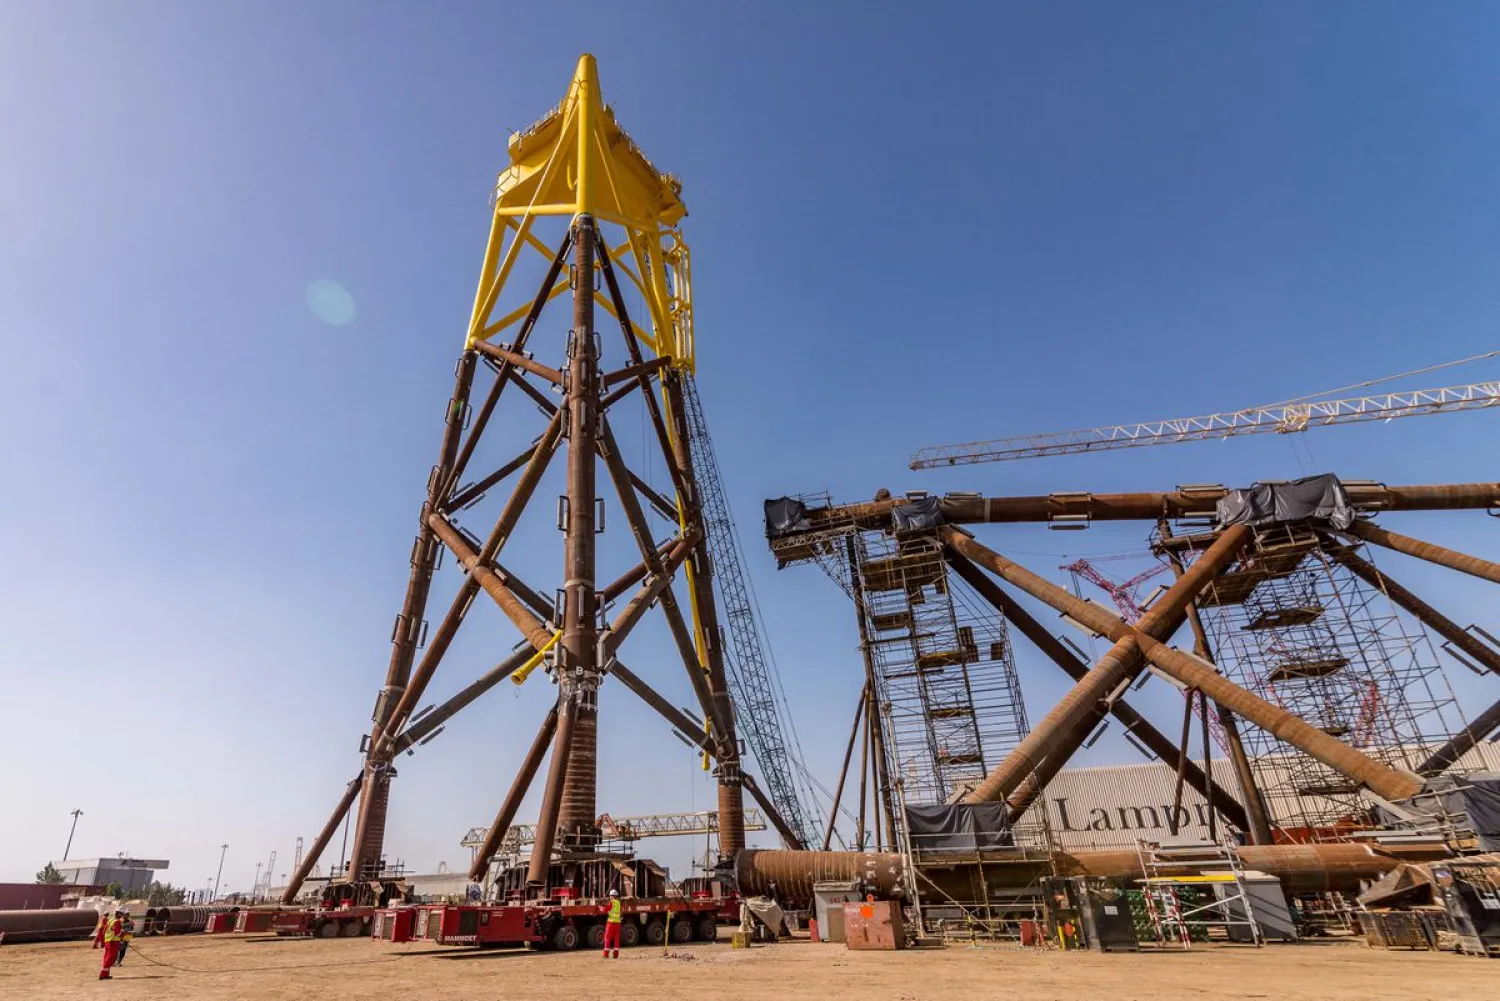
A facility operated by oil and gas services company Lamprell in Dubai, United Arab Emirates is pictured in this handout image provided to Reuters on June 24, 2022. Lamprell/Handout via REUTERS
TT

OPEC: Move to Cut Oil Output Was Unanimous to Prevent Crisis

A facility operated by oil and gas services company Lamprell in Dubai, United Arab Emirates is pictured in this handout image provided to Reuters on June 24, 2022. Lamprell/Handout via REUTERS

The Organization of the Petroleum Exporting Countries (OPEC) Secretary-General Haitham al-Ghais said on Tuesday that OPEC+ alliance took an unanimous decision to cut oil output as a pre-emptive measure to prevent a crisis.

Speaking at the African Energy Week in South Africa, al-Ghais said the heads of delegations unanimously decided to take a proactive stance to create stability in global markets.

He said if investments in oil were not met, there could eventually be a serious supply shortfall resulting in more heightened volatility.

The OPEC Secretary-General also stressed that Africa's oil and natural gas reserves would be sought-after as energy demand was set to rise dramatically in the coming decades.

Earlier this month, the OPEC+ alliance of oil-exporting countries decided to cut oil production by 2 million barrels per day starting in November to balance between supply and demand. The US said it was disappointed by the decision.

However, Arab states and OPEC+ member states lined up to endorse the production cut in support of the Saudi vision to deal with the world oil markets.

Iraq, Kuwait, Bahrain, the Sultanate of Oman, Algeria, the UAE, Egypt, Morocco and Jordan expressed their support for the decision.

They issued separate statements confirming their support for the OPEC+ production cut and to Saudi Arabia’s vision in the oil markets.

UAE Energy minister Suhail al-Mazrouei said on Tuesday that his country believes OPEC+ made the correct technical choice when it agreed to cut production targets and the unanimous decision had nothing to do with politics.

“I would like to clarify that the latest OPEC+ decision, which was unanimously approved, was a pure technical decision, with no political intentions whatsoever,” the Minister said.

“We always meet and discuss the facts and how we can all contribute to taking the right measures to balance the supply and demand,” he stressed, adding that the decision is always taken unanimously and the same approach was taken in the last meeting.

During a conference before the start of Abu Dhabi International Petroleum Exhibition and Conference (ADIPEC) on Tuesday, Mazrouei said the decision stabilized prices, rather than increasing them, adding that it was the lack of stability that was driving investors away.

Asked if the UAE plans to ask for a higher baseline as it builds capacity, the minister said there is a mechanism for any country to raise that request.

Meanwhile, Kuwait said that the recent OPEC+ decision to cut oil output was taken collectively and based on economic studies of international oil markets, state news agency KUNA reported on Tuesday citing the foreign ministry.

For its part, the Jordanian Foreign Ministry said Amman supports all measures taken by Saudi Arabia to protect its security, stability and interests.

“This is a technical issue related to oil market stability and its requirements, regulating supply and demand and protecting the interests of both producers and consumers, that should be approached on technical basis within its economic context, away from political bickering that does not serve common goals and interests,” the ministry said in a statement.

Oil prices settled lower on Tuesday on fears of higher US supply combined with an economic slowdown and lower Chinese fuel demand ahead with its zero-Covid policy.

Brent crude futures were down $2.52, or 2.7 percent, at $89.14 a barrel by 15:30 GMT while US West Texas Intermediate crude futures fell $2.97, or 3.3 percent, to $82.55.

On Monday, Reuters said the Biden administration plans to sell more oil from the US Strategic Petroleum Reserve in a bid to dampen fuel prices before next month's congressional elections, quoting three sources familiar with the matter.


Iraq Oil Output Exceeds 5 million bpd

Majnoon oil field near the Iraqi city of Basra (Reuters)
TT

Iraq Oil Output Exceeds 5 million bpd

Majnoon oil field near the Iraqi city of Basra (Reuters)

Iraq produces more than 5 million barrels of oil per day (bpd), Oil Minister Basim Mohammed told state news agency INA on Saturday.

According to Reuters, Iraq is pushing for a higher OPEC production quota as the economic fallout from the Iran war and new investment by oil majors increase pressure on Baghdad to boost output, potentially putting it at odds with the producer group.

The conflict has hit Iraq particularly hard, forcing major export cuts and depriving the state of oil revenue, which accounted for 88% of government income last year.


IMF: Any Slowdown in AI-driven Growth Would be Factor for Central Banks

IMF Managing Director Kristalina Georgieva speaks during the Annual Meetings Plenary at the Annual Meetings of the International Monetary Fund (IMF) and the World Bank Group (WBG) at the Queen Sirikit National Convention Center (QSNCC) in Bangkok on October 16, 2026. (Photo by Lillian SUWANRUMPHA / AFP)
TT

IMF: Any Slowdown in AI-driven Growth Would be Factor for Central Banks

IMF Managing Director Kristalina Georgieva speaks during the Annual Meetings Plenary at the Annual Meetings of the International Monetary Fund (IMF) and the World Bank Group (WBG) at the Queen Sirikit National Convention Center (QSNCC) in Bangkok on October 16, 2026. (Photo by Lillian SUWANRUMPHA / AFP)

Central bankers around the world would need to consider any slowdown in AI-driven growth as they assess steps in their fight against inflation, International Monetary Fund Managing Director Kristalina Georgieva said on Friday.

Georgieva said concerns about dependence on the AI investment boom and high valuations were impacting markets around the world.

"Things are going up and down, and this is likely to continue," she told an audience at IMF headquarters in Washington, adding that the volatility would complicate the job of central banks at a time when risks to price stability had been growing.

A steep rout in technology stocks on Thursday rippled through markets on fears that ⁠the Democrats' victory ⁠in the US midterm elections would increase regulatory scrutiny of AI and slow the data center build-out, sending investors to the safety of bonds.

The political jitters are hitting an AI trade already on shaky footing due to worry about return on massive spending on AI-related infrastructure, with the meltdown spurring margin calls and spooking retail investors and hedge ⁠funds alike.

Georgieva said the AI investment boom was lifting growth in some countries, helping to offset a negative oil-supply shock triggered by the war in the Middle East, but it was also adding to inflationary pressures and financial stability concerns.

The IMF last month flagged significant growth and financial stability risks from a potential ending of the AI investment boom, among other factors, including a prolonged Middle East war. At the time, it warned that a steep drop in AI investment could lead to a sharp fall in asset prices, ultimately cutting global GDP ⁠by 1.1% ⁠by 2028, including a 1.8% drop in US output.

Georgieva did not repeat the downside forecast on Friday, but acknowledged the recent market volatility.

"Should there be a slowdown in the AI-driven growth impulse, it would need to be factored in as central banks assess the necessary steps in the fight against stubborn inflation," she said.

Democrats are planning to unleash a flood of new legislation targeting artificial intelligence systems and data-center development when they take control of the US Congress in January, Reuters reported on Friday, citing congressional aides and advocates.

That would mark a sharp shift from the Republican-led Congress, where lawmakers largely focused on promoting AI development and declined to pass legislation restricting the technology.


World Food Prices Dip in October, but Remain Higher Than a Year Ago

A worker carries loaves of bread for sale at a bakery in the capital city of Cairo, Egypt November 4, 2026. (Reuters)
TT

World Food Prices Dip in October, but Remain Higher Than a Year Ago

A worker carries loaves of bread for sale at a bakery in the capital city of Cairo, Egypt November 4, 2026. (Reuters)

World food prices edged lower in October as weaker import demand contributed to monthly declines in cereal, dairy and meat prices, but were still nearly 6% higher than a year earlier, the United Nations' Food and Agriculture Organization said on Friday.

The FAO Food Price Index, which tracks monthly changes in international prices for a basket of food commodities, ‌averaged 133.9 points ‌in October, down from a revised ‌135.6 ⁠in September.

The index ⁠was 5.9% higher than a year earlier, but remained 16.4% below its March 2022 peak.

FAO's cereal price index fell 4.5% from September and was 12.6% lower than a year ago, as wheat and maize quotations declined. Wheat prices eased on weak import demand ⁠and improved production prospects, especially in Argentina.

"Expectations of ‌easing constraints on Black ‌Sea export flows added to the downward pressure on prices, ‌although continued disruptions to Black Sea logistics limited the decline," ‌FAO said in a statement.

Maize prices also eased after reaching a three-year high in September, pressured by the US harvest, expectations of ample supplies in South America and renewed ‌prospects of easing tensions in the Black Sea region.

Vegetable oil prices edged up 0.3%, ⁠as ⁠higher soybean and sunflower oil prices more than offset a fall in rapeseed oil prices.

Sugar prices rose 6.6%, their fourth straight monthly increase, to the highest level since December 2024, after rainfall disrupted harvesting in Brazil. They were now 28.8% above a year ago.

The dairy index fell 1.1%, as lower butter and cheese prices linked to ample supplies and subdued demand outweighed gains in milk powder.

The meat index declined 1.2%, while still slightly above its year-earlier level, as ovine and bovine meat prices fell.