One of Silicon Valley's Top Banks Fails; Assets are Seized

The four biggest US banks lost a whopping $52 billion in market value on Thursday. TIMOTHY A. CLARY / AFP/File
TT

One of Silicon Valley's Top Banks Fails; Assets are Seized

The four biggest US banks lost a whopping $52 billion in market value on Thursday. TIMOTHY A. CLARY / AFP/File

Regulators rushed Friday to seize the assets of one of Silicon Valley's top banks, marking the largest failure of a US financial institution since the height of the financial crisis almost 15 years ago.

Silicon Valley Bank, the nation’s 16th-largest bank, failed after depositors hurried to withdraw money this week amid anxiety over the bank’s health. It was the second biggest bank failure in US history after the collapse of Washington Mutual in 2008.
The bank served mostly technology workers and venture capital-backed companies, including some of the industry's best-known brands.

“This is an extinction-level event for startups,” said Garry Tan, CEO of Y Combinator, a startup incubator that launched Airbnb, DoorDash and Dropbox and has referred hundreds of entrepreneurs to the bank.

“I literally have been hearing from hundreds of our founders asking for help on how they can get through this. They are asking, ‘Do I have to furlough my workers?’”

There appeared to be little chance of the chaos spreading in the broader banking sector, as it did in the months leading up to the Great Recession. The biggest banks — those most likely to cause an economic meltdown — have healthy balance sheets and plenty of capital.

Nearly half of the US technology and health care companies that went public last year after getting early funding from venture capital firms were Silicon Valley Bank customers, according to the bank’s website.

The bank also boasted of its connections to leading tech companies such as Shopify, ZipRecruiter and one of the top venture capital firms, Andreesson Horowitz.

Tan estimated that nearly one-third of Y Combinator’s startups will not be able to make payroll at some point in the next month if they cannot access their money.

Internet TV provider Roku was among casualties of the bank collapse. It said in a regulatory filing Friday that about 26% of its cash — $487 million — was deposited at Silicon Valley Bank.

Roku said its deposits with SVB were largely uninsured and it didn’t know “to what extent” it would be able to recover them.

As part of the seizure, California bank regulators and the FDIC transferred the bank's assets to a newly created institution — the Deposit Insurance Bank of Santa Clara. The new bank will start paying out insured deposits on Monday. Then the FDIC and California regulators plan to sell off the rest of the assets to make other depositors whole.

There was unease in the banking sector all week, with shares tumbling by double digits. Then news of Silicon Valley Bank's distress pushed shares of almost all financial institutions even lower Friday.

The failure arrived with incredible speed. Some industry analysts suggested Friday that the bank was still a good company and a wise investment. Meanwhile, Silicon Valley Bank executives were trying to raise capital and find additional investors. However, trading in the bank’s shares was halted before stock market's opening bell due to extreme volatility.

Shortly before noon, the FDIC moved to shutter the bank. Notably, the agency did not wait until the close of business, which is the typical approach. The FDIC could not immediately find a buyer for the bank's assets, signaling how fast depositors cashed out.

The White House said Treasury Secretary Janet Yellen was “watching closely.” The administration sought to reassure the public that the banking system is much healthier than during the Great Recession.

“Our banking system is in a fundamentally different place than it was, you know, a decade ago,” said Cecilia Rouse, chair of the White House Council of Economic Advisers. “The reforms that were put in place back then really provide the kind of resilience that we’d like to see.”

In 2007, the biggest financial crisis since the Great Depression rippled across the globe after mortgage-backed securities tied to ill-advised housing loans collapsed in value. The panic on Wall Street led to the demise of Lehman Brothers, a firm founded in 1847.
Because major banks had extensive exposure to one another, the crisis led to a cascading breakdown in the global financial system, putting millions out of work.

At the time of its failure, Silicon Valley Bank, which is based in Santa Clara, California, had $209 billion in total assets, the FDIC said. It was unclear how many of its deposits were above the $250,000 insurance limit, but previous regulatory reports showed that lots of accounts exceeded that amount.

The bank announced plans Thursday to raise up to $1.75 billion in order to strengthen its capital position. That sent investors scurrying and shares plunged 60%. They tumbled lower still Friday before the opening of the Nasdaq, where the bank's shares were traded.

As its name implied, Silicon Valley Bank was a major financial conduit between the technology sector, startups and tech workers. It was seen as good business sense to develop a relationship with the bank if a startup founder wanted to find new investors or go public.

Conceived in 1983 by co-founders Bill Biggerstaff and Robert Medearis during a poker game, the bank leveraged its Silicon Valley roots to become a financial cornerstone in the tech industry.

Bill Tyler, director of operations for TWG Supply in Grapevine, Texas, said he first realized something was wrong when his employees texted him at 6:30 a.m. Friday to complain that they did not receive their paychecks.

TWG, which has just 18 employees, had already sent the money for the checks to a payroll services provider that used Silicon Valley Bank. Tyler was scrambling to figure out how to pay his workers.

"We’re waiting on roughly $27,000," he said. "It’s already not a timely payment. It’s already an uncomfortable position. I don’t want to ask any employees, to say, ‘Hey, can you wait until mid-next week to get paid?’”

Silicon Valley Bank's ties to the tech sector added to its troubles. Technology stocks have been hit hard in the past 18 months after a growth surge during the pandemic, and layoffs have spread throughout the industry. Venture capital funding has also been declining.

At the same time, the bank was hit hard by the Federal Reserve's fight against inflation and an aggressive series of interest rate hikes to cool the economy.

As the Fed raises its benchmark interest rate, the value of generally stable bonds starts to fall. That is not typically a problem, but when depositors grow anxious and begin withdrawing their money, banks sometimes have to sell those bonds before they mature to cover the exodus.

That is exactly what happened to Silicon Valley Bank, which had to sell $21 billion in highly liquid assets to cover the sudden withdrawals. It took a $1.8 billion loss on that sale.

Ashley Tyrner, CEO of FarmboxRx, said she had spoken to several friends whose businesses are backed by venture capital. She described them as being “beside themselves” over the bank's failure. Tyrner's chief operating officer tried to withdraw her company's funds on Thursday but failed to do so in time.

“One friend said they couldn't make payroll today and cried when they had to inform 200 employees because of this issue,” Tyrner said.

World Bank Projects Regional Growth to Reach 7.8% in 2027

(FILES) An aerial view shows ships anchored off the coast of Khasab in Oman's Musandam Governorate, near the Strait of Hormuz, on October 2, 2026. (Photo by AFP)
TT

World Bank Projects Regional Growth to Reach 7.8% in 2027

(FILES) An aerial view shows ships anchored off the coast of Khasab in Oman's Musandam Governorate, near the Strait of Hormuz, on October 2, 2026. (Photo by AFP)

The World Bank said Tuesday that if the Middle East conflict subsides by the end of this year, regional growth excluding Iran is projected to rebound to 7.8% in 2027.

In a report titled “From Divide to Opportunity: AI, Jobs, and Growth,” the Bank said that regional output is projected to contract by 2.1% on average in 2026, after expanding 3.3% in 2025.

The report on the economic update on Middle East, North Africa, Afghanistan & Pakistan reveals a sharp deterioration compared with its April forecasts. At that time, the Bank projected that the region's economies, excluding Iran, would grow by 1.8 percent in 2026, while it expected the economies of the Gulf Cooperation Council (GCC) countries to expand by 1.3 percent.

But growth expectations for the region have been revised downward by approximately 3.9 percentage points compared with the April forecast. Meanwhile, the outlook for GCC economies has shifted from 1.3 percent growth to a 4.3 percent contraction, representing a deterioration of 5.6 percentage points.

Hormuz Upends Gulf Calculations

This shift reflects the widening scope of the shock since April, as the repercussions of the closure of the Strait of Hormuz and the disruption of energy exports continue to unfold, with the effects spreading to trade, tourism, logistics services, and financial markets.

The World Bank expects the economies of GCC countries to contract by an average of 4.3 percent in 2026, compared with growth of 4.4 percent in 2025.

This marks a notable departure from traditional energy crises, in which rising oil prices typically boost the revenues of energy-exporting countries. In the current crisis, however, the disruption of oil shipments through the Strait of Hormuz has constrained producers' ability to export crude oil, making higher prices insufficient to offset the impact of reduced export volumes.

In contrast, oil-importing economies have shown greater resilience, with the World Bank forecasting their growth rate to rise to 4.3 percent in 2026, compared with 3.9 percent in 2025.

The repercussions of the conflict are not confined to the energy sector. They have also spread to tourism, aviation, and logistics services, while disruptions in shipping have increased import costs and placed additional strain on supply chains, particularly affecting food prices.

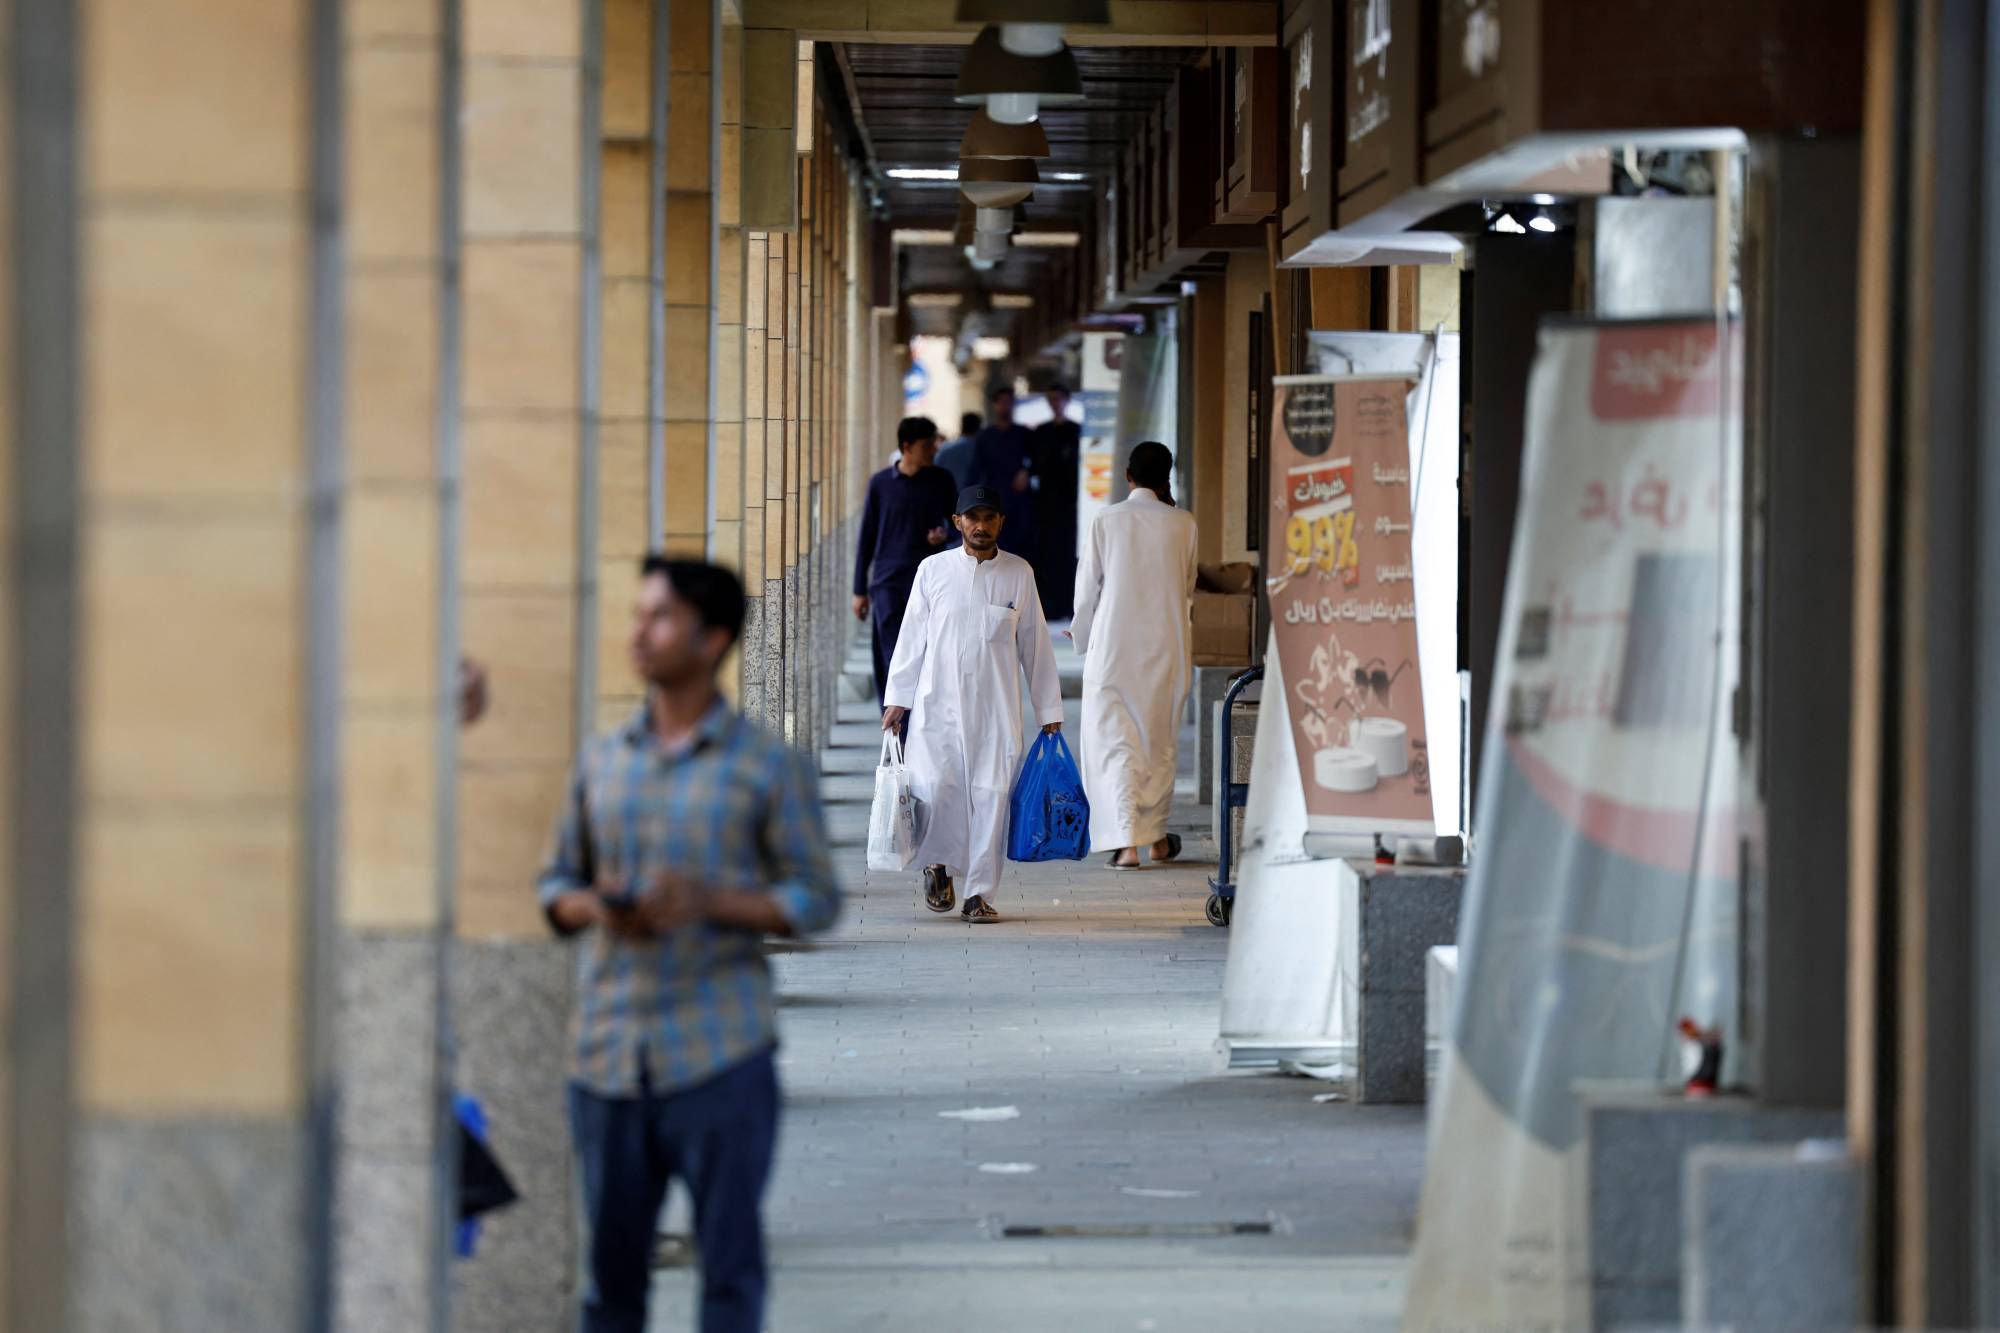
A man walks with shopping bags in a local souq down town Riyadh, Saudi Arabia, May 31, 2025. REUTERS/Hamad I Mohammed

Saudi Arabia Maintains its Recovery Path

As for Saudi Arabia, the World Bank expects real GDP per capita, which is projected to stand slightly above its 2019 level in 2025, to fall below that benchmark in 2026 before the economy benefits from a recovery in hydrocarbon production and exports as the shock recedes.

On the fiscal front, the World Bank estimates that the Kingdom's budget deficit will reach 6.6 percent of GDP in 2026, before narrowing to 3.7 percent in 2027.

The Bank also expects an improvement in the current account balance, with the deficit declining from 1.4 percent of GDP in 2026 to 0.9 percent in 2027.

These projections suggest that the most significant impact of the conflict will be concentrated in 2026, while financial and external indicators are expected to improve in the following year as hydrocarbon production and exports recover.

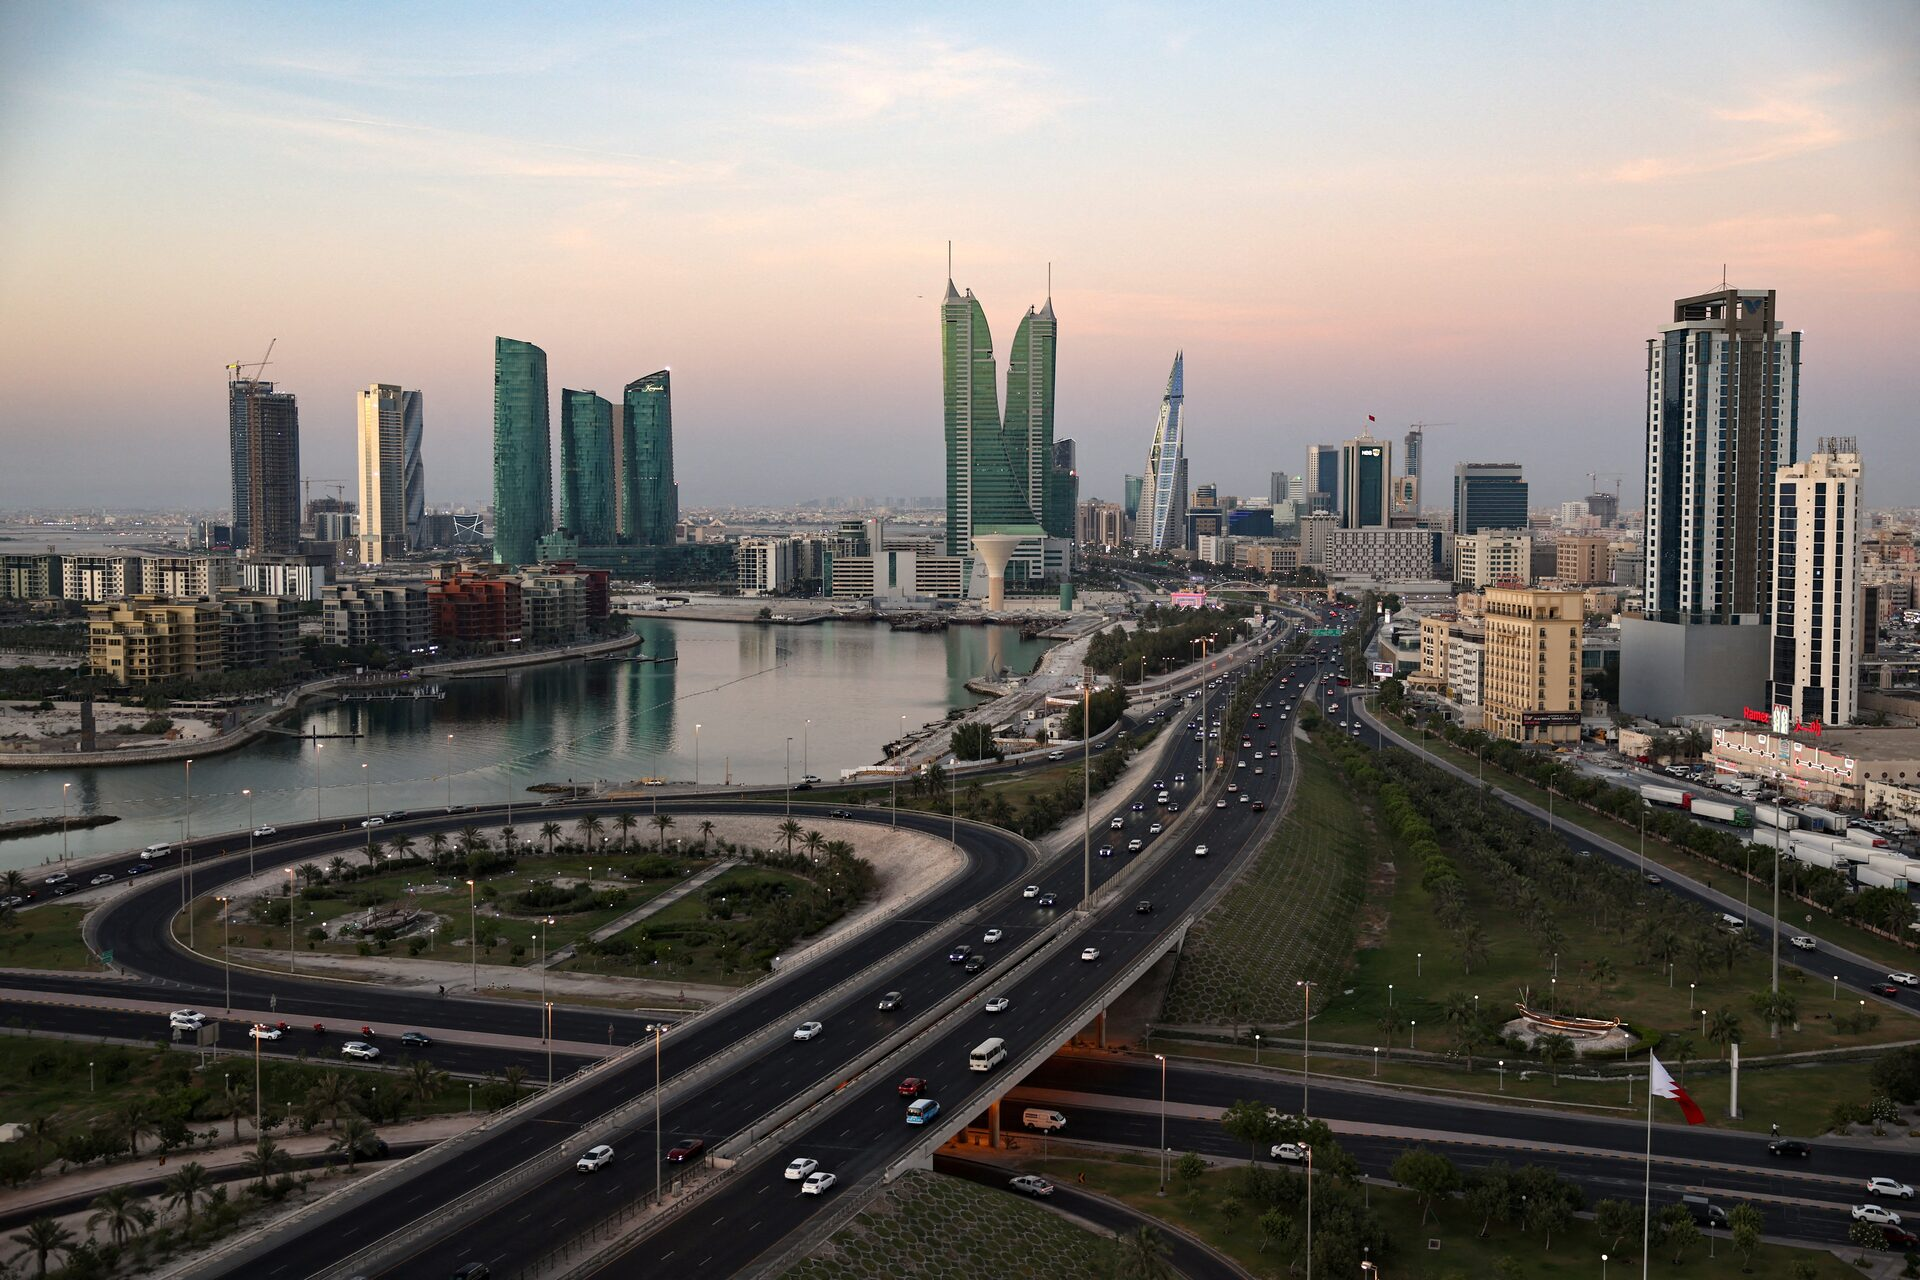
A general view of the skyline in downtown Manama, Bahrain, June 22, 2025. REUTERS/Hamad I Mohammed

Poverty Rising Across the Region

In fragile and conflict-affected economies, the latest shock is compounding pre-existing vulnerabilities. The World Bank notes that poverty in the Middle East and North Africa, Afghanistan, and Pakistan is becoming increasingly concentrated in fragile and conflict-affected settings.

The region accounts for roughly 14 percent of the world's population living in extreme poverty, making it second only to Sub-Saharan Africa. It is also the only region in the world where poverty levels remain above their pre-pandemic levels.

In 2024, some 14.3 percent of the region's population lived on less than $3 a day, compared with 10.4 percent globally. Meanwhile, 26.9 percent lived on less than $4.20 a day, compared with 18.9 percent worldwide.

The World Bank expects these negative trends to persist through 2026, with poverty becoming increasingly concentrated in conflict-affected and fragile economies, where displacement, weak labor markets, and the erosion of assets and basic services make recovery more difficult.

Strong Recovery Possible if Conflict Eases

The World Bank believes the region is capable of achieving a strong recovery if the intensity of the conflict declines by the end of 2026. Excluding Iran, the report projects regional growth to reach 7.8 percent in 2027, driven primarily by a rebound in hydrocarbon production and exports.

However, the recovery will not be automatic. The effects of damaged infrastructure, postponed investments, and the depletion of fiscal buffers could continue to weigh on growth long after the immediate shock has subsided.

Ousmane Dione, the World Bank's Vice President for the Middle East and North Africa, Afghanistan, and Pakistan, said: “Protecting vulnerable households, restoring productive capacity, and investing in more resilient energy and transport infrastructure will be critical to ensuring that a temporary shock does not leave lasting losses in human capital, growth prospects, and living standards.”

“Countries that are able to build up resilience and capacity now will be well positioned to take advantage of the opportunities of the future, particularly in artificial intelligence,” he added.

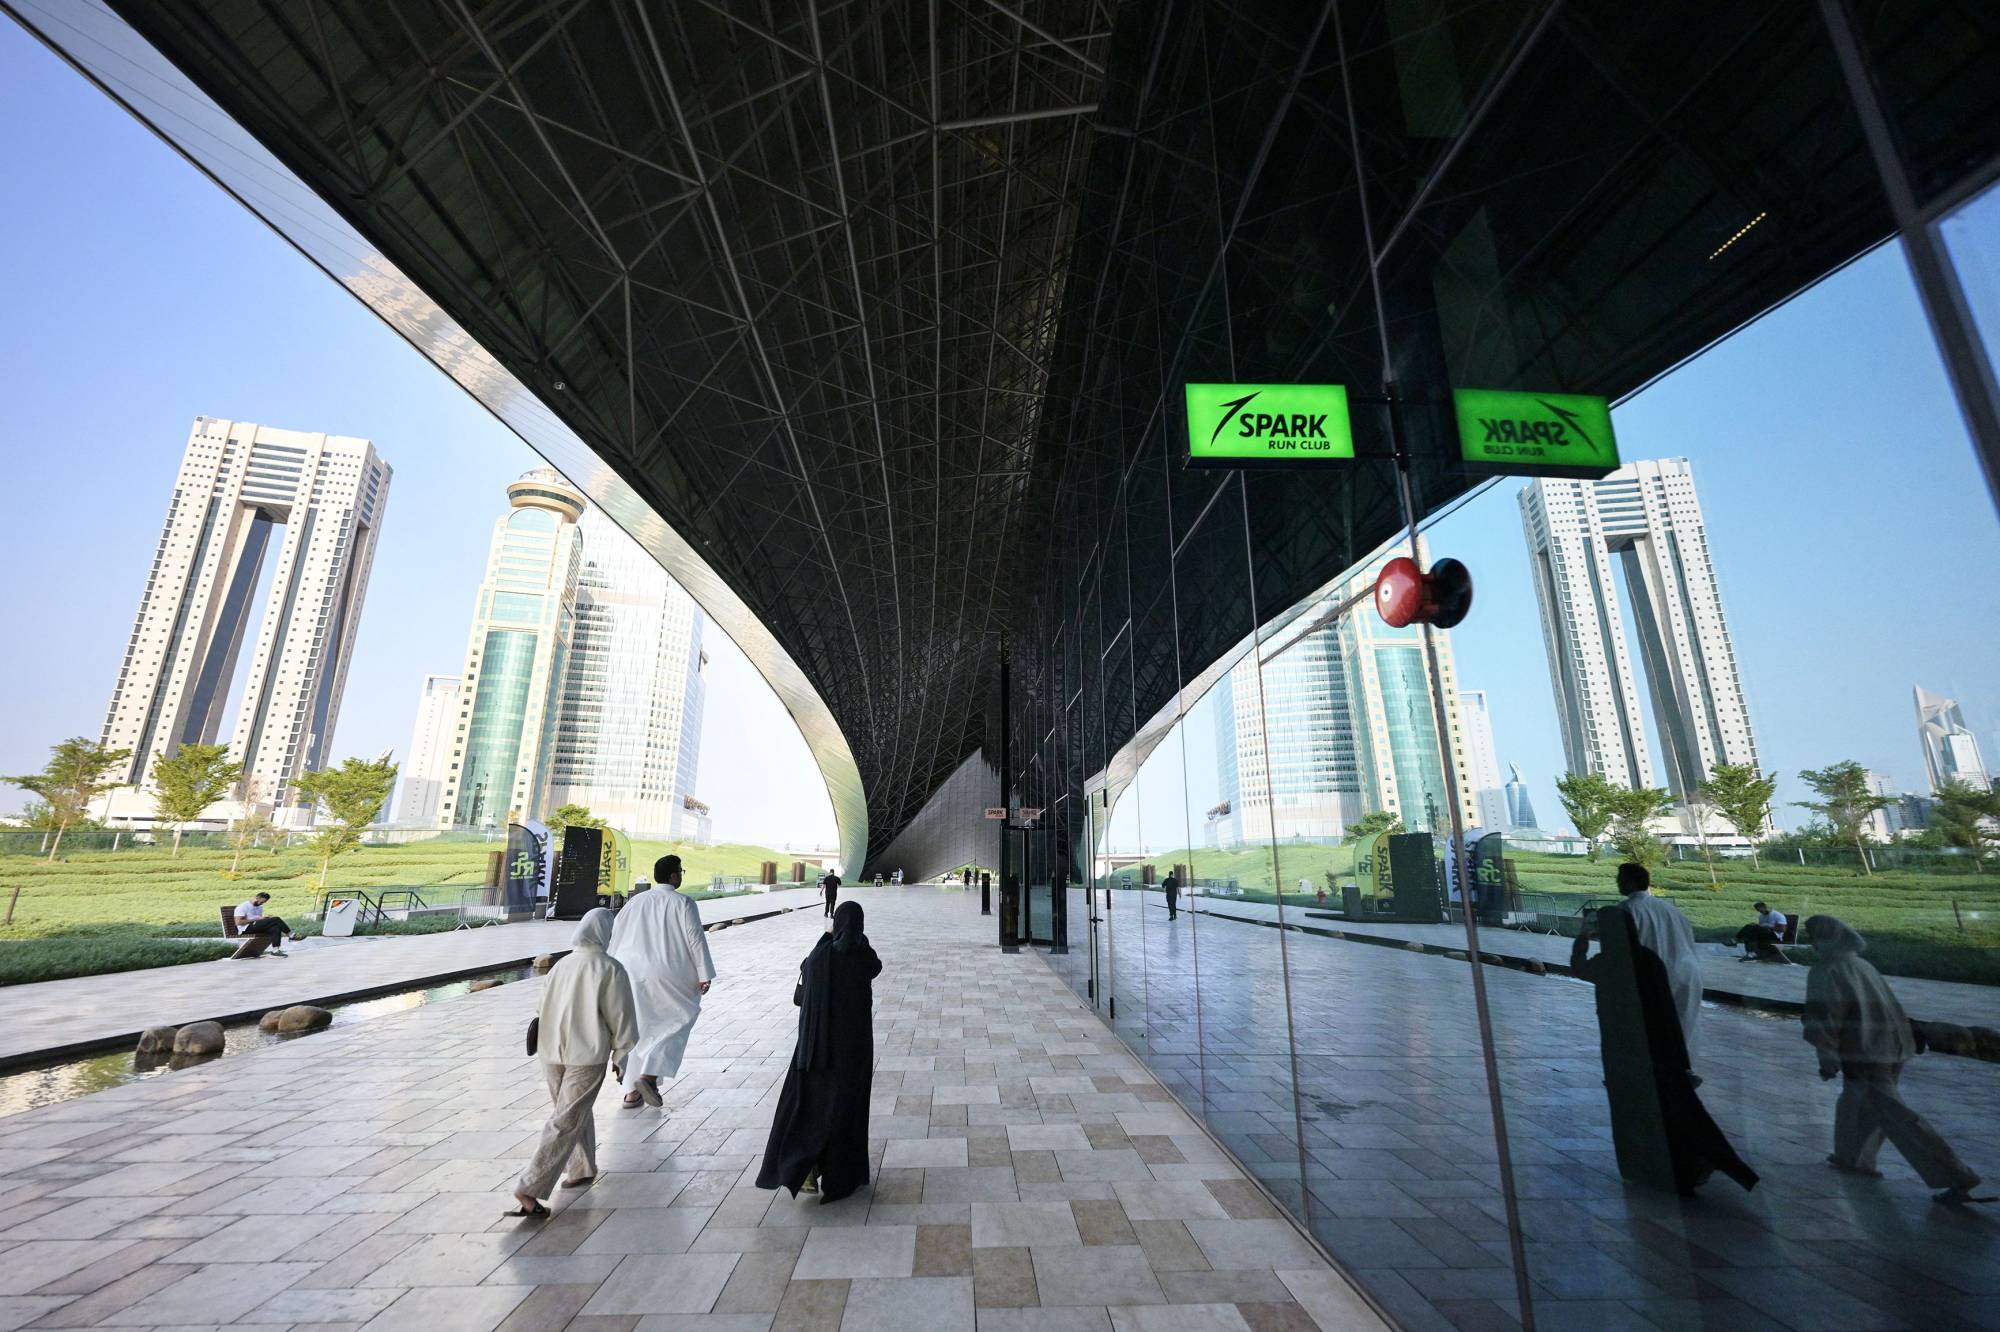
Kuwaitis at Shaheed park in Kuwait city. AFP

Artificial Intelligence: An Opportunity for Growth

Alongside the repercussions of the conflict, the report highlights a long-term transformation that could reshape the region's economies: the rise of artificial intelligence (AI).

According to Roberta Gatti, the World Bank's Chief Economist for the Middle East and North Africa, Afghanistan, and Pakistan, AI could enhance the productivity of 13 to 20 percent of jobs across the region, while fewer than 10 percent of jobs face a near-term risk of automation.

The report suggests that AI's primary impact in the region is likely to come through higher productivity rather than job losses, with workers and businesses that are able to adopt these tools effectively standing to benefit the most.

However, realizing these gains will require addressing a number of structural obstacles that continue to limit the spread of technology. These include the underrepresentation of the region's languages and data in global AI systems, low levels of AI adoption, gaps in human capital and infrastructure, and the limited dynamism of the private sector.

Regional Cooperation

The report notes that regional cooperation could be one of the most important avenues for maximizing the benefits of AI, particularly given the varying levels of technological capacity across countries in the region.

Leading countries such as Saudi Arabia and the United Arab Emirates could share their expertise in AI model development and governance with other regional economies, while middle-income countries could contribute local talent and data resources.

More fragile economies, meanwhile, could benefit from what the report describes as "small AI" solutions: low-cost technologies designed for specific purposes that can operate on basic mobile devices. These tools could help improve essential public services and support local businesses.

The report concludes that the region's ability to overcome the current shock will depend not only on the recovery of oil production and exports, but also on addressing structural weaknesses and investing in infrastructure and human capital. Such efforts would enable artificial intelligence to become an additional driver of productivity, economic growth, and long-term development.


AI Borrowing Binge Rattles US Markets

Tech giants are raising debt to finance the construction of data centers that power AI. Brandon Bell / GETTY IMAGES NORTH AMERICA/AFP
TT

AI Borrowing Binge Rattles US Markets

Tech giants are raising debt to finance the construction of data centers that power AI. Brandon Bell / GETTY IMAGES NORTH AMERICA/AFP

The world's richest companies can no longer rely on their massive cash piles alone to stay in the artificial intelligence race and have suddenly started borrowing massively in a shift that is sending repercussions across the world.

Rising US interest rates, including on the Treasury bonds that anchor the global economy, are sending tremors through the financial world, and some analysts point to the AI borrowing bonanza as one of the culprits, said AFP.

From next to nothing in 2024, tech sector borrowing has reached around $500 billion in the nine months since January, as Google, Meta, Amazon, Microsoft and others raise debt hand over fist to finance the chips, servers and data centers that power AI.

Goldman Sachs expects a further ramp-up in 2027, to $1.2 trillion.

"This is not something that we've seen before," said Chris Della Fave, senior vice president at fundraising advisory firm Post Oak Group, who estimates that AI now accounts for 25 percent of all corporate bond issuance, up from 4 percent two years ago.

In inflation-adjusted terms, the AI sector is expected to borrow more this year than US cable operators did to build out the entire internet, or than railroad companies did during the 19th-century US rail boom.

So far, investors have eagerly snapped up the chance to lend to the tech giants, but they have demanded returns that would have been unthinkable for such blue-chip companies not long ago.

Even Meta has had to offer more than 7 percent a year, while riskier cloud data center specialists have gone above 9 percent.

The impact reaches well beyond the companies building AI -- their debt is even starting to crowd out demand for the US government bonds that anchor the financial system.

An investor who might otherwise buy a US Treasury bond "might decide to buy Microsoft" instead, said Mark Malek, chief investment officer at Siebert Financial, referring to the tech giant's bonds.

That shift pushes up the rates Washington pays to borrow, he explained.

This adds to the other force driving up US borrowing costs: inflation, fueled by the war against Iran and high energy prices.

The interest rate on 10-year US government bonds -- Wall Street's benchmark and widely seen as the most important number in global finance, setting the tone for everything from mortgages to car loans -- is now above 5.30 percent, its highest level since 2002.

- 'Sharper correction' -

Adding to the volatility, hedge funds had piled into US government bonds like never before, holding 7 percent of all those in circulation at the end of 2025, though that share has since fallen.

Hedge funds, which place big bets on markets, move their money far faster than more cautious investors such as insurers and pension funds.

Even if the war and the oil situation stabilized, Della Fave said, "I wouldn't expect the yields to dramatically reduce, to be honest, because of this influence of the AI debt situation."

Beyond the rising cost of borrowing, some are questioning the risks of betting on an AI boom that could hit a wall, as the dot-com bubble did in 2000.

Even a moderate slowdown in the frenzied pace of construction, delays on certain projects or weaker-than-expected revenue growth could trigger a shock in financial markets, Malek warned.

In late September, the Bank of England's Financial Policy Committee warned that "the risk of a sharper correction persists," particularly if concerns about the pace of AI development or adoption hit earnings expectations.

In July, amid some second-guessing about the AI boom, the tech-heavy Nasdaq index fell nearly 7 percent.

Against this backdrop, cloud specialist Oracle is sometimes seen as a bellwether.

With massive debt ($125 billion), cash reserves that shrink every quarter and a possible delay on a huge data center project in New Mexico, several warning lights are flashing for Larry Ellison's group.

"Let's say Oracle has a problem... They can't pay for something," Malek said. Trouble with its debt "could trigger contagion" across AI finance as a whole, he added.


Gold Inches Lower as Firmer Dollar, Higher Yields Weigh

A woman passes in front of a gold shop in Hong Kong (AFP)
TT

Gold Inches Lower as Firmer Dollar, Higher Yields Weigh

A woman passes in front of a gold shop in Hong Kong (AFP)

Gold eased on Tuesday, pressured by a firmer US dollar and rising Treasury yields, though losses were limited by easing expectations of a Federal Reserve interest rate hike this month.

Spot gold slipped 0.3% to $4,128.69 per ounce by 0155 GMT. US gold futures were little changed at $4,156.00.

The dollar held firm, making greenback-denominated commodities more expensive for holders of other ‌currencies, Reuters said.

The 10- ‌and 30-year Treasury yields hit 24-year ‌highs ⁠on Monday as persistent ⁠bond market weakness weighed on sentiment.

"Fundamentals remain supportive of gold in the long term. The next big catalyst is likely to stem from geopolitical risk in the Middle East," said Kyle Rodda, senior financial market analyst at Capital.com.

"Alternatively, a significant change in US rate expectations could provide an ⁠impetus for the next break-out, so every ‌piece of price data will ‌be important."

Expectations of a US rate hike in October eased ‌after data on Friday showed US job growth slowed ‌more than expected in September and nonfarm payrolls for the prior two months were revised lower.

Traders are still pricing an 87% probability of an increase in December, according to CME's FedWatch Tool.

Higher ‌interest rates increase the opportunity cost of holding non-yielding gold.

Data showed US services sector activity ⁠slowed ⁠in September, while strong domestic demand stretched supply chains and pushed a measure of prices paid by businesses for inputs to its highest level in more than four years, suggesting inflation could remain elevated into 2027.

Elsewhere, Yemeni government forces staged a lightning advance to retake the coast around the Bab el-Mandeb Strait up to the city of Mocha, the government said, pushing the Iran-backed Houthis out of most of the areas they seized last month.

Among other metals, spot silver fell 0.6% to $60.67, platinum lost 0.7% to $1,710.08 and palladium eased 0.2% to $1,170.15.