First Saudi Chief Executives Association

First Saudi Chief Executives Association
TT

First Saudi Chief Executives Association

First Saudi Chief Executives Association

Saudi Minister of Human Resources and Social Development Engineer Ahmed al-Rajhi approved the establishment of the nation’s inaugural Chief Executives Association.

The Association, led by Mansour al-Shathri, has already convened its initial meeting to discuss various items on its agenda and outline its strategy for the upcoming phase.

The meeting discussed various topics, including an in-depth exploration of the Association’s working strategy for the forthcoming period.

Khalid al-Omar has been named the Chief Executive Officer and will be responsible for establishing the executive committee.

Shathri revealed that the newly established Association will serve as a professional corporation designed to facilitate the exchange of experience and knowledge and transfer best practices to enhance the capabilities and skills of its members.

The organization aims to foster increased communication with leaders across various sectors while contributing to the development of administration and leadership through local and international knowledge transfer.

He further stated that the Association is committed to engaging with leaders to give them opportunities to become active, effective, and influential members contributing to economic growth.

Shathri pointed out that the Association’s strategy is poised to achieve a set of objectives, including raising awareness about its field of work, transferring expertise, activating the role of CEOs in serving the Saudi business sector, launching initiatives, and establishing partnerships to secure a prestigious status for the Kingdom.

For his part, Omar clarified that the entity is the first Saudi Association specializing in gathering CEOs, noting that its primary goals include promoting positive administrative values encouraging creativity, innovation, commitment, achievement, empowerment, integrity, and openness.

The Association is also dedicated to providing professional development programs, conducting developmental studies and research on CEOs, hosting local and international executive leaders for knowledge transfer, and sharing expertise.

The newly-named CEO explained that the Association aims to be a distinguished and progressive local organization, delivering notable outcomes and adopting the best international practices in line with similar global associations.

Through its role, the Association plans to offer a range of specialized products and launch initiatives, develop partnerships with both public and private sectors, and bridge communication gaps to enhance efficiency and effectiveness.

He called on all executive leaders to join the Association, representing a core group of decision-makers in organizations and advancing development in the Kingdom through their specialized community.

Engagement is crucial for achieving strategic goals in experience exchange, inspiration from various experiences, overcoming challenges, disseminating knowledge, and creating enabling investment opportunities that positively impact the national economy.


Oil Prices Fall on Easing Fears Over Saudi Supply Disruption

FILE PHOTO: Vessels near the Strait of Hormuz, as seen from Musandam, Oman, September 2, 2026. REUTERS/Stringer/File Photo
TT

Oil Prices Fall on Easing Fears Over Saudi Supply Disruption

FILE PHOTO: Vessels near the Strait of Hormuz, as seen from Musandam, Oman, September 2, 2026. REUTERS/Stringer/File Photo

Oil prices fell 2% on Friday, extending losses for a third straight session as easing concerns over Saudi supply disruptions outweighed anxiety about a widening of conflict across the Middle East.

Brent crude futures fell by $2.14, or 2%, to $102.68 a barrel by 0806 GMT. US West Texas Intermediate futures fell $1.83, or 1.8%, to $100.08, Reuters reported.

Benchmark Brent prices are on track for their first weekly loss in three.

Prices climbed to close to four-month highs earlier in the week after sources said crude loadings ⁠at Saudi Arabia's Red Sea export hub of Yanbu had been suspended and Riyadh cancelled some deliveries to Europe after its East-West pipeline was damaged in an attack last week.

However, prices have cooled since on reports that Saudi Arabia was seeking to restore about half the capacity of its East-West oil pipeline within days.

Saudi Arabia has sold about 60 million barrels of crude from its Gulf port of Ras Tanura inside the Strait of Hormuz for loading via ship-to-ship transfer at the Omani port of Sohar this month and next, multiple trade sources said on Friday.

The rebound in Saudi Aramco's exports from inside the Gulf to between 1 million to 1.5 million barrels per day on average, similar to or slightly higher than August's levels, has cooled global oil prices as it could make up for some of the ⁠volume lost at its port of Yanbu.

Chinese and South Korean refiners are among the top buyers of the spot supplies, while some volumes will be going to India and Japan, said the sources, who spoke on condition of anonymity.

"Recent efforts ‌to restore Saudi export capacity have reduced some of the immediate supply ‌anxiety," said Priyanka Sachdeva, head of market insights at Phillip Nova.


ECB's Lagarde Keeps Door Open to Early Exit

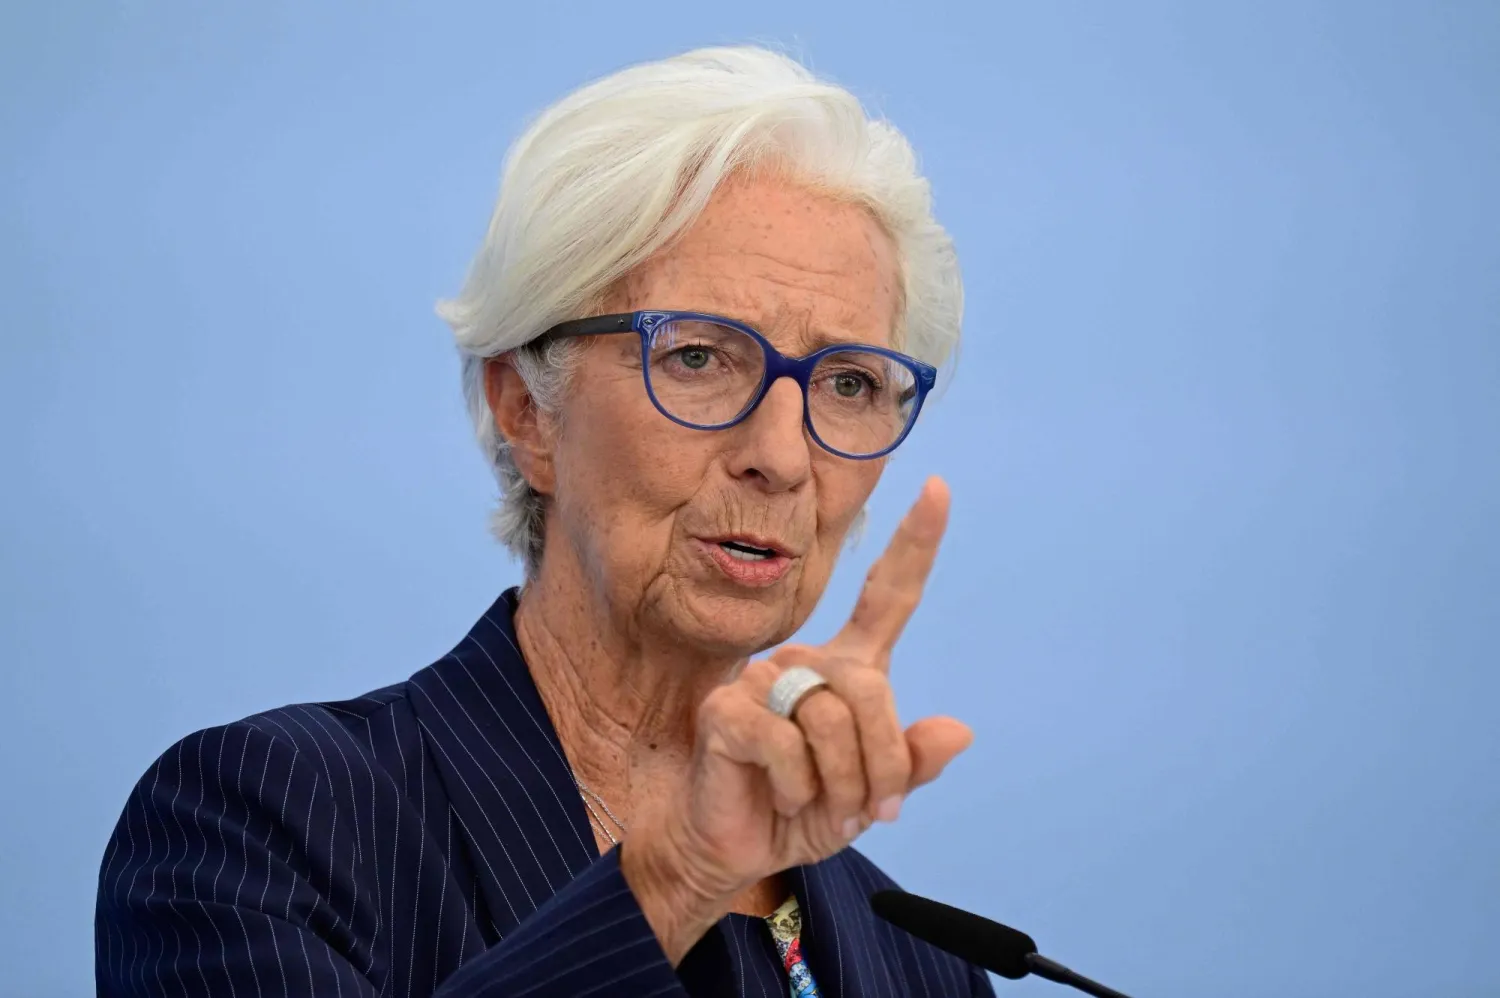
European Central Bank (ECB) President Christine Lagarde addresses a press conference after a meeting of the Governing Council of the European Central Bank (ECB) in Berlin on September 10, 2026. (Photo by John MACDOUGALL / AFP)
TT

ECB's Lagarde Keeps Door Open to Early Exit

European Central Bank (ECB) President Christine Lagarde addresses a press conference after a meeting of the Governing Council of the European Central Bank (ECB) in Berlin on September 10, 2026. (Photo by John MACDOUGALL / AFP)

European Central Bank President Christine Lagarde on Friday kept the door open to leaving her post early, replying "we'll see" when asked if she would remain in the position until her term ends ‌in October 2027.

"I ‌leave in ‌2027," ⁠Lagarde told Irish ⁠national broadcaster RTE in response to a question on rumors of her early resignation that have persisted for most ⁠of this year.

When asked ‌if ‌that meant October 2027, ‌Lagarde replied: "We'll see."

"What I ‌can tell you at this point is that whatever the time, it will be ‌handled in the most professional way as ⁠it should ⁠be," she added.

Sources told Reuters this week that France would back Dutchman Klaas Knot to succeed Lagarde as part of a bargain in which a French candidate would be picked for chief economist.


5 Countries Want Smaller Growth of Next EU Budget, Spain Offers Ideas

FILE PHOTO: European Union flags flutter outside the European Commission headquarters in Brussels, Belgium April 29, 2026. REUTERS/Yves Herman/File Photo
TT

5 Countries Want Smaller Growth of Next EU Budget, Spain Offers Ideas

FILE PHOTO: European Union flags flutter outside the European Commission headquarters in Brussels, Belgium April 29, 2026. REUTERS/Yves Herman/File Photo

Germany, Denmark, Finland, the Netherlands and Austria said on Friday the European Union's budget for 2028-2034 must be "several hundred billion euros" smaller than the €2 trillion proposed by the European Commission, drawing battle lines before EU budget talks come to a head in the next three months.

The leaders of the five countries, among the biggest net contributors to the budget, wrote in a joint op-ed in Politico that EU taxpayers ⁠cannot keep paying ⁠more to pay for both old and new priorities.

"It (the budget) is too focused on subsidies and transfers allocated largely in advance, leaving too little room for what Europe urgently needs: common investment in security and defense, competitiveness, innovation, and the fight against irregular migration," the five leaders said.

Net beneficiaries of the EU budget are concerned that ⁠would reduce EU funds for farmers and for equalizing standards of living between the poorer and richer regions of Europe -- a major political concern before parliamentary elections next year in France, Italy, Spain, Poland, Greece, Finland, Slovakia and Estonia.

The European Commission has proposed the budget should amount to €2 trillion or 1.26% of EU Gross National Income (GNI), of which some 168 billion, or 0.11% of GNI, is to service the EU's borrowing for the post-pandemic recovery fund. The five leaders called the proposed nominal increase of around 60% over the 2021-2027 budget "simply not ⁠realistic."

"This is ⁠why we call for a balanced cut to the Commission’s proposal of several hundred billion euros," Reuters quoted them as saying.

To help find a solution, Spain proposed to change the repayment schedule of part of the EU post-pandemic borrowing, linking it to economic growth and spreading it out over a longer period. This, according to Spanish Economy Minister Carlos Cuerpo, would free up some €70 billion.

"An annual payment of about 0.06% of EU GDP would retire the debt by 2058, the deadline agreed by member states," Cuerpo said.

EU governments will discuss the next EU budget at summits in October, November and December in an effort to get a deal before the end of the year.