World Bank: Middle East Tensions Threaten to Increase Global Inflationhttps://english.aawsat.com/business/4985901-world-bank-middle-east-tensions-threaten-increase-global-inflation
World Bank: Middle East Tensions Threaten to Increase Global Inflation
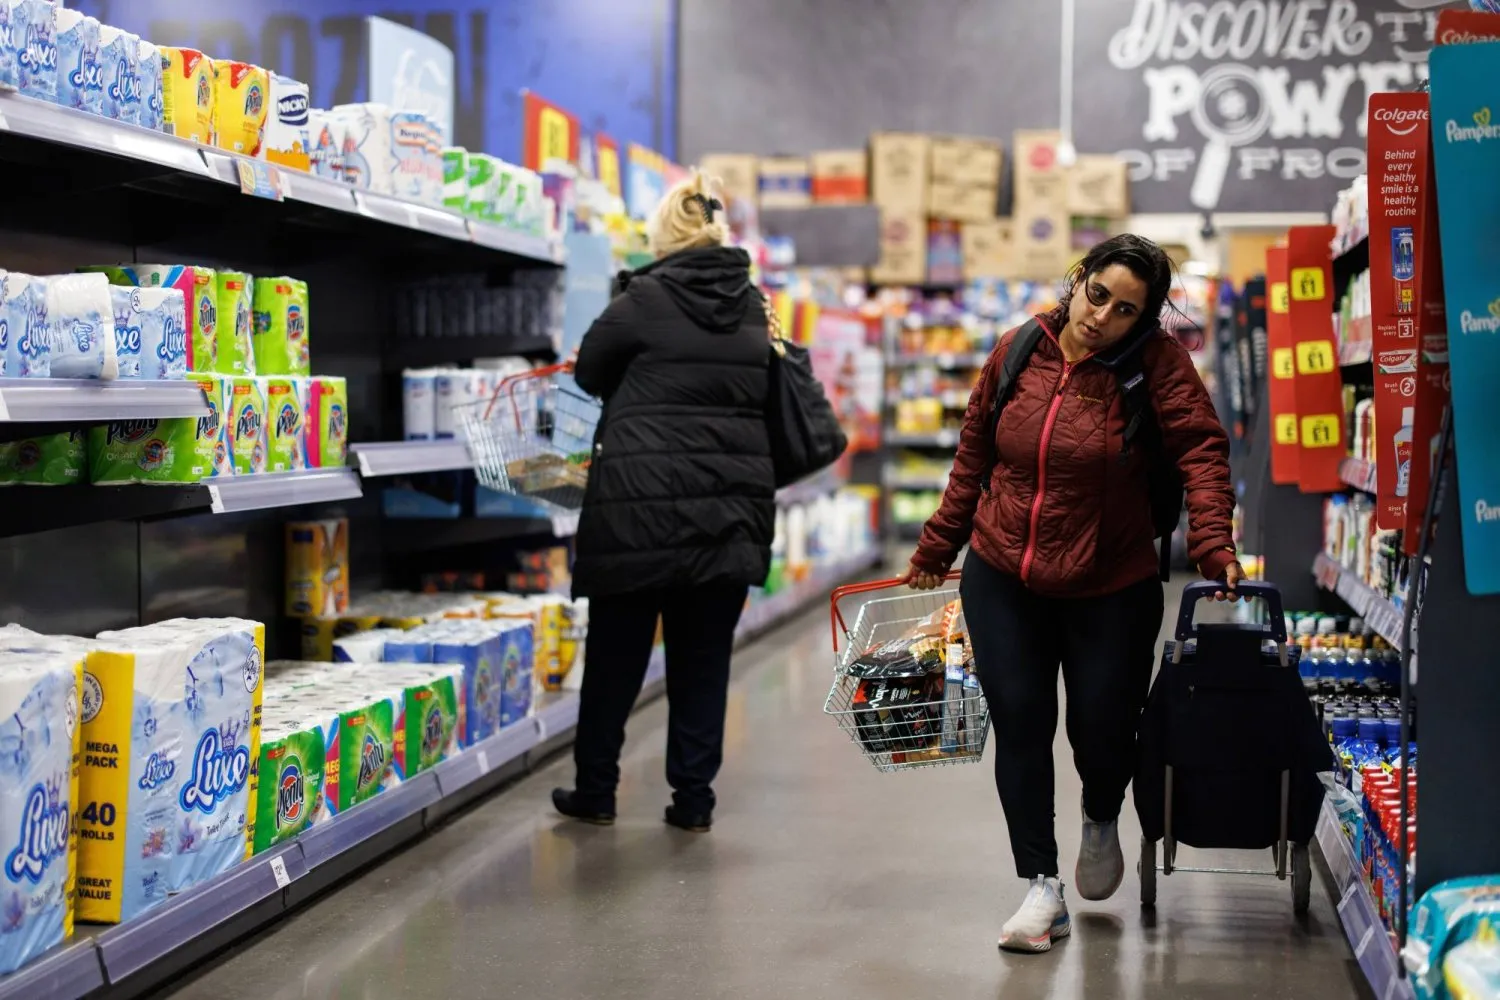
Consumers shopping in a supermarket in the British capital (EPA)
Global commodity prices are leveling off after a steep descent that played a decisive role in whittling down overall inflation last year, which could make it harder for central banks to cut interest rates quickly, the World Bank (WB) said in a report on Thursday.
The report also found that a major outbreak of conflict in the Middle East could halt the inflationary decline that has occurred over the past two years.
“Between mid-2022 and mid-2023, global commodity prices plummeted by nearly 40%. This helped to drive most of the roughly 2-percentage-point reduction in global inflation between 2022 and 2023,” according to the WB’s latest Commodity Markets Outlook.
Since mid-2023, however, the WB’s index of commodity prices has remained essentially unchanged.
“Assuming no further flare-up in geopolitical tensions, the Bank’s forecasts call for a decline of 3% in global commodity prices in 2024 and 4% in 2025,” the report showed.
That pace will do little to subdue inflation that remains above central bank targets in most countries. It will keep commodity prices about 38% higher than they were on average in the five years before the COVID-19 pandemic, it added.
“Global inflation remains undefeated,” said Indermit Gill, the World Bank Group’s Chief Economist and Senior Vice President.
“A key force for disinflation—falling commodity prices—has essentially hit a wall. That means interest rates could remain higher than currently expected this year and next,” he added, affirming that the world is at a vulnerable moment where a major energy shock could undermine much of the progress in reducing inflation over the past two years.
Meanwhile, persistently high geopolitical tensions over the past two years have propped up the price of oil and many other critical commodities even as global growth has slowed.
The report said the price of Brent crude oil, for example, surged to $91 per barrel earlier this month—nearly $34 per barrel above the 2015-2019 average.
Also, the Bank’s forecasts indicate that Brent prices will average $84 per barrel in 2024 before declining to an average of $79 in 2025, assuming no conflict-related supply disruptions.
“If the conflict in the Middle East were to escalate further, however, oil-supply disruptions could push up global inflation,” the report found.
It said a moderate conflict-related supply disruption could raise the average Brent price this year to $92 per barrel. A more severe disruption could see oil prices surpass $100 per barrel, raising global inflation in 2024 by nearly one percentage point.
“A striking divergence is emerging between global growth and commodity prices: despite relatively weaker global growth, commodity prices will most likely remain higher in 2024-25 than in the half-decade before the COVID-19 pandemic,” said Ayhan Kose, the World Bank Group’s Deputy Chief Economist and Director of the Prospects Group.
He added,“One critical factor behind this divergence relates to heightened geopolitical tensions that are keeping upward pressure on prices of major commodities and stoking risks of sharp price movements. Central banks must remain alert about the inflationary implications of commodity-price spikes amid elevated geopolitical tensions.”
Meanwhile, the average price of gold—a popular choice for investors seeking “safe haven”—is expected to hit a record in 2024 before moderating slightly in 2025.
Gold holds a special status among assets, often rising in price during periods of geopolitical and policy uncertainty, including conflicts. Strong demand from several developing-country central banks, along with heightened geopolitical challenges, is expected to bolster gold prices throughout 2024.
The report further noted that an escalation of the conflict in the Middle East could also drive up prices of natural gas, fertilizers, and food, the report notes.
The region is a crucial gas supplier—20% of global liquefied natural gas (LNG) trade transits the Strait of Hormuz. If the LNG supply were interrupted, fertilizer prices would also rise substantially, likely driving up food prices, it said.
The Bank’s baseline forecast, however, is for overall food prices to decline somewhat—by 6% in 2024 and 4% in 2025. Fertilizer prices are expected to fall by 22% in 2024 and 6% in 2025.
The WB report then found that accelerating investment in green technologies has bolstered prices of key metals that are critical for the global clean-energy transition.
It said prices of copper—necessary for electricity-grid infrastructure and electric vehicles—surged to a two-year high this month and they are expected to rise 5% in 2024 before stabilizing in 2025.
Meanwhile, prices of aluminum are forecast to rise by 2% in 2024 and 4% in 2025, bolstered in particular by the production of electric vehicles, solar panels, and other renewable-power infrastructure.
A trader works on the trading floor at the New York Stock Exchange (NYSE) in Manhattan, New York City, US, November 11, 2022. REUTERS/Andrew Kelly/File Photo
A trader works on the trading floor at the New York Stock Exchange (NYSE) in Manhattan, New York City, US, November 11, 2022. REUTERS/Andrew Kelly/File Photo
Wall Street stocks slipped early Thursday, after oil prices soared on reports that the United States could launch fresh attacks on Iran before key midterm elections.
The Dow Jones Industrial Average dipped 0.2 percent to 51,074.31, while the broad-based S&P 500 Index lost 0.3 percent to 7,776.28.
The tech-focused Nasdaq Composite Index retreated 0.5 percent to 27,405.11, AFP reported.
The gloomier start was "based on two factors that have been haunting the market: both oil prices rising sharply and also (bond) yields that are returning to yesterday's peak levels," said Peter Cardillo of Spartan Capital Securities.
He told AFP that these will be an "ongoing problem for the market in the near term."
Cardillo said that oil prices have jumped as US President Donald Trump said he did not want to deal with Iran.
"And now it looks as though there's been a shift in strategy from an economic squeeze on the Iranian economy to a new round of massive bombing," he warned.
After reports that Washington could open new attacks against Iran, international benchmark Brent North Sea crude rallied to $105.46 per barrel.
The main US contract, West Texas Intermediate rose to $92.82 per barrel before cooling slightly.
Meanwhile, the yield on the 10-year Treasury note advanced to 5.3 percent and that on the 30-year note was at 5.7 percent.
A Year After Riyadh Halted Rent Hikes, the Market Tests a New Balancehttps://english.aawsat.com/business/5327399-year-after-riyadh-halted-rent-hikes-market-tests-new-balance
A Year After Riyadh Halted Rent Hikes, the Market Tests a New Balance
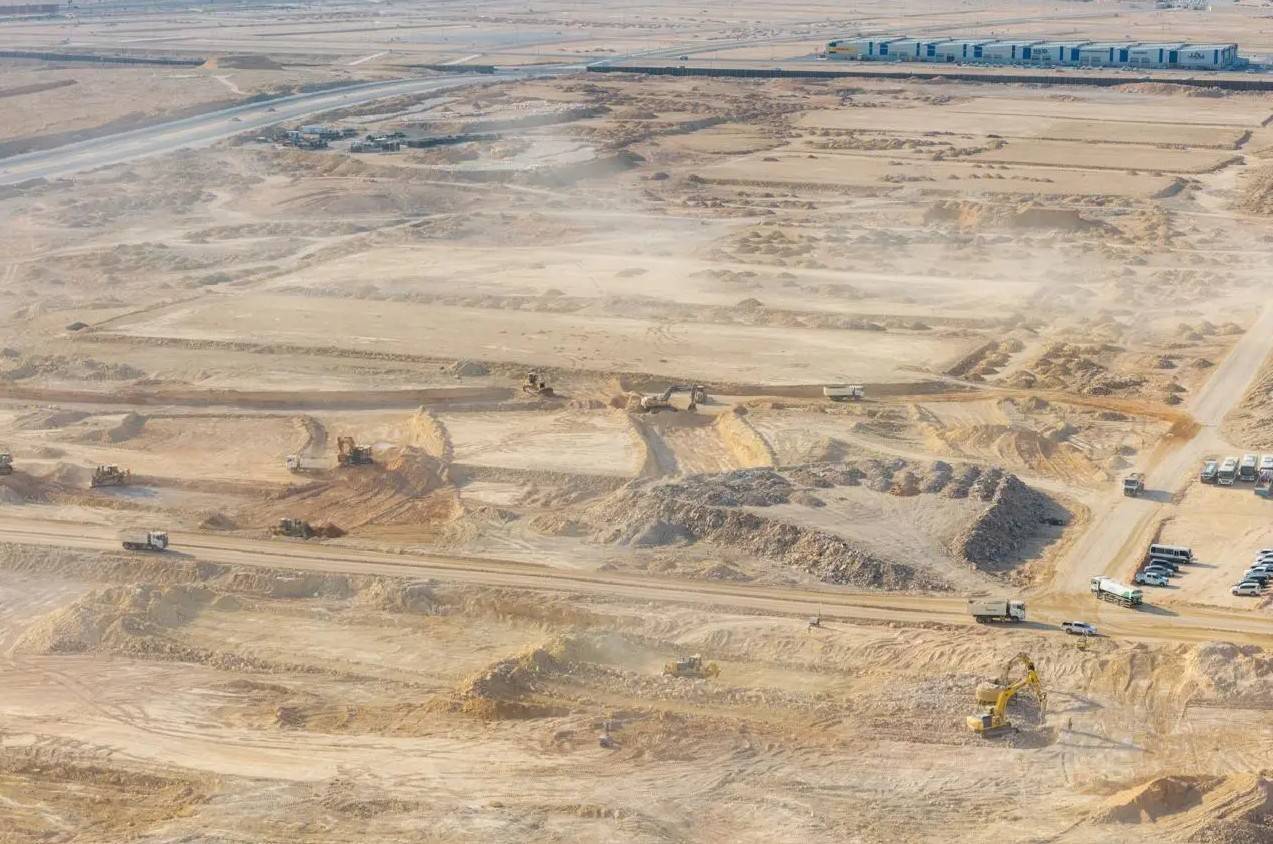
Development work on plots during the first year of the Real Estate Balance Program in Riyadh (SPA)
A year after regulations freezing rent increases began to take effect, the rental market in Riyadh has begun to show a clear shift in the trajectory of prices. Residential rents grew by 4.5 percent in August 2026, the slowest pace of increase in more than three years, while the share of household income absorbed by rent declined to about 15 percent, from more than 17.5 percent a year earlier.
These developments point to a gradual easing of the price pressures that drove rents to high levels in recent years, but they are not enough on their own to conclude that the market has entered a sustainable equilibrium. Rental activity continues to grow, while the market still needs to absorb new supply and determine the impact of the regulations on the decisions of investors, developers and tenants.
The regulatory provisions governing the relationship between landlords and tenants in Riyadh were issued on September 25, 2025, pursuant to the directive of Crown Prince and Prime Minister Mohammed bin Salman to take measures to achieve balance in the capital’s real estate sector, with the approval of the Council of Ministers and by royal decree. The provisions were later published in the official gazette, Umm Al-Qura, and took effect on November 7 of the same year. They remain in effect for five years and provide for a freeze on annual rent increases for residential and commercial properties within Riyadh’s urban boundaries, in addition to regulating rents for vacant properties that had previously been leased and setting rules governing contract renewals and evictions.
These provisions formed part of a broader package of measures aimed at restoring balance to the capital’s real estate market. The package included increasing the supply of residential land, developing the system of white land and vacant property fees, strengthening the regulation of rental relationships, and raising levels of documentation and transparency.
Development works on plots during the first year of the Real Estate Balance Program in Riyadh (SPA)
About a year after the provisions took effect, the capital’s rental market has begun to show signs of gradual repricing, with slower rent growth and a decline in the burden of rent on household income. However, the extent to which the market moves toward a more sustainable equilibrium will remain linked to the trajectory of new supply, development and financing costs, and households’ ability to afford housing.
The latest available data indicate that residential rents in Riyadh rose by 4.5 percent year-on-year in August 2026, marking the 12th consecutive month of slower growth and the lowest pace of increase in more than three years, according to an analysis based on data from the General Authority for Statistics.
Although rents continued to rise year-on-year, the slower pace reflects a gradual easing of the price pressures that the capital experienced in recent years, alongside a package of government measures aimed at restoring balance to the real estate market.
The regulation of the rental market was part of this package, which included increasing the supply of residential land, developing the system of white land and vacant property fees, as well as strengthening the regulation of rental relationships and raising levels of documentation and transparency in the market.
In an indicator directly linked to households’ ability to afford housing costs, the share of rent in household income in Riyadh declined to about 15 percent, compared with more than 17.5 percent in September 2025.
Abdullah Al-Hammad, CEO of the General Real Estate Authority, said last September that this decline was one of the initial effects measured from the real estate balance decisions in the capital.
This indicator is particularly significant because it measures the share of rent in household income, providing a clearer reading of changes in housing affordability and the impact of market movements on tenants.
This coincided with a continued slowdown in housing-related inflation across the Kingdom. The growth rate of prices in the housing, water, electricity, gas and other fuels category declined to 3.9 percent year-on-year in August, from 4.2 percent in July.
By contrast, the slowdown in price growth was not accompanied by a similar contraction in rental activity across the Kingdom. The number of rental transactions rose to about 446,300 in August, compared with 325,200 in the same month of 2025, an annual increase of 37 percent.
The value of rental transactions also increased by 32 percent to 10.62 billion riyals ($2.83 billion), compared with about 8.03 billion riyals a year earlier. The residential sector accounted for about 343,700 transactions, an increase of 36 percent, while the value of its transactions rose 28 percent to 5.59 billion riyals.
Although these figures reflect the performance of Saudi Arabia’s rental market as a whole and do not separately measure the impact of the measures implemented in Riyadh, they indicate that slower rent growth has not, so far, been accompanied by a broad contraction in rental activity.
Balance or a Transitional Phase?
A year after the regulations were implemented, the picture raises the question of whether the current indicators represent the beginning of a sustainable equilibrium in Riyadh’s rental market, or whether they reflect a transitional phase during which the market is reshaping price levels, returns, and the behavior of tenants and investors. According to real estate specialists, determining the direction of this trend will depend on developments in new supply, development and financing costs, and households’ ability to afford housing in the coming period.
Real estate expert and commentator Abdullah Al-Mousa told Asharq Al-Awsat that the current indicators reflect a tangible impact from the latest regulatory measures on Riyadh’s rental market, particularly the freeze on annual increases. He noted that slower rent growth and the decline in the burden of rent on household income reflect an easing of some of the price pressures that the capital has experienced in recent years.
He explained that this improvement cannot be attributed solely to the freeze on increases, but comes within a comprehensive package of measures that included regulating the relationship between landlords and tenants, fixing rents under specific regulations, increasing the supply of land, developing the white land fee system, and strengthening documentation and transparency in the market.
Al-Mousa said it was too early to consider the rental market to have reached “full equilibrium,” saying that what is currently taking place is closer to a transition from a period of rapidly rising prices toward stability, repricing and testing new levels of equilibrium.
He added that sustainable equilibrium is not measured by slower prices alone, but by the market’s ability to provide sufficient supply, maintain affordable housing costs relative to household income, and keep occupancy rates stable while ensuring that investment in the rental sector remains attractive.
Regarding the impact of the regulations on the behavior of landlords and tenants, Al-Mousa noted that their effect may be behavioral and contractual as much as it is related to prices. They give tenants greater ability to anticipate their future obligations and limit sudden increases, which could encourage them to remain in a unit for longer periods.
At the same time, the regulations may encourage landlords to place greater priority on tenant stability and regular payment rather than relying on raising rents at every renewal.
He noted that the regulations have also reshaped the way units are priced and negotiated, particularly for properties entering the market for the first time, where the initial rent becomes more important in determining the subsequent course of the contract. This is prompting owners and developers to study pricing more carefully and link it to the unit’s location, quality, level of services and the value it provides to the tenant.
Al-Mousa considered that this shift could, over the long term, move competition in the rental market away from focusing on raising prices and toward improving the quality of real estate products and retaining tenants for longer periods. This would reflect a market moving toward greater competition over value and stability, rather than price alone.
Reshaping Investment Economics
Real estate expert and marketer Saqr Al-Zahrani told Asharq Al-Awsat that rental regulations are likely to reshape the economics of investment in the residential sector, rather than simply limiting investment activity. He explained that limited growth in rental revenues, alongside rising land, financing and construction costs, will push investors to scrutinize target returns more closely and focus on assets capable of generating stable cash flows and achieving greater operational efficiency.
He added that the next phase could see a greater shift by institutional investors toward towers and integrated, professionally managed residential complexes, benefiting from economies of scale in reducing operating costs, improving occupancy efficiency, and diversifying products and services. At the same time, standalone residential units may become less attractive as rental assets, as a larger share of them shifts toward ownership by end users.
According to Al-Zahrani, demand for housing in Riyadh will not necessarily decline, but it may become more selective, with tenants paying greater attention to balancing price, location, space, product quality and services. Landlords, meanwhile, will rely more heavily on asset quality and sustainable occupancy rather than relying solely on rent growth.
He noted that among the key indicators that should be monitored over the next two years are rent growth rates, the volume of new supply, occupancy and vacancy rates, net investment returns, the movement of households from renting to homeownership, the length of time units remain on the market, and the ratio of housing costs to household income.
Al-Zahrani said one of the most significant potential shifts is the movement of some investment away from individual residential units toward integrated residential assets, particularly as projects capable of relying on actual local demand and generating stable cash flows become increasingly important.
At the same time, he warned that continued increases in development costs, combined with limited rent growth, could prompt some investors to reduce the supply allocated for rental or redirect capital toward homeownership projects.
Conversely, improved homeownership affordability could gradually encourage some tenants to shift from bearing rental costs toward building homeownership, potentially reshaping the pattern of demand in the capital’s housing market.
Maersk Raises Emergency Fuel Surcharge Due to Middle East Conflicthttps://english.aawsat.com/business/5327326-maersk-raises-emergency-fuel-surcharge-due-middle-east-conflict
FILE PHOTO: A truck transports a Maersk container at APM Terminals at the Port of Los Angeles, California, US, March 4, 2026. REUTERS/Mike Blake/File Photo
Maersk Raises Emergency Fuel Surcharge Due to Middle East Conflict
FILE PHOTO: A truck transports a Maersk container at APM Terminals at the Port of Los Angeles, California, US, March 4, 2026. REUTERS/Mike Blake/File Photo
Danish shipping group Maersk said on Thursday it was increasing its emergency fuel surcharge (EFS) on all export collections and import deliveries due to the ongoing conflict in the Middle East.
Oil prices rose on Thursday on worries about supply from the Middle East region amid an increase in attacks on shipping in the Gulf and the Strait of Hormuz, while the US cut output as a hurricane menaced offshore production.
Maersk said in a statement it was increasing its EFS to 20% as of October 12, and that it would continue to review the surcharge regularly.
لم تشترك بعد
انشئ حساباً خاصاً بك لتحصل على أخبار مخصصة لك ولتتمتع بخاصية حفظ المقالات وتتلقى نشراتنا البريدية المتنوعة