Oil Edges Lower on Surprise Build in US Crude, Gasoline Stockshttps://english.aawsat.com/business/5048106-oil-edges-lower-surprise-build-us-crude-gasoline-stocks
Oil Edges Lower on Surprise Build in US Crude, Gasoline Stocks
The sun is seen behind a crude oil pump jack in the Permian Basin in Loving County, Texas, US, November 22, 2019. REUTERS/Angus Mordant
Oil prices slipped in early Asian trading on Wednesday following a brief rebound in the previous session after industry data showed an unexpected build in US crude oil and gasoline inventories, offsetting global oil supply concerns.
Brent crude futures fell 21 cents, or 0.27%, to $76.27 a barrel by 0020 GMT. US West Texas Intermediate crude slipped 25 cents, or 0.34%, to $72.95 per barrel.
US crude oil, gasoline and distillate inventories rose last week, according to market sources citing American Petroleum Institute figures on Tuesday, Reuters reported.
Benchmarks slipped accordingly. Both WTI and Brent had bounced off multi-month lows to settle higher in the previous session.
The API figures showed crude stocks were up by 176,000 barrels in the week ended Aug. 2, the sources said, speaking on condition of anonymity. Analysts polled by Reuters had expected crude stocks to fall by 700,000 barrels.
Gasoline inventories rose by 3.313 million barrels against analysts' expectations for a 1 million bbl draw, while distillate stocks rose by 1.217 million barrels, a bigger build than anticipated.
The US Energy Information Administration is due to release weekly inventory data at 10:30 a.m. (1430 GMT) on Wednesday.
On Monday, Brent futures slumped to their lowest since early January and WTI futures had touched their lowest since February, as a global stock market rout deepened on growing concerns of a potential recession in the US, the world's largest petroleum consumer.
However, both benchmarks broke a three-session declining streak on Tuesday as tensions in the Middle East stoked supply concerns, supporting prices.
Iran's vow of retaliation against Israel and the US following the killing of two militant leaders has raised concerns that a wider war is brewing in the Middle East.
"Any escalation of the conflict in the Middle East could see a greater risk of disruptions to supplies from the region," ANZ analyst Daniel Hynes said.
Lower production at Libya's 300,000 barrel-per-day (bpd) Sharara oilfield is also adding to concerns of supply shortages.
Global oil inventories decreased by around 400,000 bpd in the first half this year, according to US Energy Information Administration (EIA) estimates published on Tuesday. It expects stockpiles to decline by around 800,000 bpd in the second half of the year.
PIF Launches Tawrid to Provide Supply-Chain Financing Products in Saudi Arabiahttps://english.aawsat.com/business/5320489-pif-launches-tawrid-provide-supply-chain-financing-products-saudi-arabia
PIF Launches Tawrid to Provide Supply-Chain Financing Products in Saudi Arabia
PIF Tower at the King Abdullah Financial District in Saudi Arabia’s capital, Riyadh (Asharq Al-Awsat)
The Public Investment Fund (PIF) on Sunday announced the launch of Tawrid Company for Financing Solutions, an innovative digital platform providing supply-chain financing products to companies in the Saudi Arabian market. Tawrid has obtained the Saudi Central Bank (SAMA) permit to operate under the regulatory Sandbox environment.
The financial services industry is a strategic enabler of the six ecosystems that PIF announced recently as part of its 2026-2030 strategy.
Supply-chain financing products help companies to fund their broader activities. Tawrid’s digital offering will further strengthen the Saudi private sector, particularly small and medium-sized enterprises, SPA reported.
Tawrid will play a significant role in connecting buyers, suppliers, and funders through its digital platform. It will offer products such as early settlement options against approved invoices, enabling businesses to expand their operations, enhance their working capital efficiency, and improve their liquidity management.
The launch of Tawrid is in line with PIF’s strategy to increase the Saudi private sector’s contribution to PIF’s projects and portfolio companies and to grow the private sector’s share of the local economy. Its platform will enable local banks registered on its network to engage with registered suppliers, strengthening supply chains and further supporting the diversification of financial services and the digitalization of trade in Saudi Arabia.
PIF’s investment in supply-chain financing is a natural evolution that builds on its efforts to advance the growth, resilience, and robustness of supply chains in the Saudi market. PIF has expanded opportunities for local suppliers and stimulated them to develop their capabilities in line with PIF’s strategic objectives to engage the private sector and enable it to contribute to a more diversified economy with deep, local, tech-enabled supply chains.
Head of Financial Institutions in MENA Investments at PIF Sultan Alsheikh said: “Tawrid will make Saudi supply chains stronger and more resilient by further enabling companies to access financing and improve their liquidity management. Its supply-chain financing products will enable businesses to operate with greater agility and efficiency, creating opportunities for the Saudi private sector in particular.”
Tawrid has started operations and has already signed binding agreements with local banks and companies, including Gulf International Bank (GIB), Saudi National Bank (SNB), Banque Saudi Fransi (BSF), ROSHN Group and Nesma & Partners.
PIF is one of the world’s most impactful investors, with a long-term investment strategy to further drive the economic transformation of Saudi Arabia and deliver sustainable financial returns.
IFAD President to Asharq Al-Awsat: Sanctions Are the Biggest Challenge for Remittance Channelshttps://english.aawsat.com/business/5320485-ifad-president-asharq-al-awsat-sanctions-are-biggest-challenge-remittance-channels
IFAD President to Asharq Al-Awsat: Sanctions Are the Biggest Challenge for Remittance Channels
Alvaro Lario, President of the International Fund for Agricultural Development (IFAD) (Asharq Al-Awsat)
Money sent by migrants to their families is no longer simply a means of covering living expenses. In many low- and middle-income countries, these flows have become a financial safety net for households during crises, a source of savings and investment, and a channel whose effects extend to rural economies and local markets.
Remittances to low- and middle-income countries reached $728.6 billion in 2025, an increase of 94 percent since 2016, making them larger than foreign direct investment in these countries and more than four times the amount of global official development assistance in the same year, according to the latest report by the International Fund for Agricultural Development (IFAD).
But the scale of these flows does not necessarily mean that households can access them more easily. As sanctions and financial compliance requirements have tightened in some markets, remittance channels face a dual challenge: maintaining the integrity of the financial system on the one hand, while ensuring that legitimate funds continue to reach households at the lowest possible cost on the other.
Alvaro Lario, President of the International Fund for Agricultural Development, told Asharq Al-Awsat that, from the perspective of remittances and financial inclusion, the main challenge posed by US economic sanctions is maintaining safe, low-cost and transparent channels for legitimate family remittances, while complying with sanctions and requirements to combat money laundering and terrorist financing.
He added that access to regulated financial channels becomes increasingly important in fragile and conflict-affected countries, where many families depend on money sent by relatives living abroad.
Sanctions and De-risking
Lario explained that the impact of sanctions on remittance flows varies depending on the country, the nature of the sanctions and the financial channels being used. The concern, he noted, is not limited to sanctions themselves, but also extends to how financial institutions respond to regulatory, compliance and reputational risks.
He said that even in cases where personal remittances are permitted, financial institutions may impose stricter measures when processing transactions connected to certain countries. Restrictions on correspondent banking relationships may also make it difficult for money transfer companies to maintain banking services.
This broader phenomenon is known as de-risking. It can reduce the number of formal channels available and increase remittance costs and waiting times, making it more difficult for households to access their money.
Lario warned of another possible consequence: making formal channels excessively difficult, costly or unavailable could push some transactions into informal channels, reducing rather than strengthening transparency and consumer protection.
Remittances have become a vital source of household resilience in many countries affected by conflict and economic crises (IFAD).
A Safety Net During Conflict
The importance of these channels is particularly evident in the Middle East, where some countries are experiencing protracted conflicts and economic crises.
Lario said that in many countries affected by conflict and economic crises, remittances have become a vital source of household resilience. Family members living abroad are often among the first to provide support when employment opportunities, public services, social protection networks and local economies are disrupted.
The importance of remittances lies not only in the regularity of their flow, but also in their ability to respond quickly to changing circumstances. Migrants may increase the frequency or adjust the amount of their transfers according to their families' needs, making this money, according to Lario, a first line of defense against shocks.
The funds are primarily used to cover basic needs such as food, housing, healthcare and education. But they can also give families an opportunity to build savings, obtain insurance and credit, and invest.
In Syria, a World Bank analysis found that receiving international remittances was associated with a 12-percentage-point reduction in the extreme poverty rate and an 8-percentage-point reduction in the overall poverty rate, according to Lario. In Lebanon, remittances have likewise become an increasingly important economic safety valve for households amid the prolonged crisis.
But the ability to send money is not enough. Families need financial infrastructure capable of receiving and using those funds. This becomes more complicated during conflicts, when financial infrastructure is damaged, liquidity and cash become scarce, displacement increases, people's ability to move around declines, payment systems are disrupted, or financial service providers withdraw.
1.1 Billion People Connected to Remittances
IFAD figures reveal the scale of the social economy behind these flows. The report estimates that 220 million migrants and members of the diaspora support around 1.1 billion relatives, meaning that roughly one in every six people worldwide is connected to remittances.
Since 2016, flows have increased by 94 percent, outpacing population growth and migration from low- and middle-income countries.
This money does not go only to cities. Roughly one out of every three dollars migrants send home, or about $233 billion, reaches rural areas, which often suffer from limited formal employment opportunities, financial services and infrastructure.
IFAD estimates that households receiving remittances invest around $22 billion each year in rural agrifood systems, supporting agricultural production, rural enterprises and employment opportunities.
Lario said that the impact of this money extends beyond recipient households to local businesses, jobs and food systems. For millions of rural households, he added, remittances can represent the starting point for building savings, obtaining insurance and accessing suitable credit.
Remittances Enter the Digital Age
The shape of the remittance market is changing alongside the growth in its value. IFAD estimates that more than half of remittances now originate through a digital channel, a shift that has helped reduce sending costs and made the process faster and easier.
But the digital transition is not yet complete. Only 35 percent of the services measured in 2025 were fully digital on both the sending and receiving sides, while cash remains widely used across many remittance corridors.
The report argues that the next step is not simply digitization, but also the ability of households to use the financial system more broadly. It therefore calls on governments, regulators, financial institutions and development partners to reduce remittance costs, increase transparency, improve services in rural areas, strengthen financial and digital capabilities, and expand access to savings, insurance, credit and investment.
Asia Leads as Africa Accelerates
Asia and the Pacific remain the global center of the remittance economy, receiving $384.9 billion, or 53 percent of the total flows covered by the report over the past decade.
Latin America and the Caribbean recorded the fastest growth over the decade, with remittances rising 132 percent to $168.6 billion, while flows to Africa increased 86 percent to $124.2 billion.
These figures reflect significant differences in how heavily economies depend on money from their diasporas. In 23 countries, remittances account for more than 10 percent of GDP, while in nine countries their value exceeds total exports of goods and services.
For IFAD, maximizing the impact of these flows does not mean turning them into a substitute for public investment, social protection or climate finance. Rather, it means building a financial environment that allows households to use the money they receive more safely and efficiently, and to transform part of it from a tool for meeting urgent needs into a means of saving, investing and building resilience.
Sudan’s War Economy Sends Pound into Freefallhttps://english.aawsat.com/business/5320352-sudan%E2%80%99s-war-economy-sends-pound-freefall
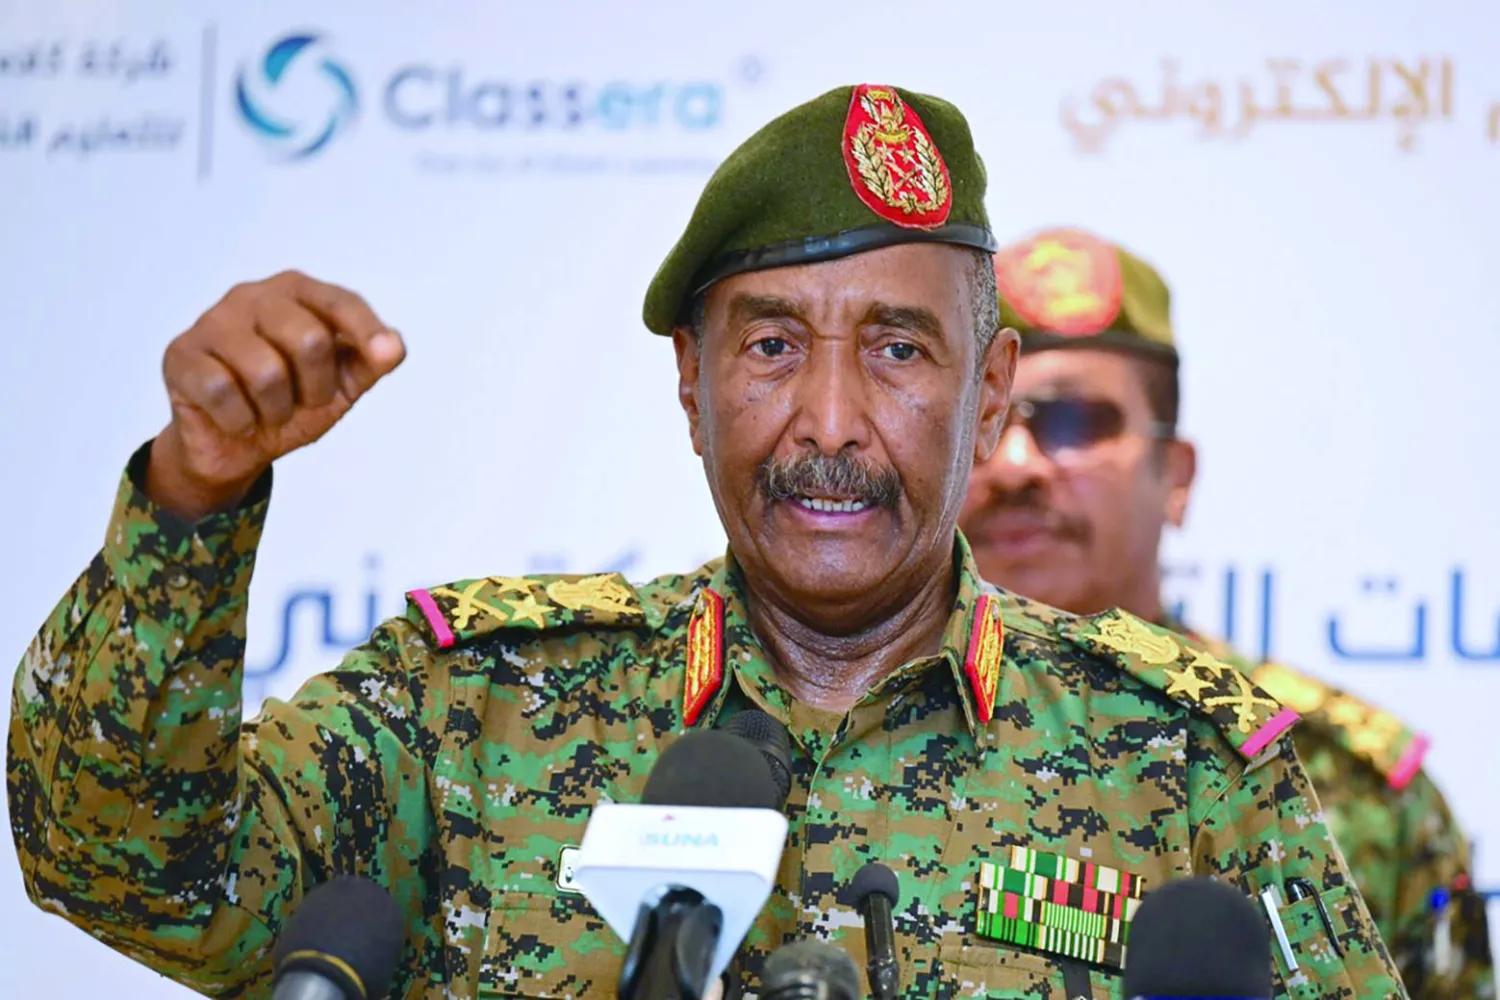
Army Commander Abdel Fattah al-Burhan stated that the high cost of living is 'part of the battle' and pledged to emerge victorious (AFP).
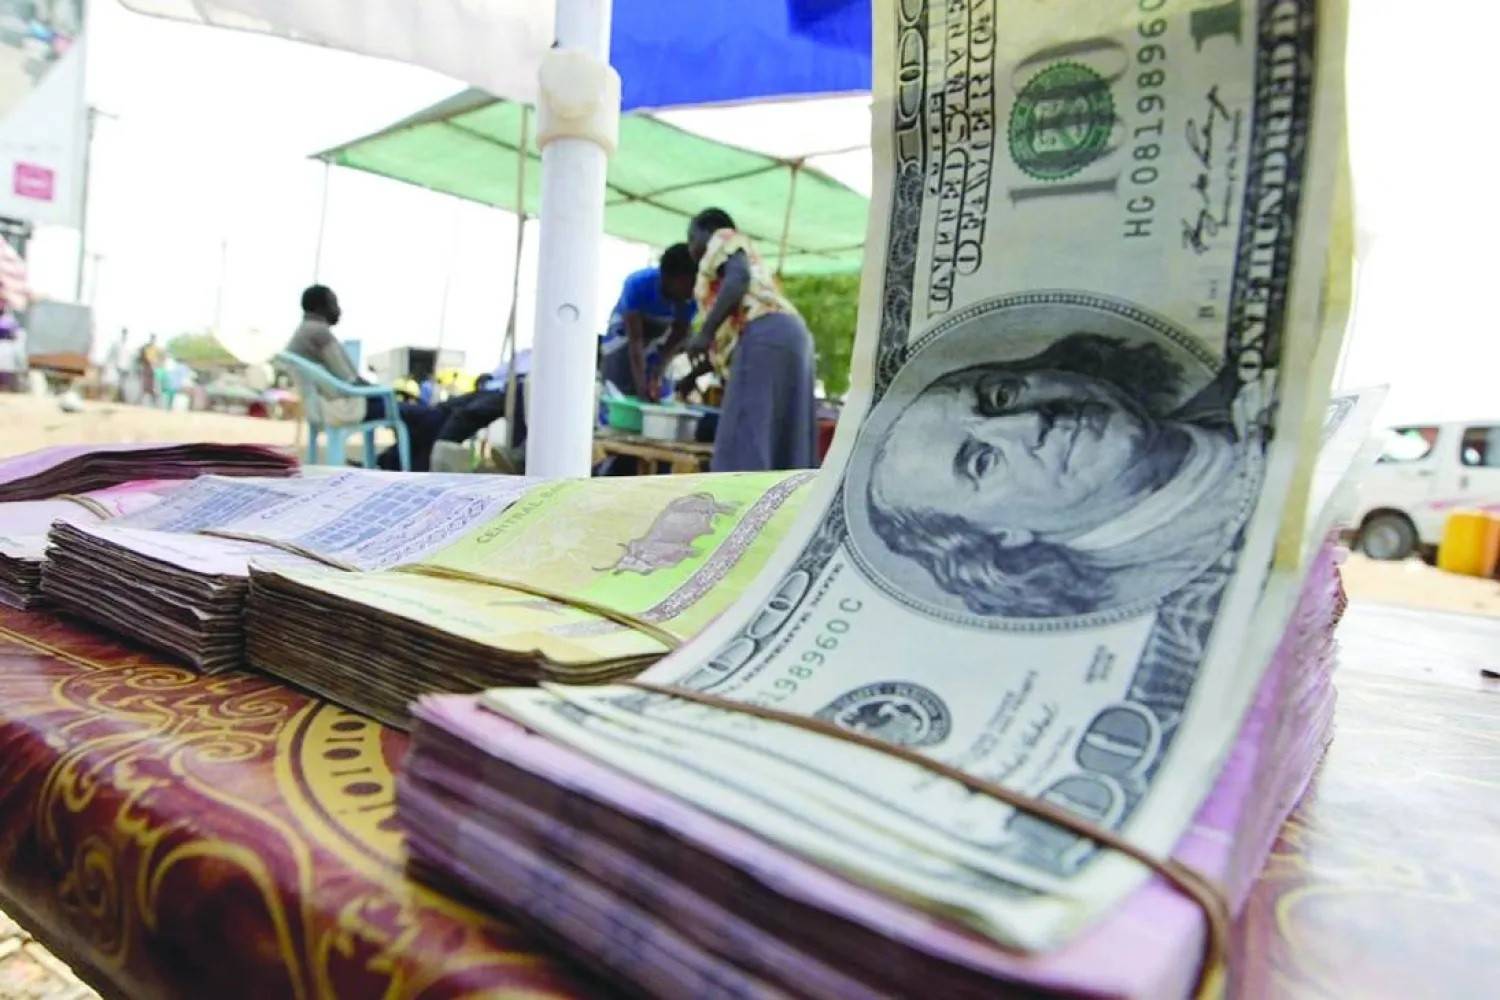
Sudan has entered a new phase of economic turmoil after its currency, the pound, fell sharply against foreign currencies, with the dollar trading above 9,000 pounds in some parallel-market transactions in recent days.
The pound later temporarily recovered some of its losses, but severe volatility disrupted markets, prompting some traders to suspend sales and close their shops.
Exchange-rate movements illustrate the scale of the deterioration. The dollar, which traded at about 4,400 pounds on the parallel market in June, surged to more than 9,000 pounds at the height of this month’s September turmoil.
The number of pounds needed to buy one dollar has nearly doubled in about three months.
Rates quoted by several banks remained far below those on the parallel market, reflecting a widening gap between the official banking rate and the price at which traders obtain foreign currency outside the banking system.
After a limited improvement on Friday, the dollar again rose above 8,000 pounds on Saturday amid a shortage of US currency in banks.
Sovereign Council Chairman and army chief General Abdel Fattah al-Burhan directly linked the economic crisis to the war.
“The battle has taken many forms,” Burhan said after Friday prayers in Khartoum’s Burri district. He described the economic crisis, rising prices and scarcity of resources as “part of this battle” and pledged that Sudan would emerge “victorious, just as we drove the rebellion out of Khartoum and other cities.”
Exchange-rate, market and gold-production figures suggest that the “economic battle” is more complicated than controlling currency speculators. It involves the wartime economy, shortages of foreign currency, declining production, foreign-trade imbalances and gold smuggling.
Prices surge
The pound’s depreciation is having a direct effect on people’s lives.
During a tour of markets in Khartoum and Wad Madani on Sept. 18, local broadcaster Radio Tamazuj reported that the price of a 50-kg sack of sugar had risen to 470,000 pounds from 380,000 pounds, an increase of about 24%.
A sack of flour climbed to 120,000 pounds from 80,000 pounds, an increase of about 50%.
The broadcaster said most of the shops visited during the tour were closed. Traders had stopped selling because prices were changing so rapidly that they could not determine how much it would cost to replace the goods they sold.
Closures spread to other cities. Local reports from Atbara in River Nile state said that a growing number of shops had closed and traders were refusing to sell. Reports from Duwaim said about three-quarters of shops had closed, citing local traders.
In Tamboul in Gezira state, activists circulated a local account describing the city’s market as almost at a standstill, with shops closed and goods scarce.
The account put the price of a 50-kg sack of sugar at 600,000 pounds, a sack of sorghum at 500,000 pounds, a 36-pound container of cooking oil at 400,000 pounds and a sack of flour at 150,000 pounds.
The prices could not be independently verified, nor could it be confirmed whether the closures affected the entire market.
The crisis is reflected in the experience of grocery store owner Ibrahim Idris, who said his capital was no longer sufficient to stock the range and quantities of goods he had previously sold.
Idris said the price of a 36-pound container of cooking oil had risen to nearly 350,000 pounds from about 170,000 pounds over the past month, more than doubling.
Customers were buying smaller quantities, he said, while increasing numbers were asking to purchase goods on credit.
Nahla Khalifa, a homemaker from Omdurman, previously told Asharq Al-Awsat that her family had often gone without meat, milk and vegetables, while obtaining medication for her husband, who has diabetes, had become increasingly difficult.
Osman al-Jundi, a supervisor of community kitchens, or takayas, in Khartoum, told Asharq Al-Awsat days before the sharp currency decline that falling donations, rising prices and the pound’s depreciation had forced several free kitchens to close.
Only two kitchens in his area were still operating daily, he said, even as the number of people in need continued to grow. They included displaced people from Kordofan, as well as children, women, older people and people with disabilities.
The Sudanese pound continues its slide to a record low against the dollar (Reuters)
Gold production declines
The sharpest contradiction emerges in Sudan’s gold sector.
According to data from the Sudanese Mineral Resources Company, recorded gold production exceeded 70.15 metric tons in 2025. That included about 58.38 tons from traditional mining, roughly 5.68 tons from mining-waste processing companies and about 5.96 tons from concession companies.
However, the amount of gold entering official export channels was far below recorded production.
Data attributed to the Central Bank of Sudan showed that about 14.7 tons of gold, worth nearly $1.54 billion, were exported in 2025. In a separate estimate, the finance minister said about 20 tons had entered official channels.
The difference cannot be treated entirely as smuggled gold because of existing stockpiles, domestic consumption and trade, as well as differences in how the data are calculated. It nevertheless reveals a substantial gap between recorded production and the amount appearing in official exports.
An official at the Sudanese Mineral Resources Company previously estimated that about 48% of the country’s 2024 gold production had been smuggled, depriving the banking system of a significant source of foreign currency.
Gold is also intertwined with the war. A study by the Chatham House think tank said both sides in the conflict had benefited from the gold economy and its production and trading networks, although through different methods and in different areas of influence.
The study linked gold-sector revenues to the warring parties’ ability to finance operations and obtain resources, weapons and supplies.
That does not mean all proceeds from official gold exports are used for military spending. The state also uses foreign currency to finance imports of fuel, wheat and other goods and necessities.
A further contradiction has emerged within the gold sector itself.
Twenty-three mining companies have threatened to begin gradually suspending production on Sept. 30 and halt it entirely on Oct. 1 in protest against the Central Bank of Sudan’s mechanism for purchasing gold.
The companies say they produce about 17% of the country’s gold and that the central bank’s purchase price does not cover rising fuel, transportation, wage and operating costs caused by the pound’s depreciation.
The distortions extend beyond the gold market.
While the dollar rose above 9,000 pounds in some transactions in government-controlled areas, it traded at about 4,600 pounds in cash in Nyala. Its price through transfers using the Bankak banking application reached about 6,500 pounds.
The cash price of the dollar in Nyala was, therefore, at roughly the same time, about half the rate recorded in some markets in government-controlled territory.
That does not mean the economy in areas controlled by the paramilitary Rapid Support Forces is stronger.
Experts and traders attribute much of the difference to the shortage of banknotes, or cash liquidity, in Darfur, as well as different trade routes and foreign-currency flows. Markets in western Sudan are also linked to Chad, Libya and South Sudan.
The difference within Nyala itself — 4,600 pounds in cash versus 6,500 pounds via bank transfer — illustrates the distortions created by the liquidity crisis.
Seeking solutions
As the pound’s decline accelerated, the National Committee for Economic Management, headed by Prime Minister Kamil Idris, formed a committee led by Finance Minister Gibril Ibrahim to address the exchange-rate crisis.
The announced measures include increasing agricultural, livestock and mining production; encouraging manufacturing and exports; reducing imports; regulating the gold trade and combating smuggling; requiring exporters to repatriate export proceeds; and confronting currency speculation and foreign-exchange trading outside official channels.
But the figures present those measures with a clear test.
The dollar has risen above 9,000 pounds despite previous interventions. Gold production has exceeded 70 tons, yet far smaller quantities have appeared in official exports. Companies producing 17% of the country’s gold are threatening to halt operations, while shops have closed because traders can no longer set stable prices for their goods.
The contradiction between Burhan’s pledge to prevail in the “economic battle” and the economic data is stark: Sudan produces more than 70 tons of gold annually but suffers from a shortage of foreign currency.
The dollar trades above 9,000 pounds in one market and at about 4,600 in another, while flour prices in some markets rose by 50% during the latest bout of volatility.
For Sudanese people, the question is therefore no longer merely when the dollar will fall. It is how much real value the pound retains — and how much food and medicine it will be able to buy the following day.
لم تشترك بعد
انشئ حساباً خاصاً بك لتحصل على أخبار مخصصة لك ولتتمتع بخاصية حفظ المقالات وتتلقى نشراتنا البريدية المتنوعة