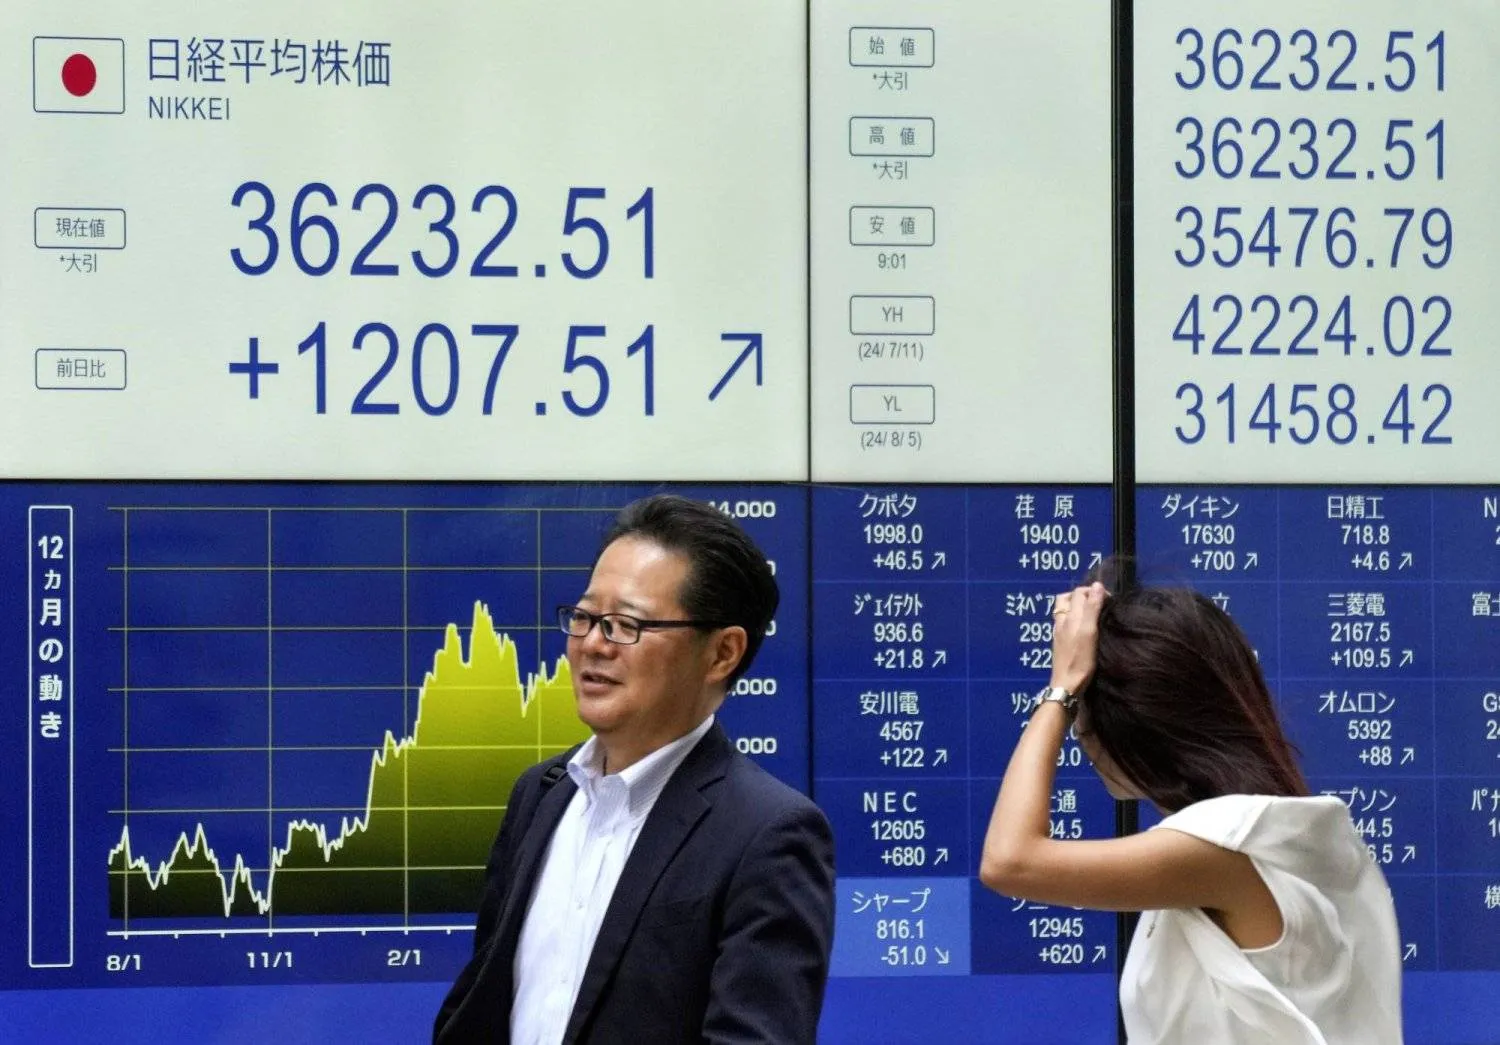
Japan Imposes New Regulations on Chip Supply-Chain Network

Pedestrians wak past an electronic board displaying the Nikkei Stock Average figure, in Tokyo, Japan (EPA)
TT

Japan Imposes New Regulations on Chip Supply-Chain Network

Pedestrians wak past an electronic board displaying the Nikkei Stock Average figure, in Tokyo, Japan (EPA)

Japan has decided to apply foreign trade regulations to chipmaking equipment as part of its efforts to secure stable supply chains, the Finance Ministry said Friday.

Foreign investors are now required to give prior notice when conducting direct investment in equipment tied to chipmaking, including when acquiring a 1% or bigger stake in a listed company or buying shares in an unlisted company, the ministry said in a statement, according to Bloomberg.

The move also aims to address the risk of technology leakage and keep commercial technologies from being used for military purposes, it said.

Other products added to the list of so-called “core business sectors” include advanced electronic components, machine tool components, marine engines, fiber optic cables and multifunctional machines, according to the ministry.

The targeted move will help the government enhance national security while its impact on companies is expected to be limited, a Finance Ministry official told Bloomberg.

The move comes as Japan tries to revive its own capacity to produce semiconductors as a pillar of its economic security strategy.

Japan has already earmarked some ¥4 trillion ($26.9 billion) over the last three years to recharge its semiconductor sectors and promote digitalization.

In the markets, Japan's Nikkei share average climbed nearly 3% on Friday and notched its best week in more than four years, as strong US retail sales data soothed fears of a recession in the world's largest economy and Japan's top trading partner.
The Nikkei closed 3.6% higher at 38,062.67, locking in its second-largest daily gain for the year, while the broader Topix finished up about 3% at 2,678.60.

The Nikkei logged its biggest weekly gain since April 2020, rising over 8%, buoyed by easing concerns about the state of the US economy, a pause in the yen's rapid appreciation and a pick-up in Japan's economic growth.

Wall Street's main indexes closed higher on Thursday after US retail sales increased 1% in July following a downwardly revised 0.2% drop in June.

The rally was broad-based, with 219 of the Nikkei's 225 constituents advancing against 5 decliners, while shares of many big names surged.

Nikkei heavyweight Fast Retailing jumped 6.2%, while chip-related share Tokyo Electron gained 4.8%, along with peer Advantest, adding 6.8%.

Meanwhile, the yen weakened against the dollar overnight in a boost to Japan's export-related shares like automaker Toyota Motor, which rose about 2%.

The Nikkei fell more than 12% on Aug. 5 in its biggest single-day decline since Black Monday amid a storm of concerns, including US recession fears sparked by a weak jobs report and a sharply stronger yen.

It has since clawed back those losses but remains well off an all-time peak of 42,426.77 touched in mid-July.

Among individual shares on Friday, electrical component maker Fujikura rallied over 11% to become the biggest percentage gainer.


Iraq Devalues Dinar as Citizens Bear the Cost of Fiscal Strain

 A currency exchanger counts bundles of Iraqi dinar banknotes while serving a customer at a roadside exchange shop in Baghdad. (AP)
A currency exchanger counts bundles of Iraqi dinar banknotes while serving a customer at a roadside exchange shop in Baghdad. (AP)
TT

Iraq Devalues Dinar as Citizens Bear the Cost of Fiscal Strain

 A currency exchanger counts bundles of Iraqi dinar banknotes while serving a customer at a roadside exchange shop in Baghdad. (AP)
A currency exchanger counts bundles of Iraqi dinar banknotes while serving a customer at a roadside exchange shop in Baghdad. (AP)

Iraqis woke on Wednesday to a sharp loss in their currency’s value after authorities devalued the dinar to 1,520 per dollar from 1,320, triggering widespread anger and forcing markets and shops in several provinces to close.

The dollar, meanwhile, climbed to around 1,900 dinars on the parallel market.

The devaluation hit households already under financial strain, quickly driving up prices for food and imported goods.

Citizens feared higher costs would spread to transportation and services, particularly amid reports that the government was considering raising regular gasoline prices to 850 dinars per liter from 450 dinars per liter.

The move cuts the dinar’s value against the dollar by about 13%, increasing the cost of buying foreign currency for importers and individuals in an economy heavily dependent on imports to meet domestic demand.

Lawmaker Ahmed al-Shammari called on parliament’s leadership to convene an emergency session and summon the finance minister and central bank governor to discuss the consequences of the exchange rate increase and what he described as “market disruption.”

The Central Bank of Iraq said it would continue taking measures that it said served the economy and citizens and safeguarded the financial system’s soundness and stability. Public and political criticism nevertheless intensified, amid fears of another wave of price increases and an erosion of incomes.

The government of then-Prime Minister Mustafa al-Kadhimi devalued the dinar by nearly 20% in late 2020, setting the rate at 1,450 per dollar after collapsing oil prices triggered a severe financial crisis.

The government of former Prime Minister Mohammed Shia al-Sudani later strengthened the currency to 1,320 per dollar, a decision experts and analysts described as “political and ill-considered.”

The government of current Prime Minister Ali al-Zaidi recently had to approve another devaluation under pressure from a crippling financial crisis. Iraq’s oil exports had been suspended for several months because of the US-Iranian war and the closure of the Strait of Hormuz.

Higher import costs, limited export gains

Economics professor Siham Youssef told Asharq Al-Awsat that devaluation would not deliver the same benefits in Iraq as in industrial economies. Iraq relies on oil to generate dollar earnings and heavily on imports to meet domestic demand.

A weaker currency “does not make exports more competitive as it does in industrial economies,” she said, because Iraq lacks a diversified export base that could benefit from the devaluation.

“The dollar becomes more expensive for importers, the cost of imported goods and production inputs rises, and some of that cost may be passed on to prices,” she added.

Converting dollar revenue into more dinars increases treasury receipts. But Youssef said that would only help resolve public finance problems if the additional funds were used to reduce the deficit and borrowing.

Making the economy absorb the cost of devaluation without addressing underlying fiscal imbalances could intensify inflationary pressures, she warned.

Reports of possible fuel price increases have compounded concerns over living costs. According to accounts circulating among lawmakers, regular gasoline could rise to 850 dinars per liter from 450, raising transport costs and adding pressure to goods and services prices.

Higher spending leaves a 43 trillion dinar deficit

The fiscal pressures extend beyond the exchange rate. The new draft budget sets expenditure at 217.239 trillion dinars ($142.9 billion) against revenue of 174.234 trillion dinars ($114.6 billion), leaving a deficit of 43.005 trillion dinars ($28.3 billion).

The draft assumes oil exports of 4 million barrels per day at $58 per barrel and an exchange rate of 1,500 dinars per dollar.

Youssef said the deficit’s decline from the 2023 budget reflected higher projected revenue, rather than spending restraint. Proposed expenditure rises 9.2%, while revenue increases 29.5%.

The government offsets a reduction in the assumed oil price to $58 from $70 by projecting higher exports of 4 million barrels per day. Oil revenue therefore remains dependent on prices, export volumes and the exchange rate, particularly amid regional turmoil and disruptions to Iraqi oil exports.

Budget needs oil well above $58 to break even

Youssef said the oil price needed to balance the budget was a key measure of the fragility of its assumptions.

According to the published tables, Iraq needs about $77.6 per barrel at an exchange rate of 1,500 dinars per dollar to cover all budget expenditure without a deficit. The required price rises to around $90.8 if revenue is calculated at 1,300 dinars per dollar.

The budget’s assumed oil price of $58 therefore falls well short of the level needed to balance public finances. Additional financing would still be required even if the draft’s production and export assumptions were met.

The gap “means that the budget, despite assuming an oil price of $58, still needs a much higher price to break even,” Youssef said.

Recurring commitments squeeze fiscal flexibility

Employee compensation, social welfare and debt servicing together account for about 54.4% of total spending, underscoring the weight of current expenditure.

Employee compensation totals 68.1 trillion dinars ($44.8 billion), social welfare 33 trillion dinars ($21.7 billion) and debt servicing 17 trillion dinars ($11.2 billion).

Youssef said those commitments limited the government’s ability to cut spending quickly when oil revenue fell. Rising debt servicing also reflected the growing cost of past borrowing.

Investment spending, meanwhile, falls 11.7% to 47.9 trillion dinars ($31.5 billion), raising questions about the budget’s capacity to support growth and diversify the economy.

Youssef said financing the 43 trillion dinar ($28.3 billion) deficit remained the central challenge. More domestic borrowing would raise future debt servicing costs at the expense of investment spending, she warned.

Oil dependence persists despite devaluation

Economist Ziad al-Hashimi said the devaluation and draft budget showed that the current crisis had not prompted a fundamental reconsideration of public spending.

In a post on X, he said the government had raised expenditure despite financial pressures and a lower assumed oil price of $58 per barrel. Operating expenditure remained high at 78% of the budget, leaving 22% for investment.

Hashimi pointed to continued expansion in government hiring and contract employment, rather than efforts to rein in the government workforce and operating expenditure. Those costs consume about 78% of the budget, leaving investment spending less able to support growth.

Moving the exchange rate to 1,520 dinars per dollar gives the treasury more dinars for its dollar revenue, “but out of citizens’ pockets,” he said. It does not address the underlying fiscal imbalance: the deficit still amounts to about 20% of total expenditure.

Oil revenue remains about 145 trillion dinars ($95.4 billion) out of total receipts of 174 trillion dinars ($114.5 billion), or roughly 83%, leaving public finances highly exposed to fluctuations in oil prices and exports.


Stocks Slide as Oil Climbs on Mideast Flareup

FILE PHOTO: A maze of crude oil pipes and valves is pictured during a tour by the Department of Energy at the Strategic Petroleum Reserve in Freeport, Texas, US June 9, 2016.  REUTERS/Richard Carson/File Photo
FILE PHOTO: A maze of crude oil pipes and valves is pictured during a tour by the Department of Energy at the Strategic Petroleum Reserve in Freeport, Texas, US June 9, 2016. REUTERS/Richard Carson/File Photo
TT

Stocks Slide as Oil Climbs on Mideast Flareup

FILE PHOTO: A maze of crude oil pipes and valves is pictured during a tour by the Department of Energy at the Strategic Petroleum Reserve in Freeport, Texas, US June 9, 2016.  REUTERS/Richard Carson/File Photo
FILE PHOTO: A maze of crude oil pipes and valves is pictured during a tour by the Department of Energy at the Strategic Petroleum Reserve in Freeport, Texas, US June 9, 2016. REUTERS/Richard Carson/File Photo

Oil prices rose Wednesday on fresh concerns about Middle East supplies following a warning that Iran appeared to be stepping up attacks in the Strait of Hormuz, weighing on stock markets.

Crude futures had steadied Tuesday, helping Wall Street to fresh highs, with a large amount of the support coming from a rush back into the AI trade that saw chip titan Nvidia push towards a $6-trillion market value.

But Wall Street stocks pulled back at the opening bell, with a rise in bond yields on US government bonds to fresh 24-year highs as investors worried about inflation and interest rates.

"Rising Treasury yields and oil prices are creating renewed pressure after stocks received some relief from both fronts to start the week," said analysts at Briefing.com.

"In Europe, where there is a lower representation of AI-related names, investors are taking a more cautious stance," noted Russ Mould, investment director at AJ Bell.

"Oil prices remain above $100 a barrel and the inflation risks are clear to see," he added.

Figures have shown Tehran increasing strikes on tankers in the crucial Strait of Hormuz.

UK Maritime Trade Operations on Tuesday said there had been nine attacks this month, representing half of the September total in the waterway and the Gulf combined.

However US Secretary of State Marco Rubio said Wednesday that Iran has "lost complete control" of the Strait of Hormuz.

"There's almost as much oil flowing out now as there was before this conflict began," he told reporters during a visit to Athens.

Chris Weston, head of research at broker Pepperstone, said "reports of increased flows across the (Mideast) region have offered some downside pressure on crude, but this has been offset by varying reports around the scale of attacks on vessels moving through the Strait".

"For now, the market remains highly sensitive to headlines and geopolitical risk," he added.

Indian stocks slipped and the rupee steadied Wednesday as the Indian central bank hiked interest rates for the first time in more than three years.

The euro fell heavily versus the dollar for a second time this week as worries about France's high debt levels spook bond markets.

Marine Le Pen, frontrunner in the race to be France's next president, said Tuesday she would implement 140 billion euros ($157 billion) in cost savings by 2032 if elected next year, warning that without change France was "heading towards default" on its debt.

The pledge "has helped ease bond yields" in France even if "pushing through that level of cuts... would be a hugely difficult task", said Susannah Streeter, chief investment strategist at Wealth Club.


Saudi Arabia Prepares New Pathways for Its Companies to Enter the Syrian Market

Syrian President Ahmed Al-Sharaa with businesspeople during the Saudi-Syrian Investment Forum in Damascus (SPA)
TT

Saudi Arabia Prepares New Pathways for Its Companies to Enter the Syrian Market

Syrian President Ahmed Al-Sharaa with businesspeople during the Saudi-Syrian Investment Forum in Damascus (SPA)

Asharq Al-Awsat has learned that the Saudi-Syrian Business Council is currently working on around three new pathways that are still being developed as part of an institutional framework aimed at facilitating the entry of Saudi companies into the Syrian market and paving the way for new sector-specific projects in the coming stages.

Saudi-Syrian economic relations have developed since last year, following the arrival in Damascus of a high-level Saudi delegation led by then Investment Minister Khalid Al-Falih. The delegation included more than 130 businesspeople and investors, reflecting the scale of official and economic interest in strengthening trade and investment ties between the two countries.

The visit saw the signing of more than 47 agreements and memorandums of understanding across 11 vital sectors, with total investments exceeding $6.4 billion. They covered real estate, infrastructure, telecommunications and information technology, industry, and other sectors.

Coordination with the “Syrian Sovereign Fund”

According to the information, a mechanism has been established to coordinate with the Syrian Investment Authority to form a joint team to study the development of land and sea logistics corridors. This would include facilitating direct access for exports and temporary admission procedures for equipment used to carry out projects.

In parallel, the Federation of Saudi Chambers has opened a direct channel with the Syrian sovereign fund to follow up on investment opportunities available to the Saudi private sector and support communication with relevant authorities in the Syrian market.

The council was established as Syria prepares for a new phase of reconstruction and development, creating opportunities for the Saudi private sector to participate in investment projects and various economic sectors, drawing on its financing and investment capabilities and its experience in project development.

Since its establishment, the council has begun preparing an action plan for 2025-2030 aimed at strengthening sustainable economic cooperation between Saudi Arabia and Syria, highlighting investment opportunities, supporting strategic partnerships, and facilitating trade and logistics procedures for Saudi companies' exports.

The plan focuses on enabling the Saudi private sector to benefit from reconstruction and development opportunities in Syria by supporting exports, simplifying procedures, and strengthening regulatory frameworks that provide a more favorable environment for investors. It focuses on sectors including infrastructure, trade and export development, real estate development, tourism, industry, and food security.

New Investments

In this context, Mohammed bin Abdullah Abu Nayyan, chairman of the Saudi-Syrian Business Council, said the council includes a number of senior Saudi officials and investors with international business activities, strengthening its ability to support trade and investment relations between the two countries and achieve its objectives.

The Saudi-Syrian Business Council delegation visited the Syrian capital, Damascus, last August, with the participation of 180 Saudi businesspeople. It held joint meetings and more than 15 meetings with government officials, in addition to eight sector-focused meetings and workshops addressing investment opportunities, challenges, and areas of cooperation.

During the visit, the delegation announced the “Sham View” project by Saudi real estate development and investment company Tharaa, with investments exceeding $1 billion. It also launched construction work on the Narcissus Damascus Hotel, owned by Saudi hotel and resort group Boudl.