EU, South American Trade Bloc Reach Giant Trade Deal

(L/R) Argentina's President Javier Milei, Uruguay's President Luis Lacalle Pou, European Commission President Ursula von der Leyen, Brazil's President Luiz Inacio Lula da Silva and Paraguay's President Santiago Pena pose for the family picture of the LXV Mercosur Summit in Montevideo on December 6, 2024. (Photo by Eitan ABRAMOVICH / AFP)
TT

EU, South American Trade Bloc Reach Giant Trade Deal

(L/R) Argentina's President Javier Milei, Uruguay's President Luis Lacalle Pou, European Commission President Ursula von der Leyen, Brazil's President Luiz Inacio Lula da Silva and Paraguay's President Santiago Pena pose for the family picture of the LXV Mercosur Summit in Montevideo on December 6, 2024. (Photo by Eitan ABRAMOVICH / AFP)

The European Union reached a blockbuster free trade agreement Friday with Brazil, Argentina and the three other South American nations in the Mercosur trade alliance, capping a quarter-century of on-off negotiations even as France vowed to derail the contentious accord.
Provided it is ratified, the accord would create one of the world's largest free trade zones, covering a market of 780 million people that represents nearly a quarter of global gross domestic product, The Associated Press reported.
The accord's proponents in Brussels say it would save businesses some $4.26 billion in duties each year, slashing red tape and removing tariffs on products like Italian wine, Argentine steak, Brazilian oranges and German Volkswagens.
Its critics in France, the Netherlands and other countries with big dairy and beef industries say the pact would subject local farmers to unfair competition and cause environmental damage.
From Uruguay, the host of the Mercosur summit, European Commission President Ursula von der Leyen hailed the deal as a “truly historic milestone" at a time when global protectionism is on the rise.
“I know that strong winds are blowing in the opposite direction, toward isolation and fragmentation, but this agreement is our clear response,” von der Leyen said, an apparent reference to US President-elect Donald Trump's vows to protect American workers and goods.
Under pressure from his country's powerful and vocal farming lobby, French President Emmanuel Macron said Friday the deal remained “unacceptable” as it stands and stressed that governments have not yet seen “the final outcome” of negotiations.
“The agreement has neither been signed nor ratified. This is not the end of the story,” Macron's office said, adding that France demands additional safeguards for farmers and commitments to sustainable development and health controls.
For France to block the deal, it would need the support of three or more other EU member states representing at least 35% of the bloc's population.
The French government, which has been rallying countries to oppose the pact, named Austria, Belgium, Italy, the Netherlands and Poland as other wary states that share French concerns about the deal.
To take effect, the pact must also be endorsed by the European Parliament.
In remarks aimed at her “fellow Europeans,” and perhaps in particular French skeptics, von der Leyen promised the accord would boost 60,000 businesses through lower tariffs, streamlined customs procedures and preferential access to raw materials otherwise supplied by China.
“This will create huge business opportunities,” von der Leyen said.
She then turned to address European farmers who fear that an influx of cheap food imports will jeopardize their livelihoods. South American countries do not have to adhere to the same standards for animal treatment and pesticide use.
“We have heard you, listened to your concerns, and we are acting on them,” von der Leyen said.
Outrage over environmental rules, rising costs and unregulated imports has unleashed massive farmers’ protests across the continent over the past year.
Leaders on both sides of the Atlantic who long have pushed for the deal praised the announcement Friday, welcoming the results as a boon for export industries.
It marks the first major trade agreement for Mercosur, which is comprised of Argentina, Brazil, Uruguay, Paraguay and, newly, Bolivia. The bloc had previously only managed to conclude free-trade deals with Egypt, Israel and Singapore.
“An important obstacle to the agreement has been overcome,” said Chancellor Olaf Scholz of Germany, where the nation's vaunted car industry is poised to profit.
From Spain, Prime Minister Pedro Sánchez called the agreement “an unprecedented economic bridge."
At the Mercosur summit in Uruguay’s capital of Montevideo, Brazil's President Luiz Inacio Lula da Silva praised “a modern and balanced text which recognizes Mercosur’s environmental credentials."
“We are securing new markets for our exports and strengthening investment flows,” he said.
The Brazilian Trade and Investment Promotion Agency said it expects the pact to boost the nation's Europe-bound exports by $7 billion.
Libertarian President Javier Milei of Argentina described the accord as aligning with his free market principles. Argentines are excited about selling more beef and agricultural products in the EU.
The deal is the product of 25 years of painstaking negotiations, dating back to a Mercosur summit in Rio de Janeiro in 1999. Talks collapsed over differences in economic priorities, regulatory standards and agricultural policies. The rise of protectionist tendencies also repeatedly upended hopes.
Momentum picked up in 2016, as former President Trump imposed harsh tariffs on Europe. At the same time, market-friendly governments came to power in South America's biggest economies, Brazil and Argentina, which had been closed for years.
In June 2019, negotiators announced a deal that included provisions for tariff reductions and commitments to environmental standards.
But it was never implemented. In Brazil, the region's economic powerhouse, right-wing former President Jair Bolsonaro in Brazil, presided over record levels of deforestation in the Amazon, prompting EU governments to demand tougher sustainability criteria. In Argentina, a new left-wing protectionist government opposed the deal.
But things picked up as the region's politics shifted again in 2023. Brazil's President Lula rode to power on pledges to rein in illegal logging, soothing concerns that the pact could accelerate deforestation. Argentina's Milei is working to open the nation's notoriously closed and crisis-stricken economy.
But if past EU trade agreements are any indication, ratification could take years.
"We celebrate it, but it's still far from reality,” Milei said of the accord.
In 2016, the EU and Canada signed a pact, known as the Comprehensive Economic and Trade Agreement, or CETA, but the approval process is still lumbering along.
Germany’s parliament only signed off on that pact two years ago, and the French Senate rejected it in March this year.
“Anyone with any memory is skeptical," said Brian Winter, a vice president of the New York-based Council of the Americas. “They have trotted out leaders and declared victory and celebrated, and yet there always seems to be a hitch.”


Saudi Arabia Expands Tourist E-Visa Eligibility to Four More Countries

The tourist visa allows visitors to attend events, perform Umrah, and visit exhibitions and conferences (SPA)
TT

Saudi Arabia Expands Tourist E-Visa Eligibility to Four More Countries

The tourist visa allows visitors to attend events, perform Umrah, and visit exhibitions and conferences (SPA)

Saudi Arabia has expanded its electronic tourist visa program by adding four countries to the list of eligible nationalities: Mexico, North Macedonia, Serbia, and Bosnia and Herzegovina.

The Ministry of Tourism said the move is part of ongoing efforts to facilitate travel to the Kingdom for visitors from around the world, allowing citizens of the newly added countries to apply electronically for tourist visit visas.

The tourist visa also permits holders to attend events, perform Umrah, visit exhibitions and conferences, and visit relatives and friends, in accordance with applicable regulations and instructions.


50-Year Contracts Open New Horizons for Real Estate Investment in Saudi Arabia

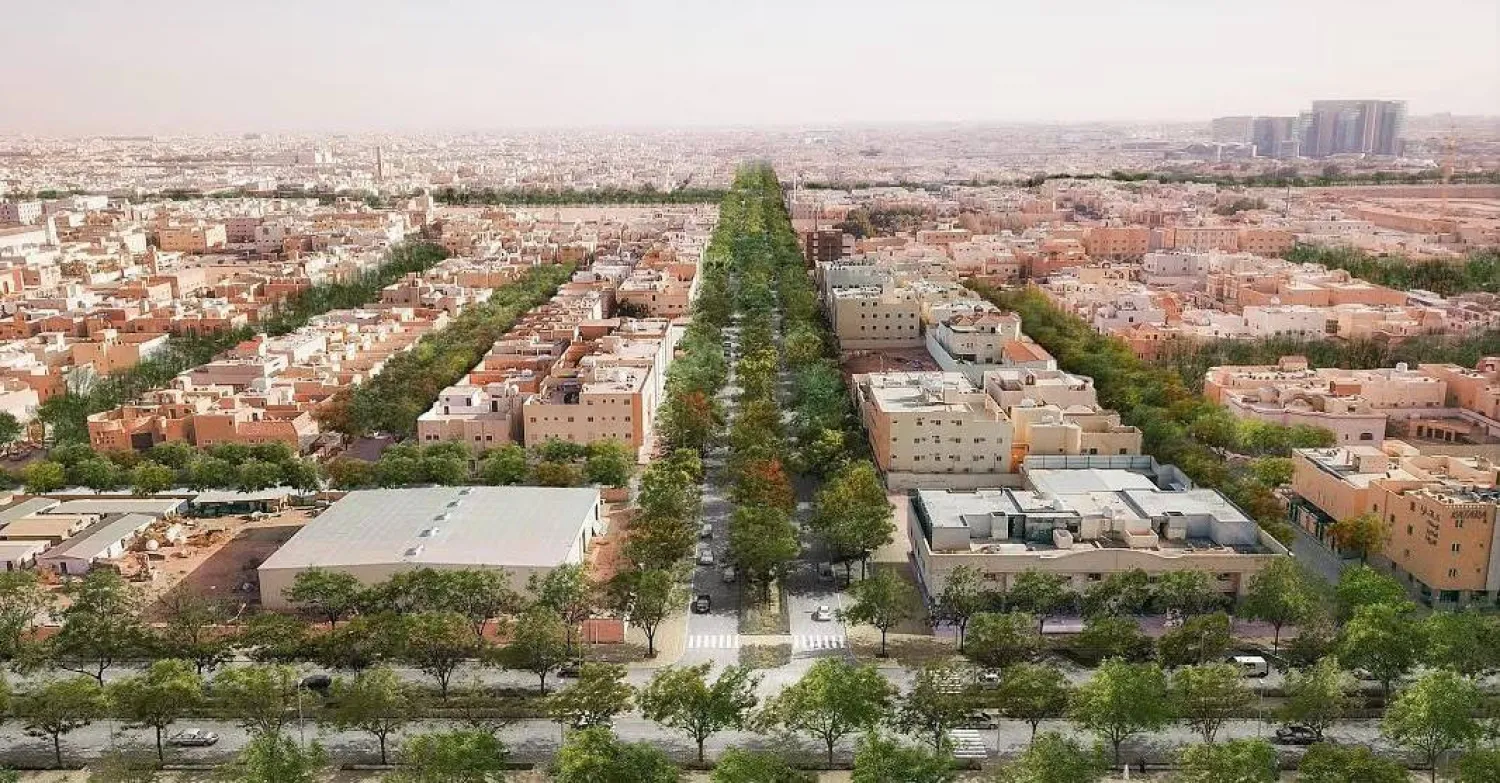
A neighborhood in the Saudi capital, Riyadh (SPA)
TT

50-Year Contracts Open New Horizons for Real Estate Investment in Saudi Arabia

A neighborhood in the Saudi capital, Riyadh (SPA)

Long-term real estate investment models are opening new opportunities for Saudi Arabia's private sector, as the Kingdom seeks to expand partnerships with investors to develop municipal assets and transform them into mixed-use projects.

The approach is expected to enhance the appeal of the real estate market, create investment opportunities spanning decades, and attract domestic and international capital to urban development. It also aims to improve land-use efficiency, maximize the economic value of municipal assets and increase housing supply.

Riyadh Region Municipality, the Ministry of Municipalities and Housing, and the National Center for Privatization & PPP (NCP) announced the launch of the expression of interest, prequalification and proposal submission phases for a joint land investment project in northern Riyadh.

The project involves developing a plot of municipal land under a 50-year partnership with the private sector, marking the municipality's first initiative under this joint investment model.

The private-sector partner will be responsible for designing, constructing, operating and maintaining all project facilities.

Located on Zaid bin Asim Street, the strategically positioned 30,015-square-meter site benefits from flexible urban planning regulations that allow for mixed-use development, including residential, commercial, office and recreational facilities.

The project aims to deliver high-quality developments that meet growing demand, serve local residents and community needs, and strengthen Riyadh's urban infrastructure.

Long-Term Investment Strategies

Offering investment opportunities through contracts extending up to 50 years represents a shift in how Saudi Arabia develops government-owned real estate assets.

The model gives private-sector investors a longer timeframe to develop projects and implement long-term investment strategies, overcoming some of the limitations associated with short- and medium-term contracts.

It also strengthens investors' ability to undertake financial and operational planning, allowing them to recover development costs and generate investment returns over a longer period.

This could make such opportunities more attractive to real estate companies and institutional investors.

The project forms part of Riyadh Region Municipality's strategy to improve the efficiency of municipal asset management, expand private-sector participation in urban development and attract high-value investments.

These efforts are intended to promote sustainable urban development, keep pace with the capital's rapid growth and advance Saudi Vision 2030 objectives, in line with the municipality's ambition to help create a prosperous, sustainable Riyadh with a higher quality of life.

Project Sustainability

Real estate expert Khaled al-Mobid said the launch of a 50-year investment project in Riyadh's Al-Narjis district represents an important step toward enabling the private sector to develop real estate assets and transform them into sustainable projects with substantial economic value.

Speaking to Asharq Al-Awsat, he explained that the extended investment period encourages developers to improve construction quality and services while enhancing the financial viability of projects.

He added that the model could help diversify real estate offerings and increase supply in one of the capital's most expensive neighborhoods.

Al-Mobid said the project's significance lies less in its immediate impact on property prices than in its potential to establish a replicable investment model.

Such a model, he noted, could gradually increase supply, strengthen competition and contribute to greater price stability across Riyadh's real estate market.

Diversifying Real Estate Supply

Real estate developer Ahmed Omar Basoudan said the importance of these contracts extends beyond simply making land available to investors.

They also create opportunities to develop integrated real estate assets combining residential, commercial, office and recreational uses, increasing the economic value of land and improving its utilization.

Speaking to Asharq Al-Awsat, Basoudan explained that bringing design, construction, operation and maintenance together under a single investment framework allows for more integrated developments.

It also creates a stronger link between construction quality, operational efficiency and long-term sustainability.

At the broader market level, he said, the model could help diversify real estate offerings, particularly in major cities experiencing rapid urban expansion and rising demand for residential, commercial and office space.

The participation of new developers and operators could also strengthen competition and improve the quality of projects and services.

Moreover, the approach could create integrated mixed-use urban destinations that meet residents' needs and support economic activity, rather than relying solely on conventional real estate development.


Replicating the Model


According to Basoudan, the success of this investment model will depend on how effectively contracts are structured, how risks are allocated between government entities and investors, and how clearly development, operation and maintenance obligations are defined.

Equally important, he said, is striking an appropriate balance between investment returns and the public interest.

Basoudan believes extending the model to other municipalities and regions could create an additional channel for attracting domestic and international investment.

It could also strengthen private-sector participation in urban development, in line with Saudi Vision 2030 objectives to diversify the economy and improve the efficiency of government asset management.


Gold Rallies as Dollar, Treasury Yields Soften after US Midterm Results

Gold chips displayed at a state-owned gold retail store in Surabaya, East Java (AFP)
TT

Gold Rallies as Dollar, Treasury Yields Soften after US Midterm Results

Gold chips displayed at a state-owned gold retail store in Surabaya, East Java (AFP)

Gold climbed to its highest level in over two weeks on Thursday as the fallout from the US midterm election results rippled through the global financial and oil markets.

Spot gold rose 1.6% to $4,124.89 per ounce by 0752 GMT. It touched $4,146.63 per ounce, its highest level since October 20, earlier in ‌the session.

Bullion ‌climbed about 3.4% on Wednesday, its biggest ‌daily gain ⁠since August 19.

US ⁠gold futures for December delivery climbed 1.5% to $4,135.40, Reuters said.

A weaker dollar and lower Treasury yields have helped gold recover above the key $4,000 level, though holding above that threshold remains crucial for the recovery outlook, said Linh Tran, market analyst at XS.com.

"If investment flows and yield movements continue to provide support, gold could stabilize ⁠above $4,000, also opening up an opportunity for a ‌recovery toward $4,200, followed by $4,400."

Oil prices ‌were slightly higher after earlier falling for a fourth day on ‌expectations that the losses US President Donald Trump's Republican Party ‌suffered in congressional elections this week may reduce the risk of further escalation of the US-Israeli war with Iran.

Lower energy prices ease inflationary pressures, reducing expectations that the central bank will keep interest rates higher ‌for longer, supporting the appeal of non-yielding bullion.

The dollar slid to its lowest in more ⁠than a ⁠month, and 10-year US Treasury yield fell to its lowest since September 10.

A weaker dollar makes greenback-priced bullion more affordable for holders of other currencies.

Market participants now await the US non-farm payrolls report on Friday to further gauge the Federal Reserve's monetary policy outlook.

Meanwhile, Citi has a 0-3 month price target of $4,500 per ounce for gold, the brokerage said on Wednesday, as it sees substantial upside potential if the Strait of Hormuz reopens and the Yemen/Saudi conflict de-escalates.

Among other metals, spot silver rose 0.8% to $52.63 per ounce, platinum gained 1.2% to $1,514.20 and palladium climbed 2.2% to $1,026.83.