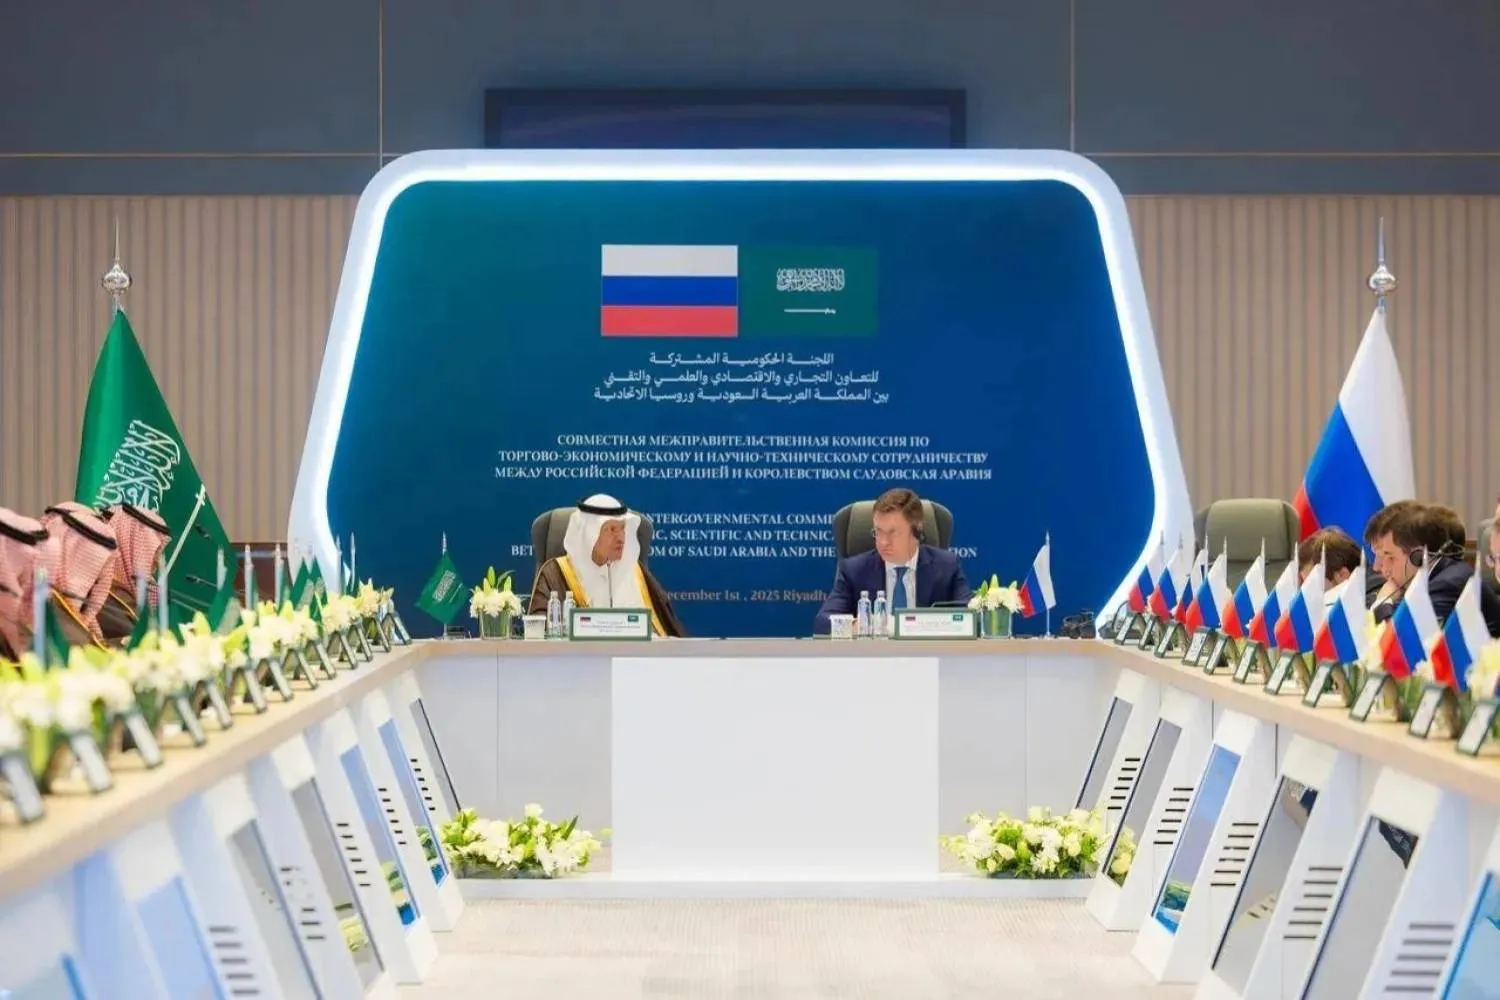
Riyadh, Moscow Advance Strategic Partnership Beyond Oil to Steady Markets

Saudi Energy Minister Prince Abdulaziz bin Salman and Russian Deputy Prime Minister Alexander Novak lead Joint Ministerial Committee session (X)
TT

Riyadh, Moscow Advance Strategic Partnership Beyond Oil to Steady Markets

Saudi Energy Minister Prince Abdulaziz bin Salman and Russian Deputy Prime Minister Alexander Novak lead Joint Ministerial Committee session (X)

The Saudi-Russian Investment and Business Forum 2025 concluded in Riyadh, closing a packed day of high level strategic dialogue aimed at anchoring a bilateral partnership that extends well beyond oil coordination.

The forum was held on the sidelines of the 9th Russian-Saudi Joint Committee and underscored the two countries’ shared determination to deepen economic and investment cooperation, driven by a sharp rise in bilateral trade.

Saudi Energy Minister Prince Abdulaziz bin Salman, who heads the Saudi side of the joint committee, and Russian Deputy Prime Minister Alexander Novak, who leads the Russian side, opened the forum in Riyadh.

Saudi Foreign Minister Prince Faisal bin Farhan attended.

Senior officials, experts and investors from both countries took part with the aim of strengthening Saudi Russian economic cooperation.

During the forum, organized by the energy and investment ministries, Prince Abdulaziz described the new mechanism adopted by the OPEC+ alliance to assess the maximum production capacity of member states as a turning point.

He said it was fair and transparent and would ultimately help stabilize markets, noting that it rewards those who invest in production.

Prince Abdulaziz and Novak also co-chaired the meeting of the joint ministerial committee, which reviewed agenda items focused on expanding cooperation in key sectors that include energy, trade, economy, investment, space, industry, mining, health, education, media, culture, sports, tourism, transport, housing and agriculture.

Both sides expressed appreciation for the continued advances in cooperation across all areas of mutual interest and welcomed the desire of both countries to strengthen their partnership in ways that support economic development.

They pointed in particular to the success of the Saudi-Russian Business Forum and the Saudi-Russian Business Council meeting held alongside the committee’s work.

Commenting on the meeting, Hassan Al-Huwaizi, chairman of the Federation of Saudi Chambers, said economic relations between the two countries are a key pillar supporting stability and growth in global energy markets.

He added that the strategic partnership has expanded significantly in recent years to include vital sectors such as mining, industry, agriculture and advanced technologies, reflecting the complementarity of their economic strengths.

Al-Huwaizi highlighted the notable rise in cooperation, saying bilateral trade has exceeded 3.8 billion dollars, an increase of 60 percent, which he said demonstrates growing private sector confidence in both countries.

From energy to economic diversification

Fadel bin Saad Al-Buainain, a member of Saudi Arabia’s Shura Council, said holding the forum is one of the tools that deepen bilateral relations and the economic partnership. He said it aims to strengthen the partnership and address challenges that may hinder progress toward its targets.

Al-Buainain stressed the importance of continued coordination between Saudi Arabia and Russia in the oil sector and of reinforcing the role of OPEC+, which he said has had a positive impact on stabilizing energy markets and shielding them from sharp fluctuations.

He added that systematic work is under way to expand the economic partnership, noting significant potential that is confirmed by tangible results such as the mutual visa waiver agreement and the launch of direct flights.

The forum’s outcomes further reflected Novak’s recent comments to Asharq Al Awsat, in which he said the OPEC+ partnership with Saudi Arabia extends beyond the oil market and represents a reliable platform for regional and international cooperation that ensures long term global market stability.

He added that bilateral cooperation includes major investment projects that go beyond energy.

Memorandums of understanding and agreements

During the forum, the Saudi energy minister and Novak signed a memorandum of understanding on cooperation in climate change and low emission development between the Saudi Ministry of Energy and Russia’s Ministry of Economic Development.

The MoU sets a broad framework for cooperation on climate issues and on supporting the objectives of the United Nations Framework Convention on Climate Change and the Paris Agreement.

It covers technologies and solutions related to mitigation, including shared opportunities to reduce, limit or remove greenhouse gas emissions and to improve energy efficiency.

On the sidelines of the event, the two sides signed a mutual visa exemption agreement for their citizens. It was signed by Prince Faisal bin Farhan for Saudi Arabia and by Novak for Russia.

Prince Abdulaziz also witnessed the signing of an agreement between Saudi Arabia’s King Abdulaziz Foundation for Research and Archives and Russia’s Federal Archival Agency to cooperate in their respective areas of work, including information exchange, conferences, forums, exhibitions, publications and expertise.

In a related development, Anton Berlin, vice president and head of sales at Russia’s Norilsk Nickel, the world’s largest producer of palladium and nickel, said the company is considering participating in mining projects in Saudi Arabia as well as in other countries, according to Russia’s Novosti agency.

He said the company is reviewing potential projects due to the presence of four industrial clusters in the kingdom.

Berlin said these clusters offer preferential tax treatment and have the needed infrastructure, including energy, gas, water supply, wastewater treatment and fueling stations. He said all an investor needs is to construct the production facilities.


CEER to Reveal First Flagship Vehicles in Saudi Arabia on Sept. 21

A glimpse of the car's design that CEER aims to launch later this September (Asharq Al-Awsat)
TT

CEER to Reveal First Flagship Vehicles in Saudi Arabia on Sept. 21

A glimpse of the car's design that CEER aims to launch later this September (Asharq Al-Awsat)

CEER, Saudi Arabia's first automotive company and Original Equipment Manufacturer (OEM), has announced the reveal date of the world premiere of its first flagship vehicles, an electric sedan and SUV, on September 21.

Friday’s announcement reflects the Kingdom’s strategic direction toward developing an advanced industrial sector aligned with the objectives of Saudi Vision 2030 and strengthening Saudi Arabia’s position on the global automotive industry map.

“At the beginning of this year, we said that 2026 is the year of CEER. I am happy to announce that we’ve set the date for the reveal of our first flagship vehicles,” said CEO of CEER James DeLuca.

“The world is about to witness a historic moment, the result of an incredible journey from initial design and intensive engineering to the buildup of one of the most advanced manufacturing facilities in the world, in record time.”

CEER was created as a joint venture between the Public Investment Fund and Foxconn. It is the only company in Saudi Arabia to design, engineer, source, validate, manufacture, and soon sell and service a portfolio of aspirational vehicles.

CEER is positioned to be a key enabler of Saudi Arabia's industrial transformation (Asharq Al-Awsat)

Since its inception in 2022, CEER has been focused on building a diverse mix of Saudi talent and global experts that had grown from 20 employees to 2,300; securing key partnerships with renowned international partners including BMW, Hyundai Transys, Rimac, Siemens, Sabelt, Isoclima, ANDRITZ Schuler, Dürr, XYG, Lear, Benteler, Fangxin, Shin Young, JVIS, as well as leading local companies including Zamil Group, Abdul Latiff Jameel Group and APICO (Balubaid Group) that are driving the target of reaching 45% local content by 2034; building one of the most advanced manufacturing complexes in the world; and designing, engineering and testing vehicles that are tailor-made to the specific requirements of Saudi Arabia and the region.

CEER is positioned to be a key enabler of Saudi Arabia's industrial transformation, creating lasting economic impact and supporting the Kingdom's diversification ambitions under Vision 2030.

CEER is projected to contribute $8 billion (around SAR30 billion) to Saudi Arabia’s GDP, $21 billion (around SAR80 billion) to trade balance improvement, and create approximately 30,000 direct and indirect jobs, with 80% of direct jobs held by Saudis. CEER supports the Saudi Green Initiative target of Net-Zero emissions in Saudi Arabia by 2060.


Oil Falls but on Track for 8% Weekly Gain on Supply Concerns; US Diesel Hits Record High

WHITING, INDIANA - SEPTEMBER 08: An aerial view shows the sprawling BP refinery on September 08, 2026 in Whiting, Indiana. (Photo by SCOTT OLSON / GETTY IMAGES NORTH AMERICA / Getty Images via AFP)
TT

Oil Falls but on Track for 8% Weekly Gain on Supply Concerns; US Diesel Hits Record High

WHITING, INDIANA - SEPTEMBER 08: An aerial view shows the sprawling BP refinery on September 08, 2026 in Whiting, Indiana. (Photo by SCOTT OLSON / GETTY IMAGES NORTH AMERICA / Getty Images via AFP)

Oil prices fell on Friday but remained on course for a weekly gain of more than 8% while US diesel prices hit a record high as attacks along Middle East shipping routes stoked concerns about prolonged supply disruptions.

Brent crude futures were down $3.45, or 3.21%, to $104.18 a barrel at 1132 GMT.

US West Texas Intermediate crude fell $2.96, or 2.89%, to $99.52 a barrel. Both benchmarks hit their highest levels since mid-May earlier in the session.

The benchmarks reversed early gains after the Financial Times reported that foreign ministers in the Middle East are trying to work out a temporary deal with Iran to manage shipping through the Strait of Hormuz.

Brent and WTI rose more than 6% on Thursday after an escalation in shipping attacks in the region.

"Some headlines of possible new talks in the Middle East are weighing moderately on oil prices today," said UBS energy analyst Giovanni Staunovo. "I keep seeing near-term risks to the upside for oil prices, but we should expect ongoing high price volatility too."

In a further potentially significant development for Riyadh, satellite imagery showed smoke on Thursday in the vicinity of Saudi Arabia's East-West Pipeline, which has become a vital means for the kingdom to divert its crude exports away from Hormuz.

Saudi Arabia's crude supply fell by 2.3 million barrels per day on the month to 6 million bpd in August, the lowest level in more than three decades, the International Energy Agency said on Friday, citing attacks on Saudi energy facilities.

Adding to concerns over regional oil flows, Yemen's Iran-aligned Houthis on Friday reached the island of Perim in the Bab el-Mandeb Strait, four Yemeni government sources told Reuters, potentially tightening their grip on one of the world's vital shipping routes.

Iran said it had attacked 10 ships near the Strait of Hormuz on Wednesday, after the US hit five Iranian oil tankers. Iran's Islamic Revolutionary Guard Corps said it would escalate its response to any further attacks.

Vessel transits at the Strait of Hormuz fell to seven on Thursday from 11 the previous day, preliminary ship-tracking data showed on Friday.

The strait handled about 125 commodity vessels and one-fifth of global daily oil and liquefied natural gas supplies before the Iran war began in late February.

Meanwhile, two European Central Bank policymakers opened the door on Friday to further interest rate increases if a war-fuelled rise in energy prices continues and pushes up other prices in the euro zone.

SUPPLY DISRUPTIONS LIFT FUEL PRICES

Oil supply disruptions due to the Iran war, along with Ukrainian attacks on Russia's refineries, pushed the US national average diesel price past $6 a gallon for the first time on Thursday, according to price tracker GasBuddy.

"Refined products, particularly diesel, are feeling a one-two punch right now," said Tim Waterer, chief market analyst at KCM Trade.

"As long as both the Gulf shipping constraints and Russian refining outages remain in play, diesel and other refined products are likely to show a higher upside tendency than the broader crude market," he added.

Commerzbank raised its year-end Brent crude forecast to $85 a barrel from $75, while increasing its diesel forecast to $1,200 a ton from $950 and its jet fuel forecast to $1,230 a ton from $980.


Gold Gains on Softer Oil; US Inflation Data in Focus

A view of smelted gold bars at a smelting facility in Accra, Ghana, August 22, 2024. REUTERS/Francis Kokoroko/
TT

Gold Gains on Softer Oil; US Inflation Data in Focus

A view of smelted gold bars at a smelting facility in Accra, Ghana, August 22, 2024. REUTERS/Francis Kokoroko/

Gold prices rose on Friday, but were headed for a weekly loss, as oil slipped from multi-month highs and assuaged some inflationary concerns, as investors awaited key US economic data for clues on the Federal Reserve's monetary policy path.

Spot gold rose 0.6% to $4,339.46 per ounce by 1105 GMT. It was down nearly 3% for the week so far.

Prices fell on Thursday after the US Producer Price Index data showed prices increased in line with expectations in August amid a rebound in the cost of energy products.

US gold futures dropped 0.6% to $4,381.30.

The precious metal is benefiting from "softer oil prices on hopes a Monday meeting between GCC ministers and Iran can yield some results regarding the passage of oil through the Strait," said Ole Hansen, head of commodity strategy at Saxo Bank. "In addition, buyers once again emerged ahead of a key support area around $4,300," said Hansen.

Oil prices were set to end the week above $100 a barrel.

Higher oil prices stoke inflation fears and bolster expectations of the Fed raising interest rates. While gold is typically seen as an inflation hedge, higher interest rates diminish the appeal of non-yielding bullion.

Traders are now pricing in a 67% chance of a rate hike at the central bank's policy meeting next week, up from 62% before the data, according to the CME FedWatch Tool. The US consumer price inflation report is due at 1230 GMT.

Elsewhere, gold demand in India was subdued this week as volatile prices discouraged buyers, while investment demand remained strong in top consumer China.

Among other metals, spot silver rose 0.4% to $63.80 per ounce, but was down 3% for the week.

Platinum climbed 0.9% to $1,792.07 and palladium gained 2.4% to $1,312.90. However, both metals were on track for a weekly loss.