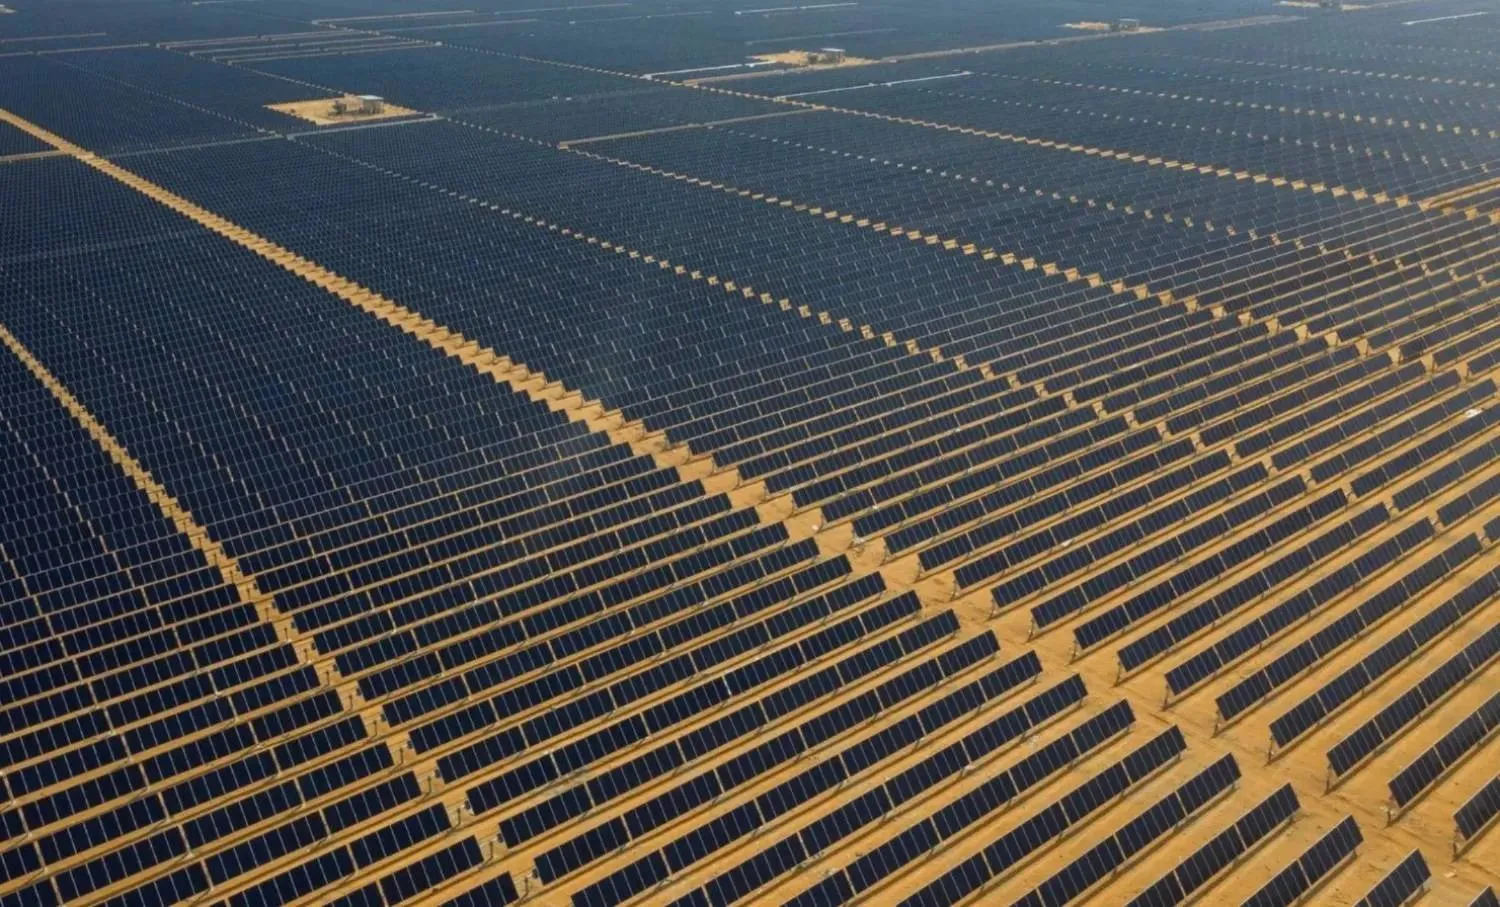
Arab Gulf Readies Infrastructure to Attract Long-Term Capital

A solar power project in northern Saudi Arabia. (SPA)
TT

Arab Gulf Readies Infrastructure to Attract Long-Term Capital

A solar power project in northern Saudi Arabia. (SPA)

Saudi Arabia and other Gulf countries are reshaping how they finance the next wave of infrastructure, moving beyond government spending to tap private and institutional capital for projects spanning energy, water, and the digital economy.

The shift marks a broader change in the Gulf’s investment model, as governments, development banks, sovereign investors, and private capital increasingly share the cost of turning large-scale projects into long-term investable assets.

What is changing in the Gulf is not simply the scale of infrastructure spending. The financing model itself is being reshaped.

As projects expand across energy, water, transport and the digital economy, government funding alone is no longer enough to meet rising investment needs. Pension funds, insurers and asset managers, meanwhile, control vast pools of long-term capital that are well suited to infrastructure assets capable of generating steady cash flows over many years.

The region is therefore moving toward financing structures designed to share risks more effectively, strengthen project creditworthiness and turn government-backed investments into opportunities that can draw in private and institutional capital.

Speaking to Asharq Al-Awsat, Saud Alsayyari, Asian Infrastructure Investment Bank (AIIB) Senior Investment Officer for the Middle East and North Africa, said the “fundamentals are strong” in Saudi Arabia and across the Gulf.

Population growth, urbanization and economic transformation programs are creating a broad pipeline of opportunities in renewable energy, digital infrastructure, water and healthcare, he explained.

The bigger challenge is no longer finding opportunities. It is structuring the risks and mobilizing enough capital to deliver them, he stressed.

Multilateral development institutions can play a central role by making projects more bankable, reducing risks for investors and catalyzing capital flows far beyond the size of their own direct commitments, he added.

Renewable energy and digital infrastructure lead opportunities

Alsayyari noted that the strongest investment opportunities over the next five years are likely to emerge where economic growth meets climate and sustainability goals.

Large-scale renewable energy projects, backed by storage technologies, will be a key pillar of the region’s energy transition, he went on to say.

He pointed to the financing of Oman’s 500-megawatt Ibri II solar power plant as an example.

Technology-enabled infrastructure will also play an increasingly important role.

From nationwide fiber-optic networks to smart logistics, such infrastructure “multiplies the value of every other asset class,” Alsayyari said.

Social infrastructure, particularly healthcare and education, is also expected to expand alongside population growth and urbanization.

“Disciplined structuring and strong environmental and social standards are what turn opportunity into sustainable, long-term value,” Alsayyari remarked.

Development banks can turn plans into bankable projects

Alsayyari said multilateral development banks can help transform government infrastructure plans into projects that lenders and investors are willing to finance. Their role includes sharing risks and providing the technical expertise needed to make projects viable.

He cited recent financing with the Saudi Water Authority, structured with the National Infrastructure Fund and commercial lenders to modernize major desalination facilities.

Projects of that scale become investable when a multilateral development institution can absorb risks that commercial lenders are unwilling to take, he added.

Such institutions can also carry out environmental and social due diligence and provide the technical expertise needed to structure deals in line with international standards.

“That is the model: multilateral development institutions turn ambition into bankable projects through disciplined preparation, blended finance and credit enhancement,” he stressed.

AIIB’s involvement also “reassures the market, reduces perceived risk and catalyzes private capital far beyond the size of our direct commitment,” he said.

The key issue is who carries the risk

For private investors, the problem is not risk itself, Alsayyari said. It is how that risk is distributed.

Infrastructure risk cannot be eliminated, but it can be allocated more effectively among the parties involved, he remarked.

Problems arise when investors are asked to shoulder risks they cannot easily price, such as regulatory uncertainty, early-stage construction risk or revenue models without a clear track record.

“Our role as a multilateral development bank is to correct that risk allocation,” Alsayyari said.

AIIB does this through non-sovereign financing that reduces pressure on public budgets, as well as guarantees and first-loss structures that can make commercial investment tranches more attractive to institutional investors.

Those tools can also increase confidence in how projects will be delivered and operated, he explained.

Clear visibility over future projects is equally important.

Alsayyari said the investment program AIIB is developing with Saudi Arabia gives investors a clearer view of a structured pipeline of opportunities rather than leaving them to assess isolated deals one by one.
Saud Alsayyari, Asian Infrastructure Investment Bank (AIIB) Senior Investment Officer for the Middle East and North Africa. (AIIB)

Four conditions could unlock institutional capital

Alsayyari said pension funds and insurers hold enormous amounts of long-term capital, yet infrastructure still accounts for only a limited share of their portfolios. That is despite a natural fit between the two.

Infrastructure assets can offer predictable, inflation-linked cash flows, making them well-suited to the long-term liabilities of institutional investors, he added.

Alsayyari identified four conditions needed to attract more of that capital: stable legal and regulatory frameworks, including clear public-private partnership rules; standardized project documents, procurement processes and structures; credit-enhancement tools; and reliable environmental, social and governance performance.

“Many global investors are subject to net-zero commitments, so they are looking for assets aligned with the goals of the Paris Agreement,” he noted. “When those conditions are in place, Gulf infrastructure can become a core asset class for institutional investors, and the capital will follow.”

Regional funds can multiply investment

Alsayyari described regional funds as one of the Gulf’s most effective tools for mobilizing private capital for infrastructure.

A direct loan finances one project. A well-structured investment platform can finance an entire portfolio, spread risk and build a broader investment ecosystem around it, he said.

He pointed to AIIB commitments to Gulf infrastructure funds, including Rakiza and Aberdeen Standard Investcorp Infrastructure Partners.

The funds target sustainable core infrastructure in healthcare, education, water, mobility and digital networks, with backing from investors including Saudi Arabia’s Public Investment Fund and the Oman Investment Authority.

AIIB’s participation adds more than capital, Alsayyari said.

Projects financed through the funds are assessed against the bank’s standards, ineligible activities are excluded and governance requirements are written into contracts.

The combination of “scale, discipline and local expertise” is crucial to steering institutional capital toward the region’s infrastructure needs, he said.

Gulf states look beyond new construction

Alsayyari said Gulf countries have made significant progress in building an infrastructure system that balances economic growth, environmental goals and long-term financing needs.

Sustainability has become embedded in national strategies, from net-zero commitments to renewable energy targets, he stated. One of the most striking developments, however, is the growing focus on upgrading existing assets rather than simply building new ones.

Alsayyari cited the modernization of desalination plants in Saudi Arabia.

Switching from thermal desalination to reverse osmosis will reduce energy consumption and emissions while increasing production capacity and extending asset life, he said.

“Growth and environmental performance are advancing together,” he told Asharq Al-Awsat.

The region’s financing system is also evolving quickly, with more structures combining multilateral, national and commercial institutions.

Alsayyari said the partnership with the National Infrastructure Fund offered a model that could be replicated elsewhere.

Every AIIB-approved financing aligns with the goals of the Paris Agreement, he said. “The direction of the region is clear, and we are proud to support that path.”

Energy, water and green hydrogen seen as the next growth areas

Over the next decade, Saudi Arabia and other Gulf states are likely to stand out in several infrastructure sectors, Alsayyari said.

Renewable energy and storage systems are expected to lead, alongside the emerging green hydrogen economy, technology-enabled infrastructure and climate-resilient water systems.

The region already has advanced investments in connectivity, data center capacity and digital infrastructure, he noted.

Water security will remain a strategic priority because of the region’s geography and its future needs.

The bigger transformation may be in how projects are financed

Alsayyari said the most important infrastructure change over the next decade may not be what the Gulf builds, but how it pays for it.

The region is gradually moving away from models driven mainly by government funding toward more complex partnerships bringing together governments, development institutions, sovereign investors and private capital.

That shift sits at the heart of the role the Asian Infrastructure Investment Bank was created to support, Alsayyari said.

AIIB’s 11th annual meeting, to be hosted by Doha, will mark an important milestone as the bank enters its second decade.

Alsayyari said Saudi Arabia and other Gulf countries could lead several global trends in renewable energy, digital infrastructure and water systems in the years ahead.


Norway's Sovereign Fund Proposes Deep Cuts to US Treasury Holdings

A general view of the Norwegian central bank in Oslo, Norway March 6, 2018. Picture taken March 6, 2018. REUTERS/Gwladys Fouche
TT

Norway's Sovereign Fund Proposes Deep Cuts to US Treasury Holdings

A general view of the Norwegian central bank in Oslo, Norway March 6, 2018. Picture taken March 6, 2018. REUTERS/Gwladys Fouche

The manager of Norway's $2.3 trillion sovereign wealth fund has proposed significantly cutting its exposure to US Treasuries as part of a wider shake-up of its bond investments to improve returns, according to a letter published this week.

Norges Bank Investment Management has recommended reducing its weighting to government bonds within its benchmark bond index to 50% from 70%, with US Treasuries, the biggest holding, getting the biggest cut, according to the letter.

The changes would mean cutting nearly $80 billion from the fund's current holdings of about $215 billion of US Treasuries as of the end of June, according to Reuters calculations.

Government bond markets have been under pressure recently, with long-term borrowing costs soaring as rising inflation and government debt levels spooked investors.

Norway's sovereign wealth fund, the world's largest, owns on average 1.5% of ⁠all listed companies ⁠globally. Its scale means that portfolio decisions can influence broader market flows. Any cuts to its bond holdings are unlikely to be implemented until several months into 2027 at the earliest.

The letter containing the fund's proposals was sent in response to questions from Norway's finance ministry about the wealth fund's investment strategy for bonds.

Norges Bank IM said it would await the ministry's response, and any changes would be done gradually to limit market impact and transaction costs.

The proposals will form part of recommendations to the ministry in January.

They will be discussed ⁠as part of the fund's annual white paper process next spring, after which the ministry will make a final recommendation to parliament which will then hold a hearing, a Norges Bank IM spokesperson said.

"We recommend that the government subindex of the bond index be reduced from 70% to 50%," Ida Wolden Bache, governor of Norges Bank, and Norges Bank IM CEO Nicolai Tangen wrote in the letter.

"A government share of 50% will be sufficient to cover the liquidity needs, including in periods of turbulence in financial markets."

The fund also proposed considering an increase in investments in unlisted assets in a separate letter, in part as a way to reduce concentration risks that have grown in its equity portfolio amid the boom in the share prices of a handful of US tech companies.

Under its current mandate the fund can own unlisted real estate and renewable energy assets, but it has a lower share of unlisted investments ⁠than comparable funds.

Norges Bank IM said the biggest change to its bond index would be investing in more non-government debt, including mortgage-backed securities, to give it better diversification and exposure to risk premiums.

The spokesperson said total US dollar exposure would remain around 50%, adding: "What changes is the mix inside the dollar market: less US government debt, correspondingly more US mortgage and government-related bonds."

Under the proposals, the bond index weighting to US government bonds would reduce from 34.1% to 21.9%, according to the letter, with the allocation to euro area debt falling more modestly from 16.8% to 14.1%.

The allocation to Japanese government bonds would increase from 4.6% to 7.4%, while the UK allocation would remain unchanged at 4.2%. The fund said the changes would align the index more closely with the broader market weightings.

While US Treasuries exposure would fall, the proposed allocation to US non-government debt would jump from 16.2% to 27.6%, meaning that the overall bond index's weighting to the US dollar would fall only slightly, from 52.9% to 52.5%.

Europe's biggest pension fund, Dutch fund ABP, cut the value of its own US Treasury holdings in the first quarter of this year, Reuters previously reported.


J.P. Morgan, BNP Paribas Forecast December ECB Rate Hike

FILE PHOTO: The logo of the European Central Bank (ECB) is pictured outside its headquarters in Frankfurt, Germany, April 26, 2018. REUTERS/Kai Pfaffenbach/File Photo
TT

J.P. Morgan, BNP Paribas Forecast December ECB Rate Hike

FILE PHOTO: The logo of the European Central Bank (ECB) is pictured outside its headquarters in Frankfurt, Germany, April 26, 2018. REUTERS/Kai Pfaffenbach/File Photo

J.P. Morgan and BNP Paribas said on Thursday they expect the European Central Bank to deliver another 25-basis-point rate hike in December, as persistent inflation risks and elevated energy prices strengthen the case for further tightening.

Both brokerages had previously expected the ECB's tightening cycle to end without a December rate increase.

The revised outlooks suggest borrowing costs in the euro zone will remain elevated for longer than previously anticipated, reflecting resilient regional economic ⁠growth and ongoing energy ⁠supply concerns.

"We think the persistence of the energy shock and the resilience of the economy make second-round effects more likely to materialize," said analysts at BNP Paribas in a note.

Markets have almost fully priced in ⁠a 25-basis-point interest rate hike by the European Central Bank at its September 10 policy meeting, indicating a 99.2% probability, according to data compiled by LSEG.

Oil prices eased but remained above $95 a barrel. At the same time, eurozone bond yields retreated from multiyear highs, following recent market pressure as the escalating conflict in Iran boosted energy prices, stoking fears of persistent inflation and ⁠tighter ⁠monetary policy.

According to Reuters, J.P. Morgan said "an interaction between more persistent energy price pressures, solid growth, sticky core inflation and a neutral rate that the ECB sees edging higher" would be the reason for a further rate hike in December.

BNP Paribas expects the ECB to hike interest rates by 25 bps at its meeting next week while leaving the door wide open to delivering more if evidence of second-round effects builds.


US Sanctions Turkish Bank Golden Global Over Alleged Iran Links

ASHEVILLE, NORTH CAROLINA - SEPTEMBER 1: Treasury Secretary Scott Bessent arrives for a press conference as the 2026 G20 Financial meetings come to a close on September 1, 2026 in Asheville, North Carolina. Melissa Sue Gerrits/Getty Images/AFPages via AFP)
TT

US Sanctions Turkish Bank Golden Global Over Alleged Iran Links

ASHEVILLE, NORTH CAROLINA - SEPTEMBER 1: Treasury Secretary Scott Bessent arrives for a press conference as the 2026 G20 Financial meetings come to a close on September 1, 2026 in Asheville, North Carolina. Melissa Sue Gerrits/Getty Images/AFPages via AFP)

The US Treasury Department on Friday imposed sanctions on a Turkish bank over its alleged ties to Iran's Revolutionary Guard Corps (IRGC), as Washington pushes to economically isolate Tehran six months into their war. 

The latest action targets Golden Global Bank and its subsidiaries, which the US Treasury said "facilitated tens of millions of dollars' worth of transactions" for the IRGC. 

They were also said to have provided Tehran with "key correspondent banking access that allows it to move its funds internationally." 

The bank denied the accusations, saying it "has not concluded any banking transactions that could substantiate" the claims by the US government. 

The institution, which describes itself as "the first investment bank in Türkiye that observes the principles of interest-free banking in all its operations," said it respects "all applicable local and international banking regulations, practices and compliance requirements." 

Last week, Washington took a step towards cutting a major Egyptian bank's United Arab Emirates operations from the US financial system. 

"Financial institutions continue to find out the hard way that we are serious about Operation Economic Outcast," said US Treasury Secretary Scott Bessent in a statement. 

"While we hope no more banks will need to be sanctioned, that ultimately depends on how quickly the international community comes to its senses and ceases support of the murderous Iranian regime," he added. 

Bessent had said Tuesday that Washington would likely announce a bank sanction this week and one next week, as it tries to choke off Tehran economically. 

He was speaking on the sidelines of a Group of 20 finance leaders' gathering in Asheville, North Carolina, where he also sought to rally support from partners to put pressure on Iran. 

Iran has been at war since late February, when the United States and Israel launched a surprise bombing campaign that killed its supreme leader. 

Bessent recently vowed that the United States was declaring an "economic D-Day" on Iran, and warned of harsh consequences for countries that do not join the campaign.