Winter Tests European Energy Security... Algeria Advances to the Forefront

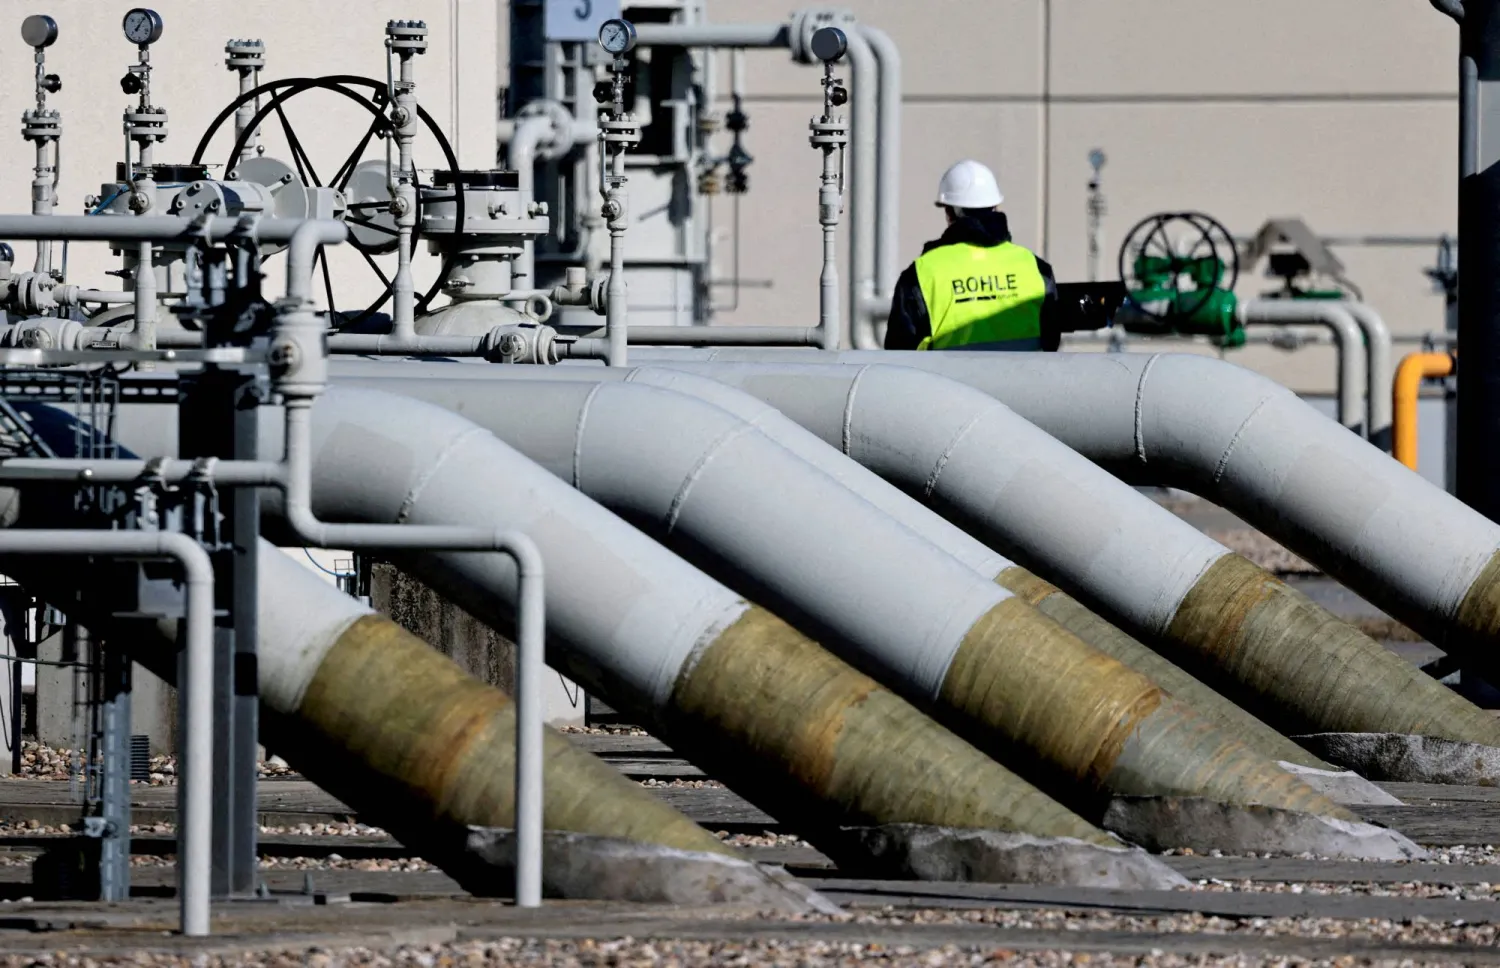
Pipes at the landfall facilities of the “Nord Stream 1” gas pipeline are pictured in Lubmin, Germany, March 8, 2022. (Reuters)
TT

Winter Tests European Energy Security... Algeria Advances to the Forefront

Pipes at the landfall facilities of the “Nord Stream 1” gas pipeline are pictured in Lubmin, Germany, March 8, 2022. (Reuters)

Europe is approaching winter facing a more complex gas equation than in previous years: lower-than-usual inventories, prices that have surged to levels the market has not witnessed in years, and disrupted Qatari supplies due to the war in the Middle East, all while Brussels moves forward with phasing out Russian gas.

At the heart of this equation, Algeria emerges as one of the most critical available alternatives, particularly for European countries bordering the Mediterranean, while Germany is moving more seriously for the first time to secure long-term contracts for Algerian gas.

Europe’s primary concern is not an immediate gas shortage, but a narrow safety margin ahead of the heating season, with EU inventories at approximately 64.7 percent in early September and Germany in a particularly vulnerable position. Simultaneously, the benchmark Dutch TTF gas price climbed to roughly 69.90 euros per megawatt-hour - its highest level since January 2023 - amid rising anxieties over liquefied natural gas (LNG) supplies from the Gulf.

The sensitivity of the situation is heightened because the European market does not only need to fill its storage facilities before winter, but must do so at a time when Asia is competing for the exact same shipments of LNG, making any additional supply shortfall even more costly.
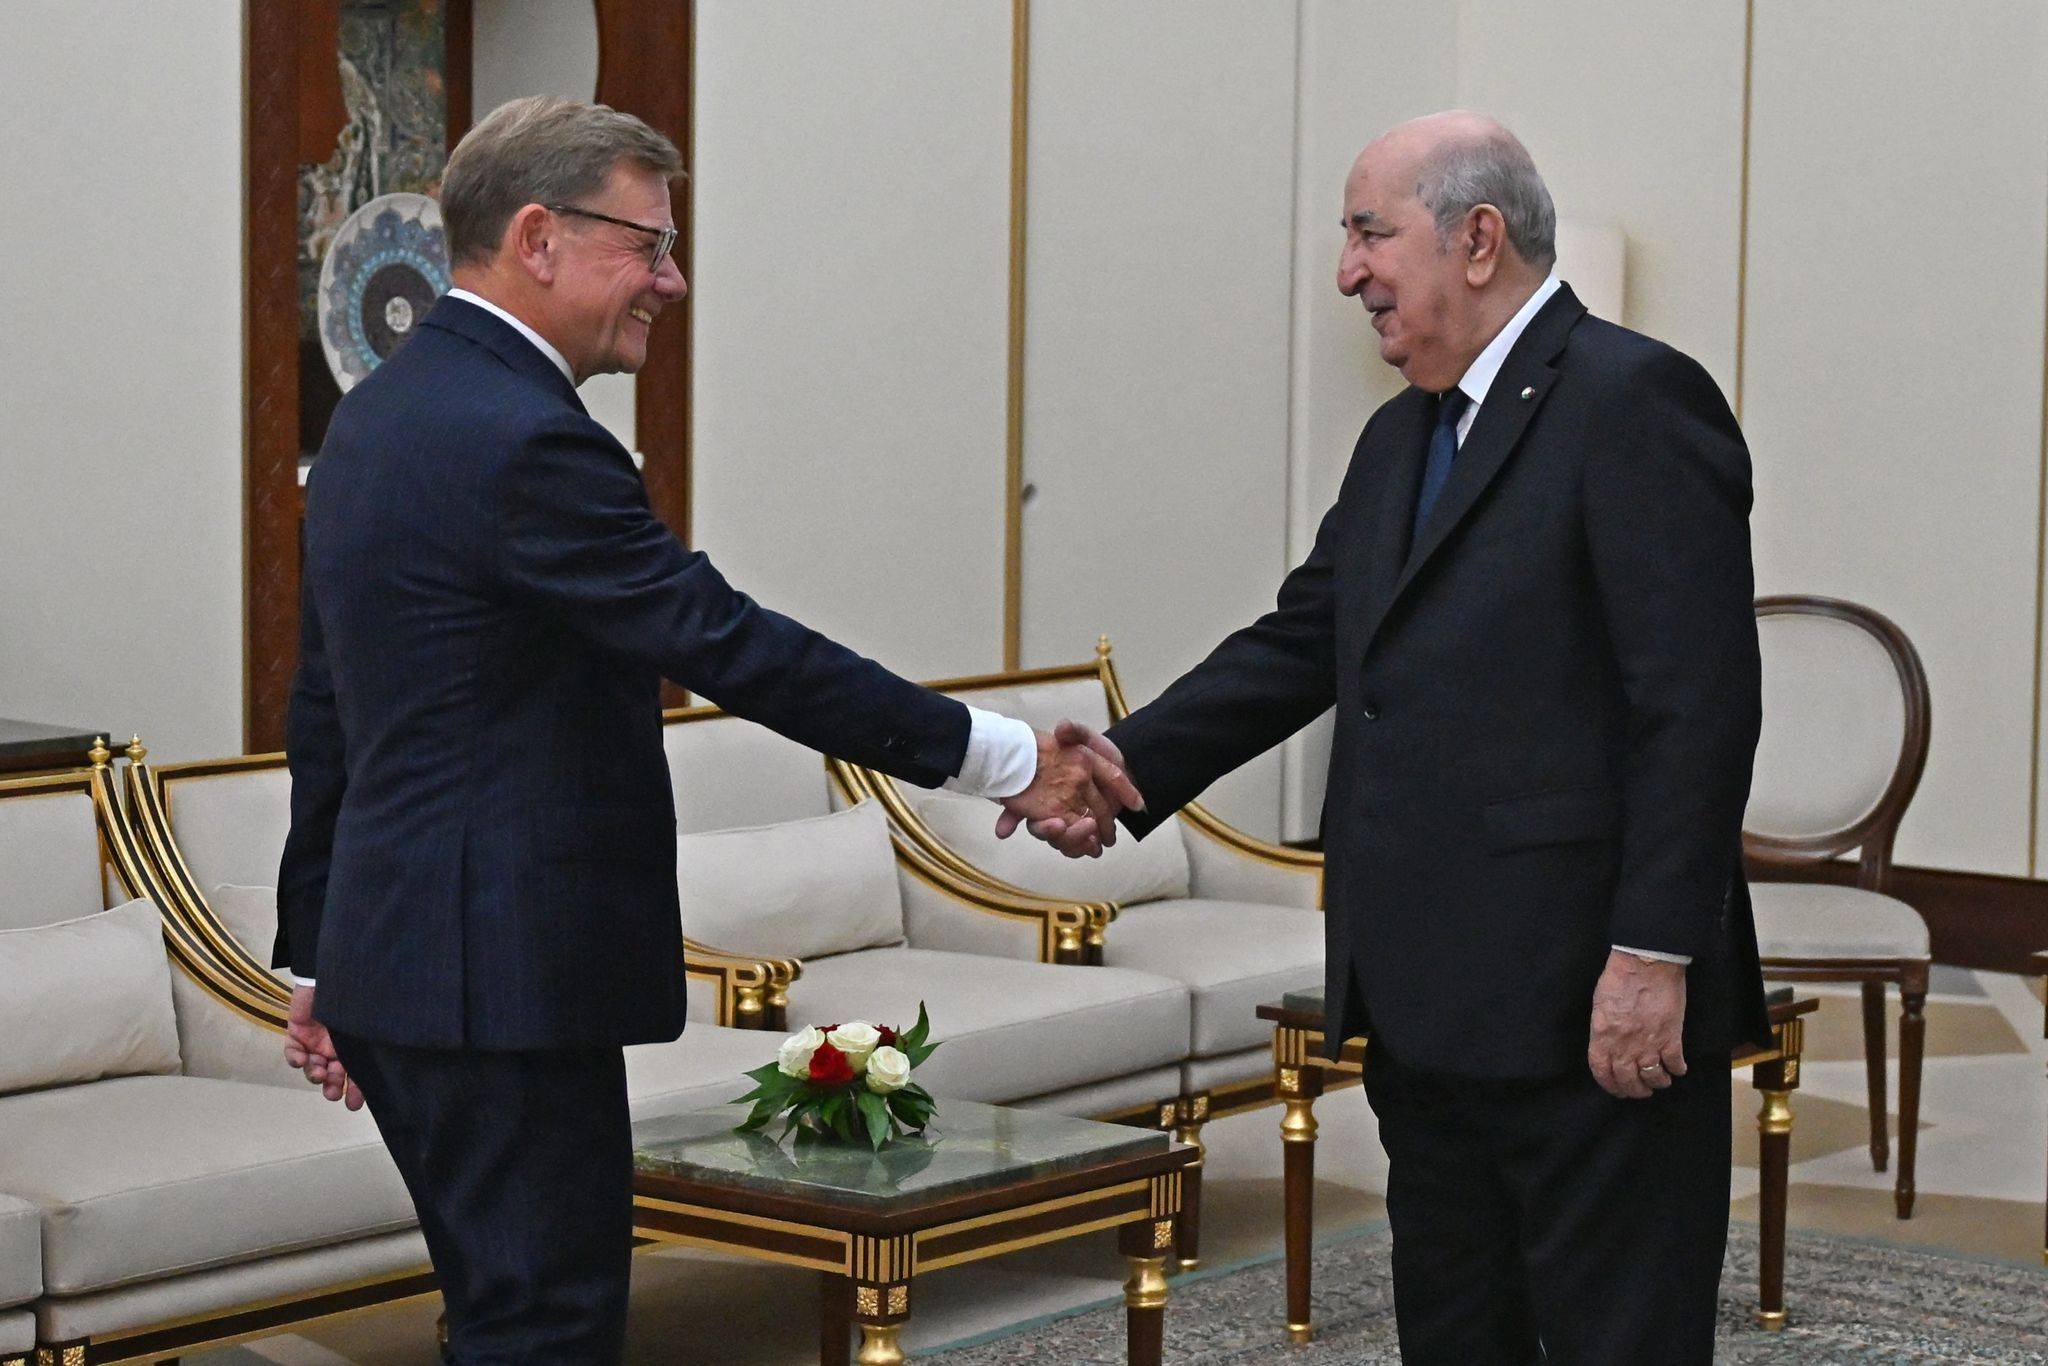
01 September 2026, Algeria, Algier: Johann Wadephul (L), German Foreign Minister, meets with Abdelmadjid Tebboune, President of Algeria. (dpa)

Algeria enters the spotlight

In this scene, Algeria is advancing to the forefront of the European scene as a nearby supplier capable of providing gas through pipelines, alongside LNG shipments.

During his visit to Algeria on Tuesday, German Foreign Minister Johann Wadephul said his country wants to negotiate long-term gas contracts with Algeria, stressing that diversifying supply sources has become a necessity and that Algeria represents a reliable source that can help meet Germany’s needs.

The German move does not come from a vacuum; Germany’s VNG and Algeria’s company Sonatrach signed a new gas supply contract in July, with deliveries scheduled to begin in 2027, as part of expanding and diversifying the German company's portfolio of gas sources.

Germany and Algeria underscored the importance of their energy partnership in July, expressing mutual interest in increasing gas supplies and cooperating on the Southern Hydrogen Corridor project. This collaboration reflects a strategic effort to establish an enduring energy relationship that extends beyond short-term supply security.

Why Algeria?

Algeria is gaining increasing importance in the European energy security equation, not only as a primary supplier of gas but also due to its weight in the oil market as a member of the Organization of the Petroleum Exporting Countries (OPEC) since 1969, producing around one million barrels per day of crude oil, including high-quality Sahara Blend. Alongside its oil wealth, Algeria possesses around 4.5 trillion cubic meters of proven natural gas reserves, cementing its position as the largest gas producer in Africa and providing a resource base capable of supporting its role as a long-term supplier to global markets.

Algeria's importance to Europe is magnified by its geographic proximity to the continent's markets and its existing export infrastructure, which includes pipelines and LNG networks. These advantages allow Algeria to respond to shifts in European demand more rapidly than suppliers that require massive investments and new infrastructure before increasing their deliveries.

The vast scale of the European market reveals both the scope of the opportunity and the challenge facing Algeria simultaneously. European Union natural gas consumption reached around 339 billion cubic meters in 2025, while domestic production did not exceed 33 billion cubic meters, leaving the continent heavily dependent on imports.
US President Donald Trump during a visit to a liquid natural gas export terminal in Louisiana. (Reuters)

With European demand projected to decline by more than 2 percent in 2026, the primary issue is not consumption growth, but rather securing supplies and diversifying their sources, particularly as Europe continues to reduce its reliance on Russian gas.

Algeria already plays a pivotal role in supplying southern Europe, particularly Italy and Spain, while Germany seeks to secure a share of Algerian supplies as part of its efforts to diversify gas sources and reduce reliance on traditional suppliers. The movement of Algerian flows to Europe reveals flexibility in directing exports according to market needs; while some flows to Italy declined, supplies heading to Spain rose, reinforcing Algeria's role in balancing the European market.

However, this importance does not mean that Algeria is capable on its own of filling the gap left by the decline of Russian supplies or any potential shortfall in Qatari deliveries. The scale of Algerian production and export capacities is insufficient to fully compensate for these supplies. Consequently, the European wager on Algeria is not based on replacing one supplier with another, but rather on a gradual reshaping of the European energy map, diversifying supply sources, and reducing the risks of relying on any single provider.
3D-printed oil pump jacks and the QatarEnergy logo appear in this illustration taken March 2, 2026. (Reuters)

Qatar absent at the worst time

The larger issue for Europe is that Qatar, which has been one of the world's most critical sources of LNG, is absent from the market at a time when the continent needs every possible additional shipment.

According to Reuters data, Qatar's LNG exports fell by around 96 percent during the first six months of the US-Israel war on Iran, with the number of shipments leaving Qatar dropping to just 18, compared to 509 during the same period last year.

This is no longer limited to a temporary disruption; QatarEnergy has extended the suspension of gas shipments to Italy’s Edison until early November, resulting in the cancellation of five additional shipments. This brings the total number of suspended shipments to 29, equivalent to around 3.8 billion cubic meters of gas.

Herein lies the paradox: Europe is entering the phase of replenishing its inventories, while one of the world's largest suppliers of LNG is unable to return to the market at full capacity.

Russia leaving the picture but not fast enough for Europe

On the opposing side, Europe is moving forward along the political and legal path to end its reliance on Russian gas. The European Union has adopted a gradual plan to ban Russian gas imports, with a full ban on long-term liquefied natural gas contracts set to begin in January 2027, and pipeline gas contracts facing a ban by September or November 2027 at the latest.

Russian gas remains present in the European market despite EU efforts to reduce reliance on it. EU countries imported over 16 percent more Russian liquefied natural gas during the first half of 2026 compared to the same period last year, totaling approximately 5.96 billion euros (USD$6.9 billion), with France, Belgium, and Spain leading as the top importers according to data from the German non-profit organization Urgewald.

These figures reflect the continued reliance of some European markets on Russian gas during the transitional phase, even as the EU moves toward a gradual phase-out of these imports and the diversification of its supply sources. This reveals the contradiction facing Europe: a political decision to eliminate Russian gas versus an ongoing market need for supplies before alternative options are fully realized.
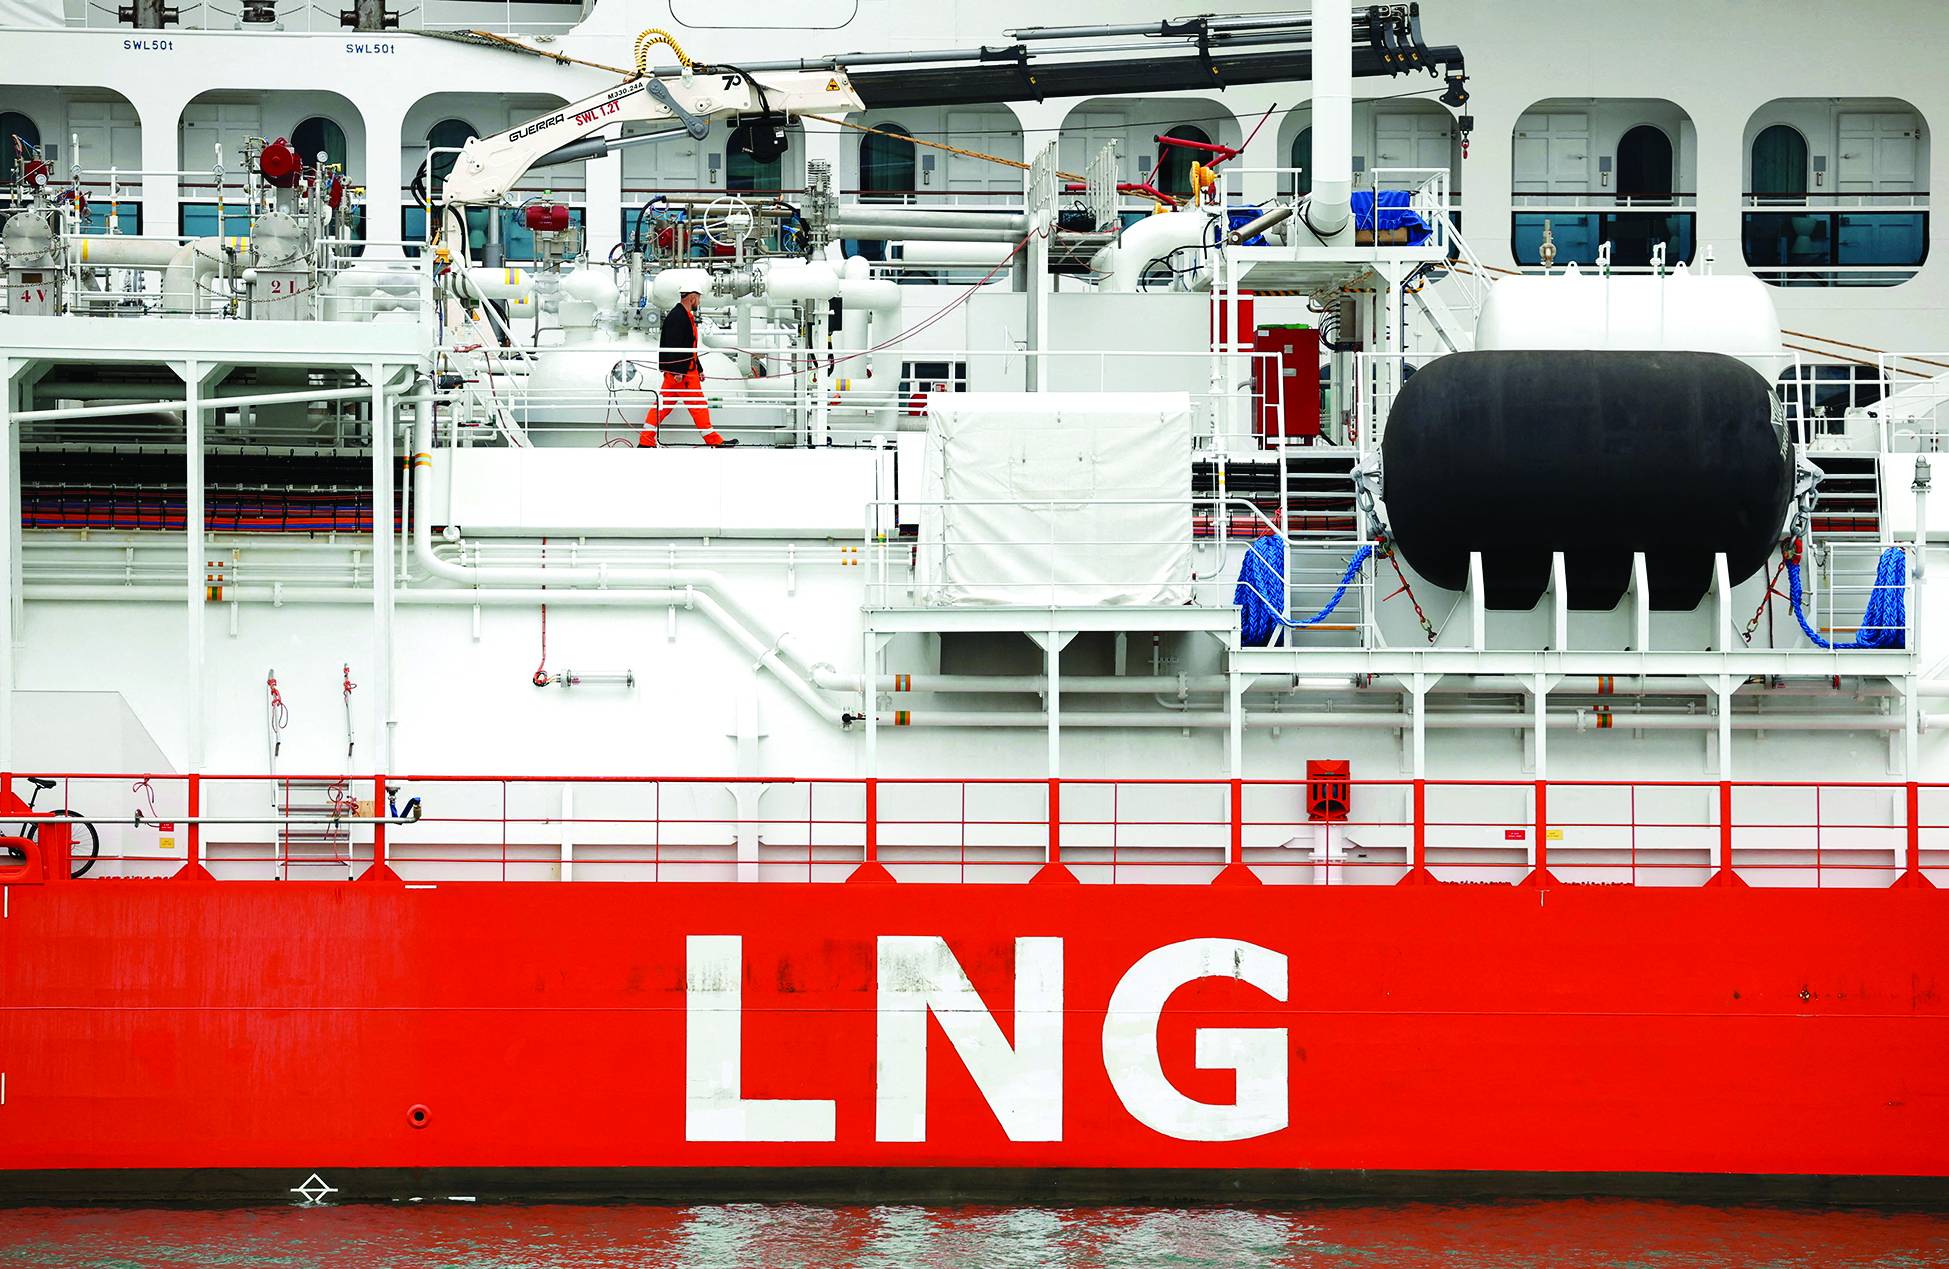
An LNG (Liquefied Natural Gas) ship loads gas to a cruise ship in Barcelona, Spain, January 29, 2024. (Reuters)

Market prices the risk

This equation was directly reflected in prices as the Dutch TTF gas contract rose to approximately 69.90 euros per megawatt-hour on September 1, marking a 4.4 percent increase in a single session. Market data indicates that European gas prices have surged by more than 130 percent since the beginning of the year.

Most importantly, the price curve itself reflects anxiety regarding the winter season, as near-term prices have become higher than some futures contract prices. This phenomenon, known as backwardation, means the price of a commodity for immediate or near-term delivery is higher than its price for future delivery, which weakens the economic incentive for traders to store large quantities of gas now, despite Europe’s need for it ahead of winter.

In the most severe scenario, European gas prices could exceed 100 euros per megawatt-hour if LNG supplies from the Middle East remain limited and competition with Asian buyers intensifies.

Winter is the real test

Therefore, the European question this winter will not be: Is there gas in the market? Rather, it will be: Is there enough gas at a price that Europe can afford?

Europe today possesses more diverse sources than it did during the 2022 crisis, with increased reliance on Norway, the United States, and Algeria, alongside the expansion of infrastructure to receive liquefied natural gas. However, this new flexibility has not eliminated the market's sensitivity to geopolitical shocks.

Europe requires substantial volumes of US LNG to offset a portion of the shortfall, but the US itself faces growing domestic gas demand, particularly with the expansion of data centers and artificial intelligence, while US gas exports cannot be increased indefinitely at a rapid pace. In July, Europe received 4.76 million tons of US gas, compared to 3.32 million tons that went to Asia.
A pressure gauge is pictured at a Gaz-System gas compressor station in Rembelszczyzna outside Warsaw October 13, 2010. (Reuters)

Algeria is an important, not a sole alternative

Algeria is therefore acquiring increasing strategic importance. It is located close to Europe, possesses existing pipelines, and has extensive experience in gas exports, while it has already begun expanding its relations with European companies.

However, the European wager on Algeria does not mean the country can single-handedly fill the supply gap left by Russia and Qatar. New German demand for Algerian gas and emerging contracts reflect a broader strategic shift toward diversifying suppliers and minimizing reliance on any single source.

Ultimately, Europe's ability to safely navigate the winter will be determined by three interconnected factors: the volume of available supplies, the speed of inventory replenishment, and the severity of winter temperatures. If a cold winter coincides with the continued absence of Qatari gas and weak Russian supplies, Europe may find itself forced to pay higher premium prices to attract global shipments, while Algeria, Norway, the US, and other sources become central to the battle to secure every additional unit of gas.

So, the upcoming European gas crisis does not appear to be a mere storage issue, but rather a test of the new system built by Europe following the collapse of the Russian gas model; a system that is more diversified, yet more exposed to global prices, Asian competition, and geopolitical shocks.


Lebanese Banks Escalate Dispute Over Taxes on Unrealized Gains

Finance Minister Yassine Jaber meets with a delegation from the Association of Banks in Lebanon in October 2025 (National News Agency)
TT

Lebanese Banks Escalate Dispute Over Taxes on Unrealized Gains

Finance Minister Yassine Jaber meets with a delegation from the Association of Banks in Lebanon in October 2025 (National News Agency)

Lebanese banks have escalated their dispute with the Ministry of Finance, announcing a one-day strike every week starting Wednesday in protest against demands to amend their tax returns for 2020 through 2024. The proposed adjustments would subject unrealized accounting gains and provisions set aside to cover actual losses to taxation.

The Association of Banks in Lebanon (ABL) has authorized its board of directors to take further action if the relevant authorities fail to respond to its demands. The association is seeking a legislative resolution to the dispute as Parliament prepares to discuss next year's draft state budget.

The unanimous decision to strike follows a letter the association received from the Finance Ministry several days ago. The ministry said its audit departments would begin reviewing banks' tax returns in the middle of next month to verify their accuracy and compliance with existing laws, while allowing taxpayers to challenge any subsequent tax assessments or penalties.

The banks have called on the authorities to withdraw the request for amended tax returns, reconsider the proposed tax treatment and take the necessary measures, including legislative amendments where needed, to exclude unrealized accounting gains and loss provisions from taxable income.

The association believes Parliament's consideration of next year's draft budget provides an opportunity to resolve the issue through legislative amendments.

Dispute Over Constitutionality of Tax Assessments

On the legal front, the banks base their objections, as previously reported by Asharq Al-Awsat, on Articles 81 and 82 of the Lebanese Constitution, which require new taxes or changes to existing taxes to be enacted through legislation passed by Parliament.

The association argues that administrative regulations cannot serve as a sufficient basis for imposing new tax liabilities. It maintains that accounting differences arising from the collapse of the Lebanese pound, calculated using the difference between historical cost and the prevailing exchange rate, do not represent genuine profits but reflect actual losses that should not be taxed.

The Finance Ministry, meanwhile, bases its position on regulatory decisions issued by the finance minister and an opinion issued by the Legislation and Consultation Commission in early 2025. Under the ministry's interpretation, these provide grounds for taxing banks on accounting differences arising from the gap between the historical cost exchange rate and the dollar's actual exchange rate at the time of assessment.

The banks warn that collecting the disputed taxes, estimated at approximately $600 million, would deplete part of their remaining cash liquidity and undermine their ability to repay depositors. They argue that the measures would place additional burdens on both banks and depositors as a result of a crisis in which the state defaulted on its obligations.

The association maintains that protecting available liquidity and directing it toward repaying depositors should take precedence over collecting taxes on gains it describes as unrealized and existing only on paper.

The dispute has intensified over recent weeks through a series of exchanges between the ministry and the banks, following the ministry's demand that lenders submit revised tax returns retroactively for the five years from 2020 through 2024.

The banks had requested joint meetings to clarify what they consider shortcomings in the proposed tax treatment before formally rejecting the required measures in their latest letter, citing legal, accounting and regulatory concerns.

According to the banking association's legal and accounting assessment, the disputed foreign exchange differences arose from the revaluation of accounts following the sharp depreciation of the Lebanese pound. They do not constitute actual profits or represent a genuine increase in banks' wealth or ability to pay taxes.

The association also argues that the provisions in question were established to cover actual losses resulting from the state's failure to meet its obligations, in accordance with applicable accounting and regulatory standards. Taxing these amounts, it says, fails to distinguish between realized profits, accounting gains and actual losses.

In explaining its position, the association draws a distinction between profits generated through economic activity and nominal or accounting gains resulting from extraordinary currency fluctuations and the revaluation of accounts. It stresses that the latter do not reflect any genuine increase in banks' wealth or taxable capacity.

As for provisions against Eurobond holdings, the association says they were established in accordance with applicable accounting and regulatory standards, with the approval of the Banking Control Commission of Lebanon, to account for losses arising from the Lebanese government's default on its debt obligations.

In a statement, the association reiterated its categorical rejection of the Finance Ministry's demand to amend tax returns, arguing that the proposed measures would impose taxes on unrealized accounting gains and provisions intended to cover losses resulting from the government's default on Eurobonds.

It said its position was driven by its responsibility to protect depositors' rights and preserve the banking sector's remaining liquidity.


Saudi Arabia Elected to International Telecommunication Union Council

A session of the ITU Plenipotentiary Conference (PP-26) in Doha (Communications, Space and Technology Commission)
TT

Saudi Arabia Elected to International Telecommunication Union Council

A session of the ITU Plenipotentiary Conference (PP-26) in Doha (Communications, Space and Technology Commission)

Saudi Arabia has been elected to the Council of the International Telecommunication Union (ITU) for the 2027–2030 term, joining 47 other countries on the 48-member council, elected from the union’s 194 member states. The election took place during the ITU Plenipotentiary Conference in Doha, Qatar.

The election strengthens Saudi Arabia’s role in shaping the ITU’s strategic direction and setting international priorities in the telecommunications, space and technology sectors. It also supports efforts to bridge the digital divide and expand access to modern technologies and artificial intelligence.

Minister of Communications and Information Technology and Chairman of the Board of Directors of the Communications, Space and Technology Commission (CST), Abdullah Al-Swaha, said Saudi Arabia’s election reflects the international community’s confidence in the Kingdom’s role and contributions to advancing the telecommunications, space and technology sectors and strengthening international partnerships.

He said the Kingdom is working with its partners to expand opportunities to benefit from technology and help countries build their digital capabilities.

CST Governor Haitham Al-Ohali said the council membership reflects confidence in Saudi Arabia’s contributions to the ITU and its ability to work with the international community to achieve the union’s objectives.

He added that the Kingdom would work with its partners during the upcoming term to strengthen digital infrastructure, develop capabilities and support developing countries in expanding access to telecommunications services, helping bridge the digital divide and broaden access to technology and artificial intelligence.

The ITU Council oversees the organization’s work between Plenipotentiary Conferences, monitoring its policies, strategies and financial plans. Membership gives countries a role in guiding international efforts in the telecommunications and technology sectors.

Saudi Arabia joined the ITU in 1949 and was first elected to its Council in 1965. Since then, the Kingdom has contributed to the union’s work and initiatives and helped shape its policies and strategies.


Saudi Arabia Issues Over 80,000 Building Permits in Nine Months

A residential development in Saudi Arabia’s Qassim region (SPA)
TT

Saudi Arabia Issues Over 80,000 Building Permits in Nine Months

A residential development in Saudi Arabia’s Qassim region (SPA)

Saudi Arabia issued more than 80,000 building permits during the first nine months of 2026 as part of efforts to regulate urban growth, improve city efficiency and attract investment in urban development.

The Ministry of Municipalities and Housing said permits are issued through the Balady platform using streamlined electronic procedures. The process involves selecting the permit type, entering the applicant’s information, choosing the cadastral survey report and submitting the required plans and documents through an engineering office. Permits are issued once all requirements have been met.

The ministry said the procedures help regulate construction and urban development, simplify permitting to support investment, improve the urban landscape and enhance the quality of municipal services by accelerating processes and improving the user experience.