‘Nomura’ to Asharq Al-Awsat: Bond Yields Reshape Region’s Cost of Capital

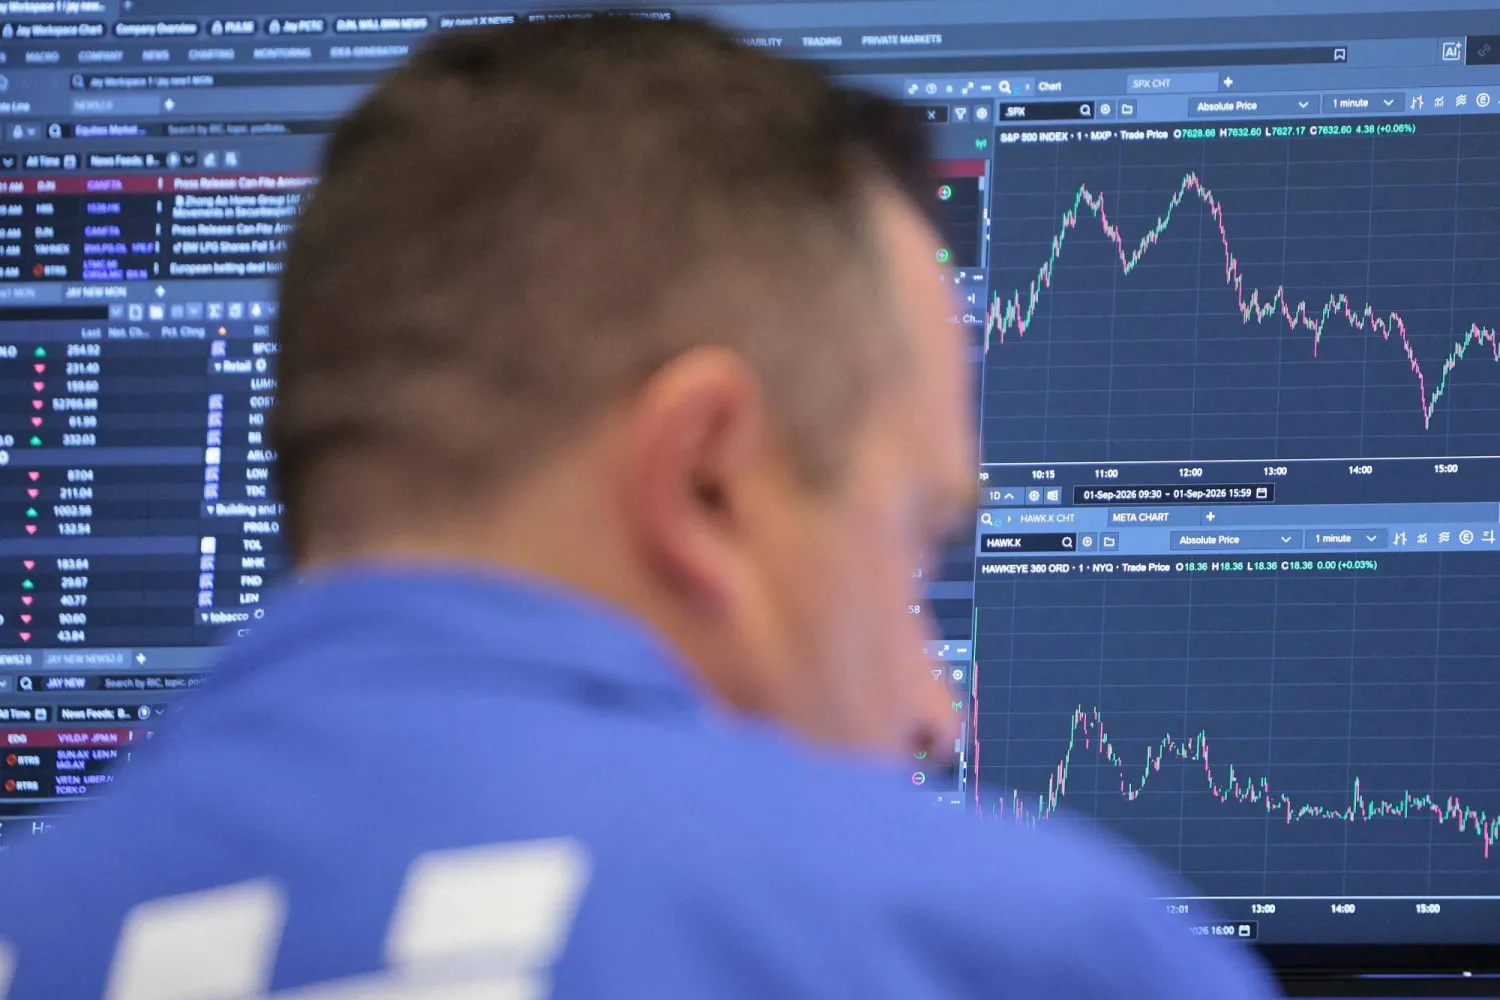
Traders work on the floor of the New York Stock Exchange during morning trading on September 02, 2026 in New York City. (Getty Images/AFP)
TT

‘Nomura’ to Asharq Al-Awsat: Bond Yields Reshape Region’s Cost of Capital

Traders work on the floor of the New York Stock Exchange during morning trading on September 02, 2026 in New York City. (Getty Images/AFP)

Global debt markets are entering a new era of higher borrowing costs, with US, Japanese and British bond yields climbing to levels not seen in years amid three overlapping pressures: inflation fueled by oil prices, ballooning fiscal deficits and rising government borrowing needs.

As investors reassess the risks of holding long-term debt, the repercussions are spreading to regional markets through higher financing costs for governments and companies. This is placing Gulf economies under a fresh cost-of-capital test, although they have stronger financial buffers than many emerging markets.

In an exclusive assessment for Asharq Al-Awsat, Tarek Fadlallah, chief executive officer of Nomura Asset Management Middle East, said the latest jump in bond yields had a temporary component linked to geopolitical tensions and oil prices.

“But it also reveals a deeper shift in debt markets, amid growing concerns that elevated yields could prove more persistent because of chronic fiscal deficits and increasing borrowing needs in major economies,” he said.

Fadlallah’s assessment comes as global bond markets undergo a broad repricing, with yields on major government debt rising as concerns over energy-driven inflation converge with widening fiscal deficits and growing borrowing requirements.

In the United States, the 10-year Treasury yield approached 5% after rising by more than 80 basis points since the beginning of March, while the 30-year yield surpassed levels not seen in nearly 19 years. In Japan, the 10-year government bond yield exceeded 3% for the first time since 1996, while its British counterpart climbed to 5.268%, its highest level since June 2008.
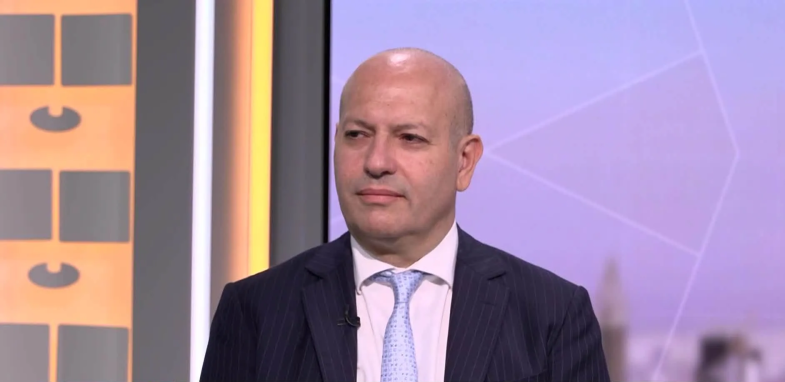
Tarek Fadlallah, chief executive officer of Nomura Asset Management Middle East. (LinkedIn)

These moves are particularly significant because they point to a change in how debt-market risks are priced, with investors focusing increasingly on long-term fiscal prospects rather than only on central banks’ next policy decisions. That means borrowing costs could remain elevated even if some short-term pressures subside, placing public finances and debt sustainability under greater market scrutiny.

Bond markets showed early signs of stabilizing on Thursday, with the US 10-year Treasury yield easing to about 4.77% and its Japanese counterpart falling back below 3%. Yields, however, remained elevated compared with their levels before the latest sell-off, leaving open the question of whether the recent turbulence represents a temporary correction or the start of a deeper shift in global borrowing costs.

The surge in yields coincided with growing global attention to borrowing costs and public debt, which have emerged among the economic and financial issues under discussion within the G20. Finance ministers and central bank governors have been examining the implications of tighter financing conditions for the global economy and financial markets. This reflects how the bond issue has broadened beyond market movements into a wider economic and financial concern involving fiscal sustainability, the trajectory of inflation and major economies’ capacity to shoulder mounting debt burdens.

These concerns have also coincided with International Monetary Fund warnings that rising bond yields in advanced economies are increasing borrowing costs worldwide and putting greater pressure on financial markets, as global public debt approaches 100% of gross domestic product and progress in bringing down inflation loses momentum in several economies.

Energy shocks and rising investment linked to artificial intelligence are adding new sources of pressure on inflation and growth.
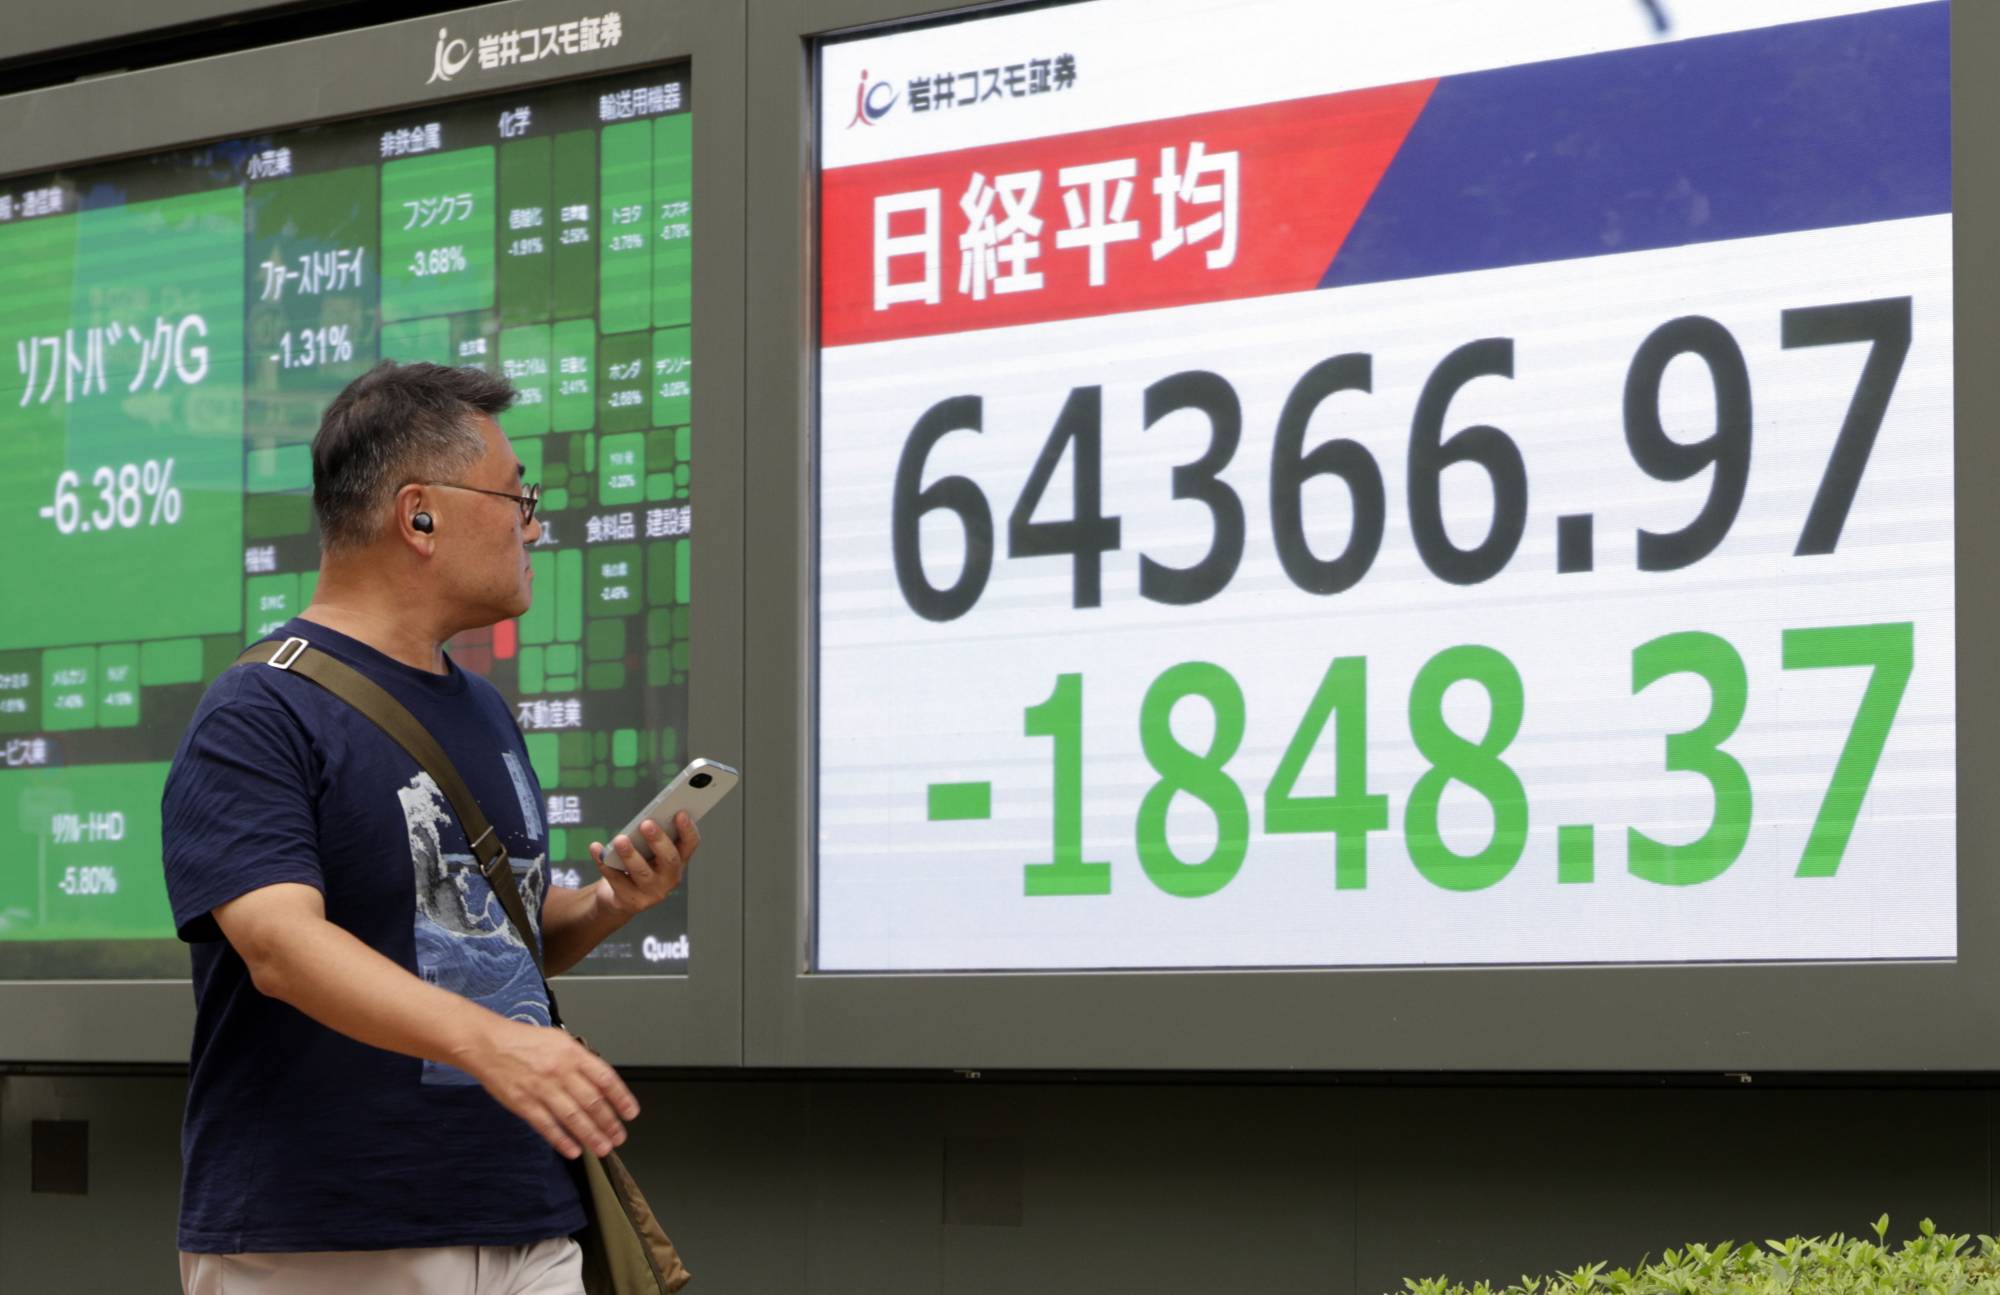
A passerby walks past a stock market indicator board in Tokyo, Japan, 02 September 2026. (EPA)

Is the rise temporary or the start of a new yield regime?

Fadlallah said the most important shift in the bond market was the move away from pricing based on short-term monetary policy expectations toward a reassessment of the risks involved in holding long-term debt, with investors demanding higher returns to compensate for duration, inflation and fiscal risks.

US debt lies at the heart of this equation after the national debt exceeded $40 trillion - a development Fadlallah described as “a clear reminder of the scale of the fiscal challenge facing the world’s largest bond market.”

“With long-term bonds leading the sell-off, markets are repricing what governments must pay to finance their needs, not merely what central banks determine through short-term interest-rate decisions,” he said.

The consequences of this shift extend beyond debt markets. US Treasuries serve as the main pricing benchmark for what is known as the “risk-free asset,” meaning that higher Treasury yields raise the discount rate used to value a broad range of assets, from equities to sovereign and quasi-sovereign bonds worldwide.

5% puts equities to the test

This equation is particularly important for US equities as the 10-year Treasury yield approaches 5%, a level investors view as a psychological threshold that could prompt some to shift their portfolios away from riskier assets and toward bonds.

The developments follow a strong US corporate earnings season, potentially shifting investors’ attention gradually from company results to broader economic and financial variables, led by yields, inflation and monetary policy.

Equity valuations also remain relatively high. The S&P 500’s forward price-to-earnings ratio stood at about 19.7, down from 22.2 at the beginning of the year but still above its historical average of about 16.

For Fadlallah, the combination of fiscal concerns, higher yields, elevated asset valuations and concentrated investment portfolios presents an important test for equities.

The market response has so far remained relatively limited, he said, “but the coming weeks will be crucial in determining whether investors can absorb higher yields or whether the pressure will trigger a broader shift toward reducing risk.”
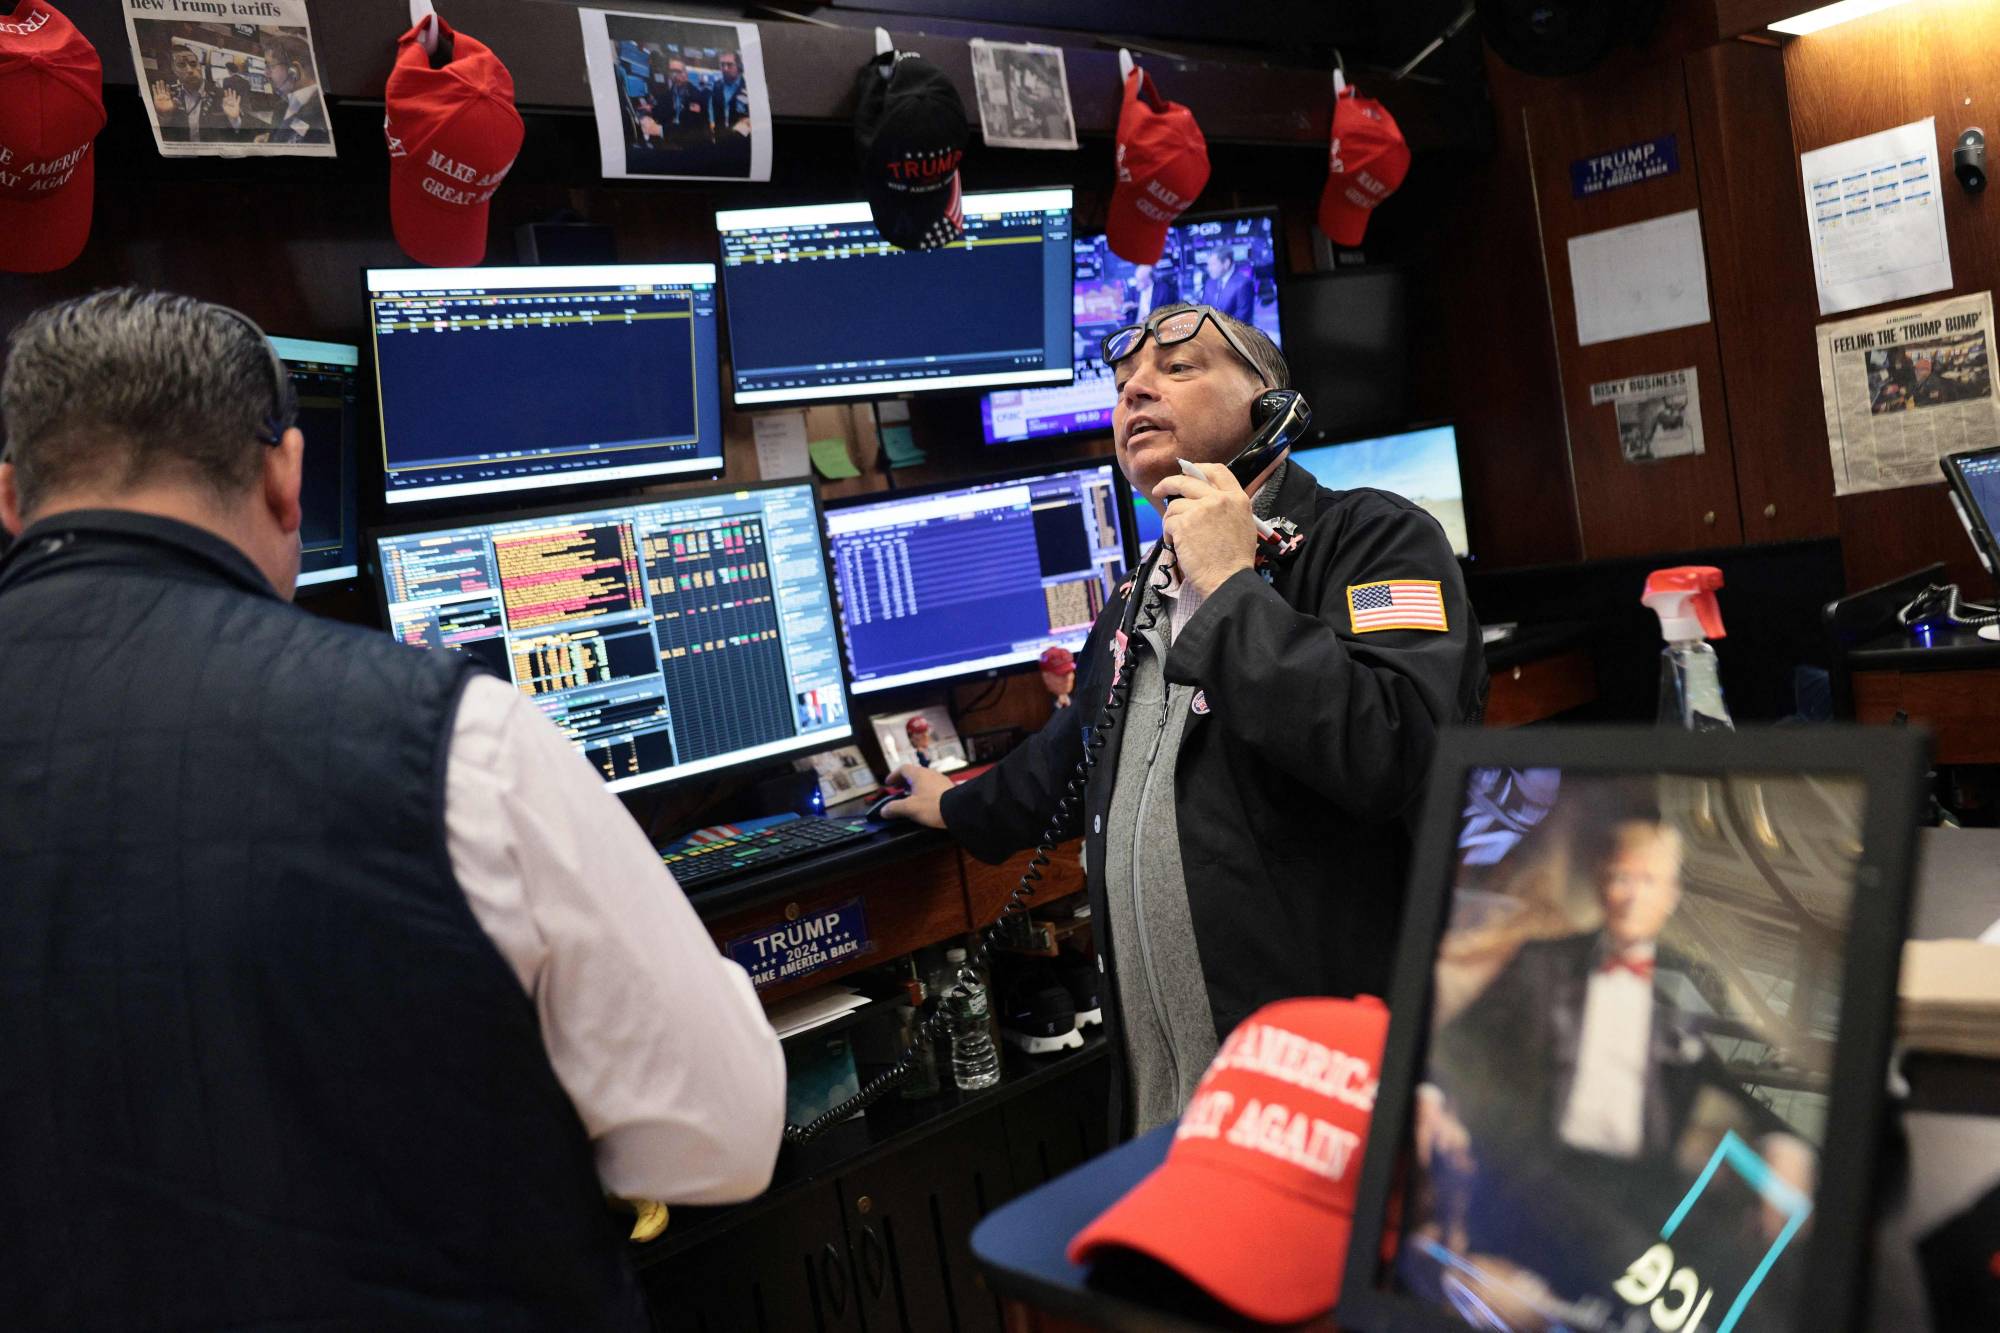
Traders work on the floor of the New York Stock Exchange during morning trading on September 02, 2026 in New York City. (Getty Images/AFP)

Japan: The end of cheap money?

The significance of the yield surge is not limited to the US and Europe. Fadlallah said the more profound development could come from Japan, which for nearly three decades has played a central role in supplying low-cost capital to global markets.

With the 10-year Japanese government bond yield reaching 3%, the equation is becoming more complicated for investors accustomed to borrowing cheaply in yen and investing the proceeds in higher-yielding assets abroad through what is known as the “carry trade.”

“The era of near-zero Japanese yields may be approaching its end, potentially changing the direction of global capital flows,” Fadlallah said.

“Higher domestic yields in Japan could make Japanese assets more attractive to hold while reducing the appeal of borrowing in yen to finance investments in overseas markets.”
A trader talks on the phone during a bond auction on a trading floor in Madrid July 5, 2012. (Reuters)

Gulf faces higher borrowing costs, but has buffers

These developments have a “direct” impact on Gulf economies because most regional currencies are pegged to the US dollar. This transmits the effect of higher US yields to the borrowing costs of governments and companies, both in domestic markets and when issuing debt internationally.

Fadlallah said this would raise the cost of financing projects and refinancing existing debt.

“But it does not eliminate the region’s ability to continue pursuing its investment and economic diversification plans, given its oil revenue, financial buffers and strong sovereign positions,” he added.

Higher financing costs do not necessarily mean a decline in Gulf investment.

“But they will make efficient capital allocation and the economic returns generated by projects more important, with priority given to investments capable of delivering sustainable returns and benefiting from the strong fiscal and sovereign positions that give regional states greater room to maneuver,” he noted.

Will the yield surge subside?

Despite the structural shift in some of the bond market’s driving forces, Fadlallah does not believe yields are destined to keep rising in a straight line.

He said the fastest scenario for reversing the current surge “would be an easing of geopolitical tensions and a decline in oil prices, which would reduce the risk premium and calm inflation expectations.”

“A sharp fall in equity markets, data confirming that inflation has returned to a clear downward path, or coordinated intervention by central banks” could also “drive investors back toward bonds and push yields lower,” he stressed.

The greater risk, according to Fadlallah, is that large fiscal deficits and mounting borrowing needs become a permanent reality.

“This would mean markets may have to live with ‘higher for longer’ yields, not only because of monetary policy but also because investors will demand greater returns in exchange for financing heavily indebted governments,” he explained.

The current sell-off may therefore be more than a temporary episode in the interest-rate cycle. It could mark the beginning of a broader repricing of the cost of global capital - an equation that will shape equities, bonds and investment, as well as Gulf economies entering this phase from a position of greater strength but not insulated from the worldwide rise in borrowing costs.


Saudi Stock Market Closes 0.82% Higher, Led by Energy Sector

A market data display at the Saudi Tadawul Group headquarters in Riyadh (Tadawul)
TT

Saudi Stock Market Closes 0.82% Higher, Led by Energy Sector

A market data display at the Saudi Tadawul Group headquarters in Riyadh (Tadawul)

Saudi Arabia's benchmark Tadawul All Share Index (TASI) ended Sunday's session up 0.82 percent at 10,189 points, with trading turnover reaching SAR 2.3 billion ($613 million).

The index hit an intraday high of 10,215 points and a low of 10,107 points.

Among sectors, energy led the gains, rising 1.99 percent, supported by a 2.06 percent increase in Saudi Aramco shares, which closed at SAR 25.80.

Al Arabia, Ladun and Saudi Vitrified Clay Pipe Co. were the top gainers, advancing between 7 and 9 percent to close at SAR 42.12, SAR 1.99 and SAR 16.90, respectively.

On the losing side, Watani Iron Steel topped the list of decliners, falling 8 percent to SAR 3.22, followed by Najran Cement, which dropped 2.32 percent to SAR 5.47, and SAICO, which shed 2.12 percent to close at SAR 9.25.


Lebanon Weighs $2 Billion Plan to Boost Consumption and Production

A boy jumps off a rock into the Mediterranean Sea in Beirut, Lebanon, Saturday, Oct. 17, 2026. (AP Photo/Hassan Ammar)
TT

Lebanon Weighs $2 Billion Plan to Boost Consumption and Production

A boy jumps off a rock into the Mediterranean Sea in Beirut, Lebanon, Saturday, Oct. 17, 2026. (AP Photo/Hassan Ammar)

Lebanese government, economic and banking officials are considering a $2 billion financing plan aimed at stimulating consumer spending, increasing industrial production and boosting exports by providing equal amounts of credit to individuals and businesses. Under the assumptions outlined in the proposal, the initiative could generate up to $574 million in additional government revenue in its first year, supporting economic activity and growth.

The plan proposes channeling financing through Banque du Liban (BDL), Lebanon's central bank, either by allowing commercial banks to draw down funds they have placed with it or through direct lending from the central bank's liquidity. Commercial banks would then extend the loans to eligible borrowers.

One billion dollars would be allocated to consumer lending, including car loans and personal spending, while the remaining $1 billion would go to businesses, primarily to finance working capital and upgrade industrial machinery. The goal is to increase production, reduce dependence on imports and strengthen exports.

The proposal remains under discussion, with officials working to incorporate feedback and make the necessary improvements before seeking formal approval. It is based on projections of economic and fiscal returns, alongside the potential to stimulate consumption and production simultaneously and support government efforts to restore financial stability.

According to a working paper obtained by Asharq Al-Awsat from a senior official involved in the discussions, the initial, one-time injection of $2 billion is expected to generate approximately $2.95 billion in economic activity.

That would represent around 6.4 percent of gross domestic product (GDP), based on an estimated GDP of $46 billion, or 8 percent using a lower estimate of $36.9 billion, according to the paper, which cites World Bank data.

Financing Mechanism

The official said discussions had reached an advanced stage, with the plan's provisions drafted, its components organized and potential funding sources identified.

The options include allowing banks to withdraw part of their placements at the central bank or providing direct financing from BDL's liquidity. Both would be subject to strict arrangements ensuring that credit is divided equally between households and businesses.

The working paper also envisages recycling the financing as borrowers repay their loans, allowing banks to lend the funds again and sustain the economic impact over time. It estimates that this revolving credit mechanism could generate approximately $3 billion in economic activity annually.

Under the proposed arrangement, the central bank would provide $2 billion to commercial banks through formally recorded transactions, classified either as withdrawals from existing placements or as new lending facilities.

The banks would then extend the funds to businesses and consumers, earning a fixed margin of two percentage points on corporate loans and three percentage points on consumer loans.

The total annual return on the lending portfolio is projected at approximately $50 million in the first year.

The funding, whether provided directly, through withdrawals from banks' placements or via lending facilities administered through the banking system, would come almost exclusively from the central bank's foreign currency reserves, currently estimated at approximately $11.6 billion.

The plan calls for an equal allocation of loans to consumers and businesses, targeting activities that allow repayment over the short and medium term. This would enable the funds to be lent repeatedly in the coming years, increasing liquidity flows throughout the economy.

Beyond its potential near-term multiplier effect and the restoration of a vital banking function, the proposed financing represents a significant structural opportunity for key productive sectors.

Most credit products have been effectively unavailable since Lebanon's financial crisis erupted, leaving banks' placements at the central bank, estimated at approximately $80 billion, tied up.

The same crisis, now approaching the end of its seventh consecutive year, has severely weakened consumers' purchasing power following the collapse of the Lebanese currency and restrictions on deposit withdrawals.

Depending on the applicable BDL circulars and the categories of eligible beneficiaries, depositors can currently withdraw between $500 and $1,000 per month.

The proposal also raises the possibility of allocating part of the initiative's returns to provide additional liquidity through existing mechanisms for repaying bank deposits.

Untapped Investment Opportunities

According to field surveys cited in the proposal, Lebanese industry is currently operating at approximately 50 percent of its installed capacity, pointing to significant untapped investment opportunities that the plan considers capable of generating reliable returns.

The proposal seeks to help close that gap by directing approximately $700 million toward working capital, including raw materials and additional production shifts, while allocating another $300 million to modernize industrial machinery.

Once the financing is fully deployed, the plan projects a substantial and sustained increase in exports of approximately $1.14 billion.

This would represent growth of nearly 38 percent in annual exports of goods and services, compared with their current estimated value of around $3 billion.

The additional financing is also expected to stimulate activity across industrial sectors, diversify products and goods, create jobs and improve workers' incomes.

At the same time, the plan proposes allocating $1 billion to consumer lending, with an initial distribution that remains subject to review and adjustment.

Under the preliminary proposal, up to $400 million would finance car loans repayable over five years, while $600 million would fund personal spending loans with repayment scheduled over one year.

A net interest margin of three percentage points on consumer lending would generate an estimated $30 million in returns, helping sustain and potentially expand the financing program in subsequent years.

Financial modeling suggests that the proposed $2 billion credit package could generate up to $574 million in additional government revenue in its first year by stimulating economic activity.

Value-added tax (VAT) would account for the largest share, generating approximately $310 million, followed by customs duties and excise taxes of at least $135 million.

Income tax revenue is projected at approximately $100 million, while taxes on bank profits could generate between $8 million and $31 million, depending on the lending mechanism ultimately adopted.

From an economic and financial perspective, the corporate lending component alone is projected to contribute more than $1.34 billion annually to Lebanon's balance of payments through increased export earnings and savings on imports.

The initiative would also help raise industrial capacity utilization and modernize factories, strengthening Lebanon's external trade position by revitalizing industrial production and services, expanding exports and replacing imported goods with locally manufactured alternatives.


Bangkok Meetings Highlight Overlapping Shocks to Global Economy

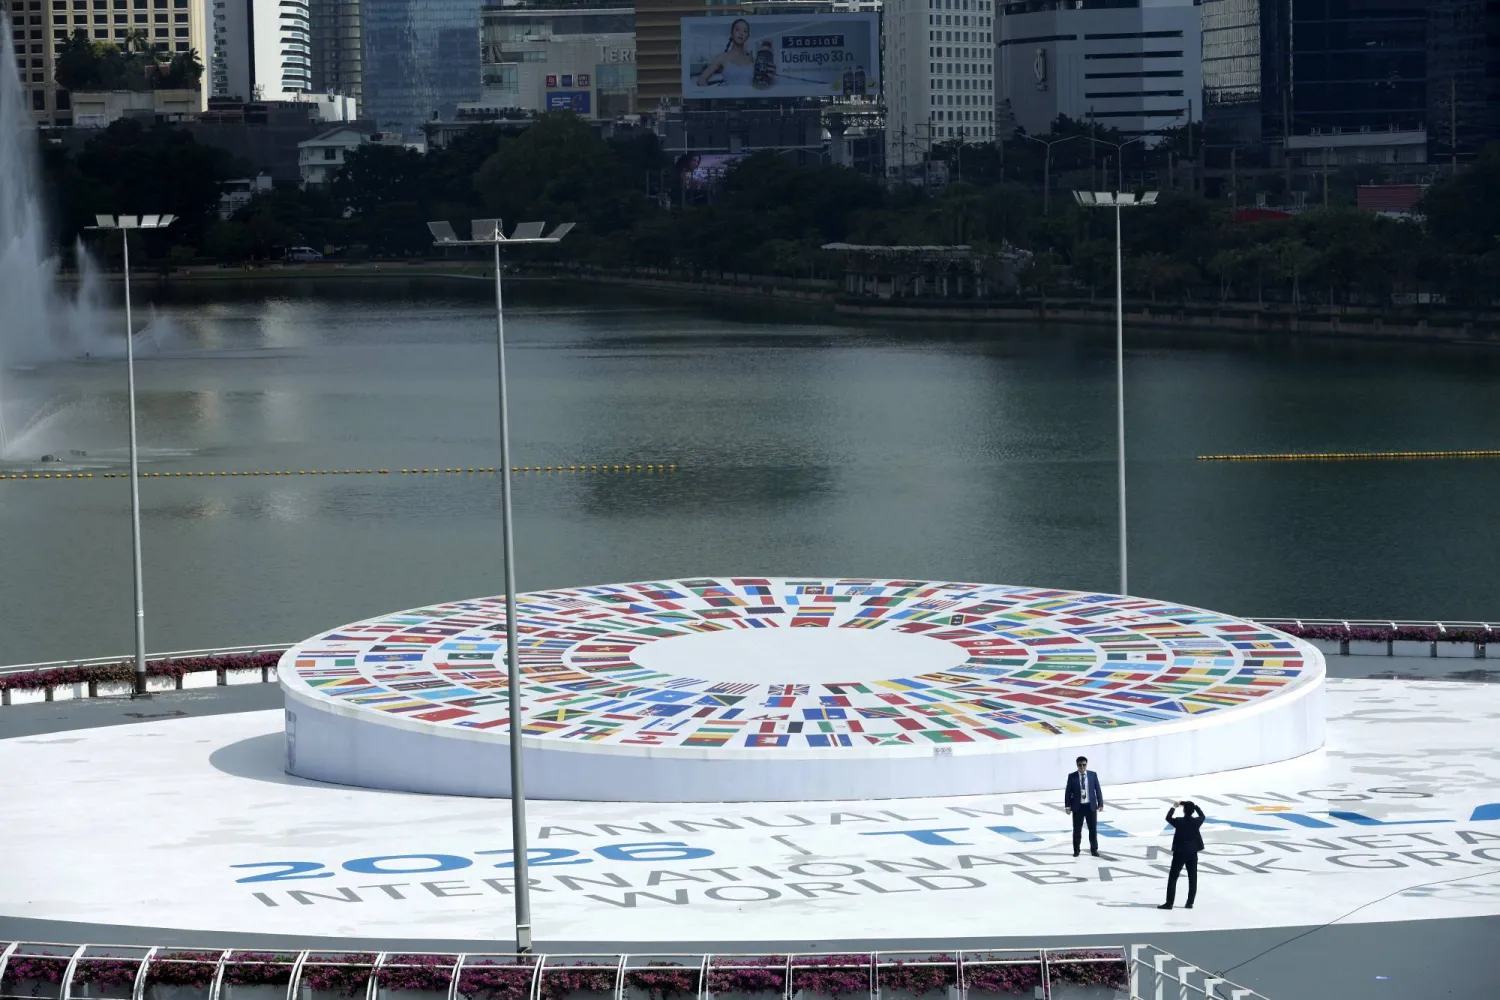
Delegates take photographs with the logo of the 2026 Annual Meetings of the IMF and the World Bank Group in Bangkok, Thailand, 16 October 2026.  EPA/RUNGROJ YONGRIT
Delegates take photographs with the logo of the 2026 Annual Meetings of the IMF and the World Bank Group in Bangkok, Thailand, 16 October 2026. EPA/RUNGROJ YONGRIT
TT

Bangkok Meetings Highlight Overlapping Shocks to Global Economy

Delegates take photographs with the logo of the 2026 Annual Meetings of the IMF and the World Bank Group in Bangkok, Thailand, 16 October 2026.  EPA/RUNGROJ YONGRIT
Delegates take photographs with the logo of the 2026 Annual Meetings of the IMF and the World Bank Group in Bangkok, Thailand, 16 October 2026. EPA/RUNGROJ YONGRIT

The global economy's resilience in the face of repeated shocks is no longer enough to reassure policymakers, as the fallout from wars, disruptions to energy supplies and trade, mounting public debt and rising borrowing costs increasingly overlap. These challenges dominated discussions at the Annual Meetings of the International Monetary Fund (IMF) and World Bank Group in Bangkok, where the International Monetary and Financial Committee (IMFC) warned of threats to energy and food security, mounting pressure on growth and inflation, and governments' diminishing capacity to absorb further shocks.

Asharq Al-Awsat examines the key challenges highlighted during the meetings, from growing debt burdens and shrinking fiscal space to energy and food supply disruptions, the risks associated with artificial intelligence, and the ability of Asian economies to continue driving growth and creating jobs.

IMF Managing Director Kristalina Georgieva summed up these challenges as a balance between "optimism and concern." The resilience of the global economy, opportunities presented by artificial intelligence and the dynamism of Asian economies offer reasons for optimism, while inflation, elevated debt levels, wars and climate risks remain major concerns. She warned that relying on a single growth engine, such as investment in artificial intelligence, leaves economies more vulnerable to volatility.

Throughout the week, finance ministers, central bank governors and international officials gathered in Bangkok to discuss ways to contain inflationary pressures, rebuild fiscal buffers, create jobs and expand the private sector's role in developing economies. The discussions came as tensions in the Middle East continued to drive up energy and transportation costs, placing additional strain on the most vulnerable countries.

Mounting Debt Squeezes Fiscal Space

Rising public debt and debt-servicing costs emerged as major concerns, particularly for low-income economies facing higher borrowing costs, rising food and energy prices, and diminishing resources to finance development spending.

Georgieva said debt-service payments as a share of government revenue in low-income countries had risen from 8 percent to 14 percent in recent years, leaving fewer resources for essential services and investment.

She stressed the IMF's responsibility to help these countries restructure their debt when necessary, mobilize domestic resources, attract international financing and create conditions conducive to private investment.

To address mounting fiscal pressures, the IMF urged governments to reduce deficits, contain debt growth and move away from broad-based cash transfers and subsidies in favor of more targeted assistance for those most affected.

It also emphasized the importance of preserving central bank independence and maintaining interest rates at levels that can contain inflation and prevent price pressures from becoming entrenched.

The risks extend beyond developing economies. Rising bond yields in advanced economies are pushing up borrowing costs and debt-servicing burdens, with implications for global financial conditions and the cost of financing in other countries.

Interconnected Risks

A statement by the International Monetary and Financial Committee, chaired by Saudi Finance Minister Mohammed Aljadaan, brought together the principal risks confronting the global economy, including ongoing conflicts, disruptions to critical waterways and trade routes, and the resulting threats to energy and food security.

The Committee stressed that the global economy's ability to adapt does not eliminate the risks clouding the growth outlook, particularly amid elevated debt levels, higher borrowing costs and growing pressure on low-income and fragile economies.

These risks intersect with the challenges posed by artificial intelligence, which offers opportunities to boost productivity but also raises concerns about widening disparities between economies and the emergence of new financial vulnerabilities.

Against this backdrop, policymakers face growing pressure to pursue economic policies that reinforce stability and rebuild fiscal buffers, alongside broader international cooperation to address cross-border shocks and support the countries most exposed to them.

Energy, Food and Middle East Shocks

The conflict in the Middle East brought energy and food security, along with trade disruptions, to the forefront of the risks discussed in Bangkok.

Its repercussions have spread to transportation, insurance and production costs, fueling inflationary pressures and imposing additional burdens on energy-importing countries, particularly those with limited fiscal resources.

The impact varies across the region depending on countries' fiscal positions, their reliance on energy and food imports, and their ability to absorb rising costs and supply disruptions.

Conversely, higher oil prices do not necessarily improve conditions for every oil-exporting country. The overall impact depends on production and export volumes, import costs, public spending and how long the disruptions persist.

These risks have taken on added significance amid IMF warnings about the war's implications for growth, including its forecast that the economies of the Middle East and Central Asia will contract in 2026 before recovering the following year.

Supply disruptions are also interacting with volatile food prices and climate-related challenges. At the same time, rising public debt and borrowing costs are narrowing governments' room for maneuver, making it increasingly difficult to balance inflation control, protection of vulnerable populations and spending that supports economic growth.

These pressures underscore the importance of securing waterways and trade routes, pursuing greater fiscal discipline, directing assistance toward those who need it most and investing in measures that safeguard productive capacity over the long term.

Together, these developments capture the central warning to emerge from the meetings: simultaneous shocks are testing economic resilience, making stronger fiscal buffers, diversified sources of growth, expanded employment opportunities and international cooperation essential to limiting the fallout from crises that cross national borders.

Artificial Intelligence: A Growth Engine and a Source of Risk

Artificial intelligence featured prominently in the Bangkok discussions as its influence on trade, investment and productivity expands, raising questions about whether its expected benefits can translate into broader and more sustainable economic growth.

Participants noted that investment in AI-related goods has become a significant driver of global trade.

According to figures presented by the IMF during the meetings, cumulative global trade grew by 8.3 percent between 2023 and 2025, compared with a 29 percent increase in trade in AI-related goods.

The Fund estimated that global trade growth would have been limited to 4.6 percent if those goods were excluded.

However, the broader productivity gains remain uncertain, with much of the investment and market valuations concentrated in a relatively small number of companies.

The rapid pace of technological development is also raising concerns about financial stability, cybersecurity and how the benefits of growth and employment opportunities will be distributed.

International institutions increasingly view artificial intelligence as a force reshaping jobs and the skills required to perform them, rather than one that will necessarily lead to widespread job losses.

This highlights the importance of improving education and training, reskilling workers and enabling small and medium-sized enterprises to adopt new technologies, ensuring that the benefits are not confined to the most advanced economies and largest companies.

Asia Remains a Key Driver of Global Growth

At the regional level, discussions underscored Asia's growing importance in the global economy, supported by trade, technology investment and expanding commercial ties among developing economies.

According to IMF figures, Asian economies accounted for approximately 68 percent of global economic growth in 2026.

The Fund also highlighted structural shifts in international trade, including the growing share of developing economies and increasing trade among them.

Nevertheless, the region faces risks stemming from several economies' dependence on energy imports, the repercussions of the Middle East conflict, trade tensions and tariffs.

Discussions emphasized the need to accelerate regional economic integration, remove non-tariff trade barriers and strengthen supply chains and digital infrastructure.

Jobs, Poverty and Development Financing

Job creation and mobilizing development financing formed another major focus of the meetings, amid projections that approximately 1.2 billion young people in emerging economies will reach working age over the coming years, while the capacity to generate new jobs remains limited.

The World Bank emphasized the private sector's role in creating employment and the need to expand small and medium-sized enterprises' access to financing, markets and technology.

It also stressed that reducing poverty requires sustainable economic opportunities rather than reliance on financial assistance alone, particularly as government budgets and development aid come under mounting pressure.

These challenges are especially acute in low-income and conflict-affected countries, which simultaneously face rising costs for basic necessities, limited access to financing and shrinking fiscal space.

The IMF called for more coordinated support for these economies, including debt relief and restructuring measures where needed, stronger domestic resource mobilization and greater access to international financing.

Ultimately, the Bangkok meetings made clear that the challenge facing the global economy is no longer simply containing one economic shock at a time. Policymakers must now contend with overlapping crises that constrain fiscal and monetary policy choices and make it increasingly difficult to sustain growth and create jobs.

Between the opportunities offered by artificial intelligence and the risks posed by geopolitical tensions and mounting debt, the global economy's ability to navigate the next phase will depend on diversifying growth engines, strengthening financial stability and ensuring that economic gains reach a broader share of the population.

And with countries differing widely in their ability to absorb shocks, international cooperation and access to financing for the most vulnerable economies will remain essential to preventing economic disparities from widening further.