

Economic strength is no longer measured solely by GDP growth rates, the size of foreign reserves, or the ability to attract investment during prosperous times. In a world increasingly exposed to successive shocks, ranging from wars and disruptions in energy and trade to pandemics and financial market crises, another equally important standard has emerged: an economy’s ability to withstand changing circumstances, continue functioning during a crisis, and subsequently recover and adapt.
As a result, the concept of economic resilience has gained growing prominence in global economic debates. A resilient economy is not one that remains unaffected by crises, but rather one that can mitigate their impact, preserve its core functions, and return to a growth path more quickly, while maintaining the capacity to adapt if shocks persist or evolve.
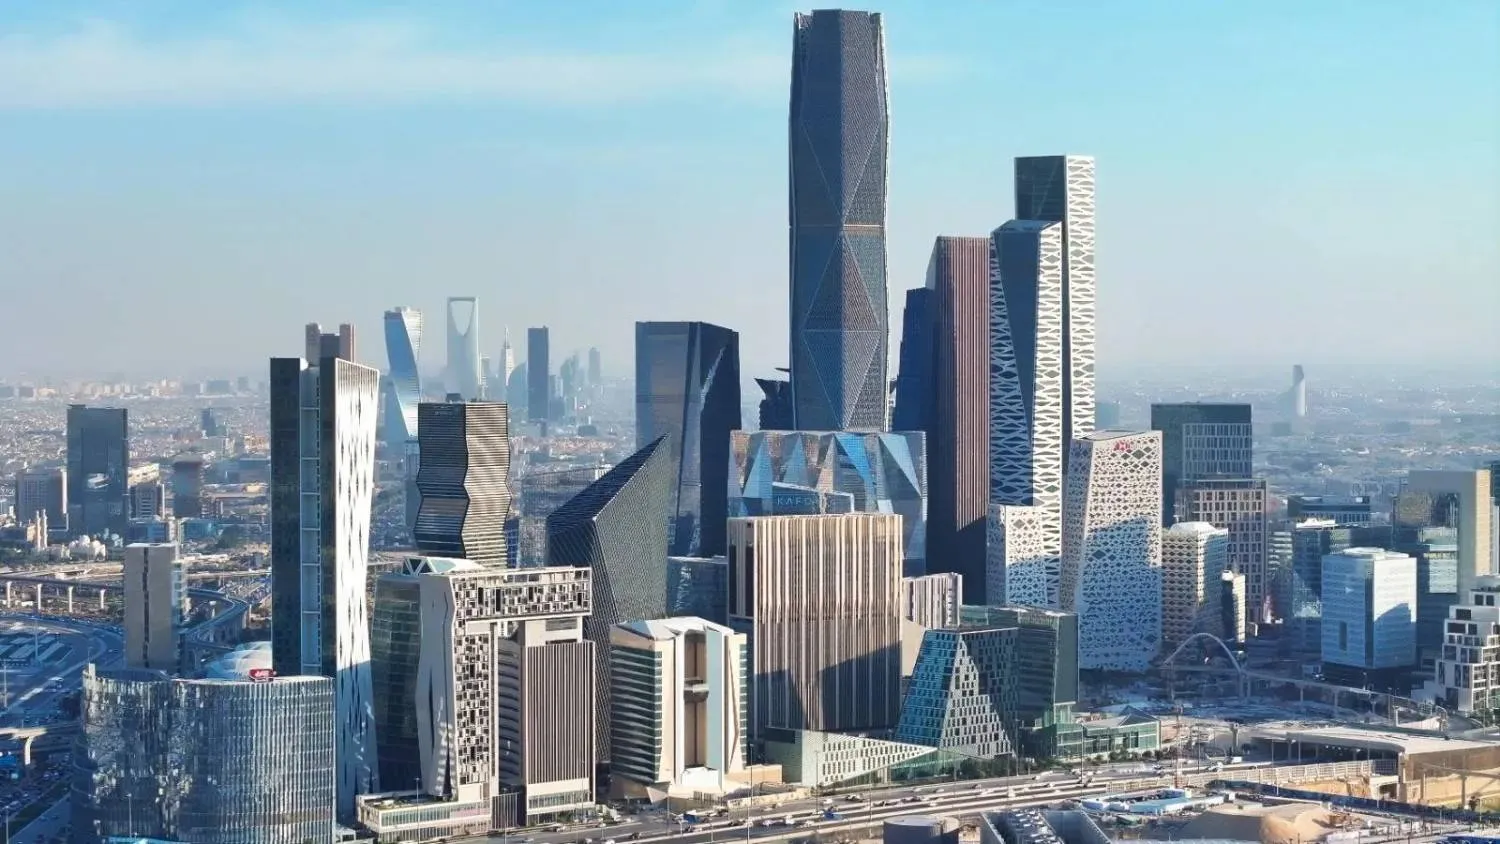
This issue is particularly significant for Gulf economies, especially Saudi Arabia, which has undergone substantial transformations over the past decade in its economic structure, sources of revenue, investment patterns, and trade, while simultaneously building fiscal and institutional buffers to deal with crises.
In this context, the International Monetary Fund (IMF) views resilience as an economy’s ability to absorb shocks, adapt to them, and recover rapidly while maintaining economic and financial stability. This capability depends not only on the availability of resources but also on sufficient room for fiscal and monetary policies to respond, strong institutional frameworks capable of managing crises, and structural fundamentals that enable the economy to adjust to long-term changes.
The Bank for International Settlements (BIS) adds another dimension to the concept by emphasizing the importance of limiting the buildup of financial imbalances before shocks occur. Resilience is not only about how an economy reacts during a crisis but also about the policies that reduce vulnerabilities and prevent shocks from having more severe consequences. From this perspective, prudential, monetary, and fiscal policies work together to strengthen an economy’s ability to navigate cycles of financial booms and downturns.
This discussion coincides with the IMF’s upcoming World Economic Outlook report, titled “Resilience under Strain, Urgent Choices,” scheduled for release on October 13 during the IMF and World Bank annual meetings in Bangkok. The report comes at a time when the global economy faces overlapping shocks, from energy and trade disruptions to geopolitical tensions.
In its latest briefing, the IMF noted that the global economy has demonstrated resilience despite continuing war-related disruptions, although countries differ significantly in their ability to absorb and adapt to these consequences.
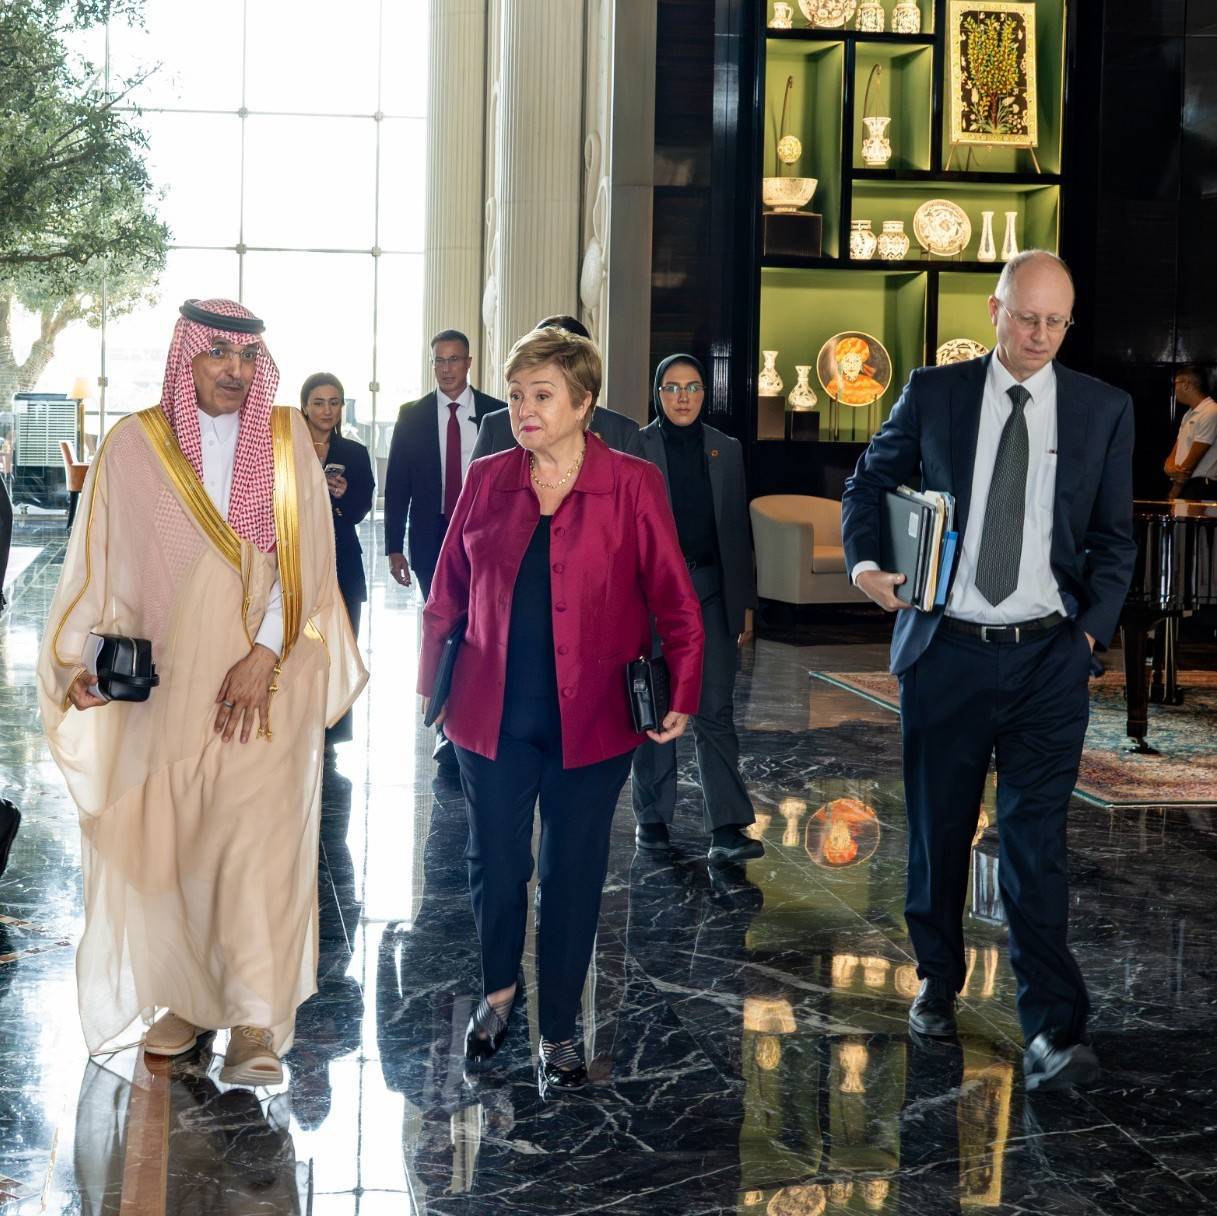
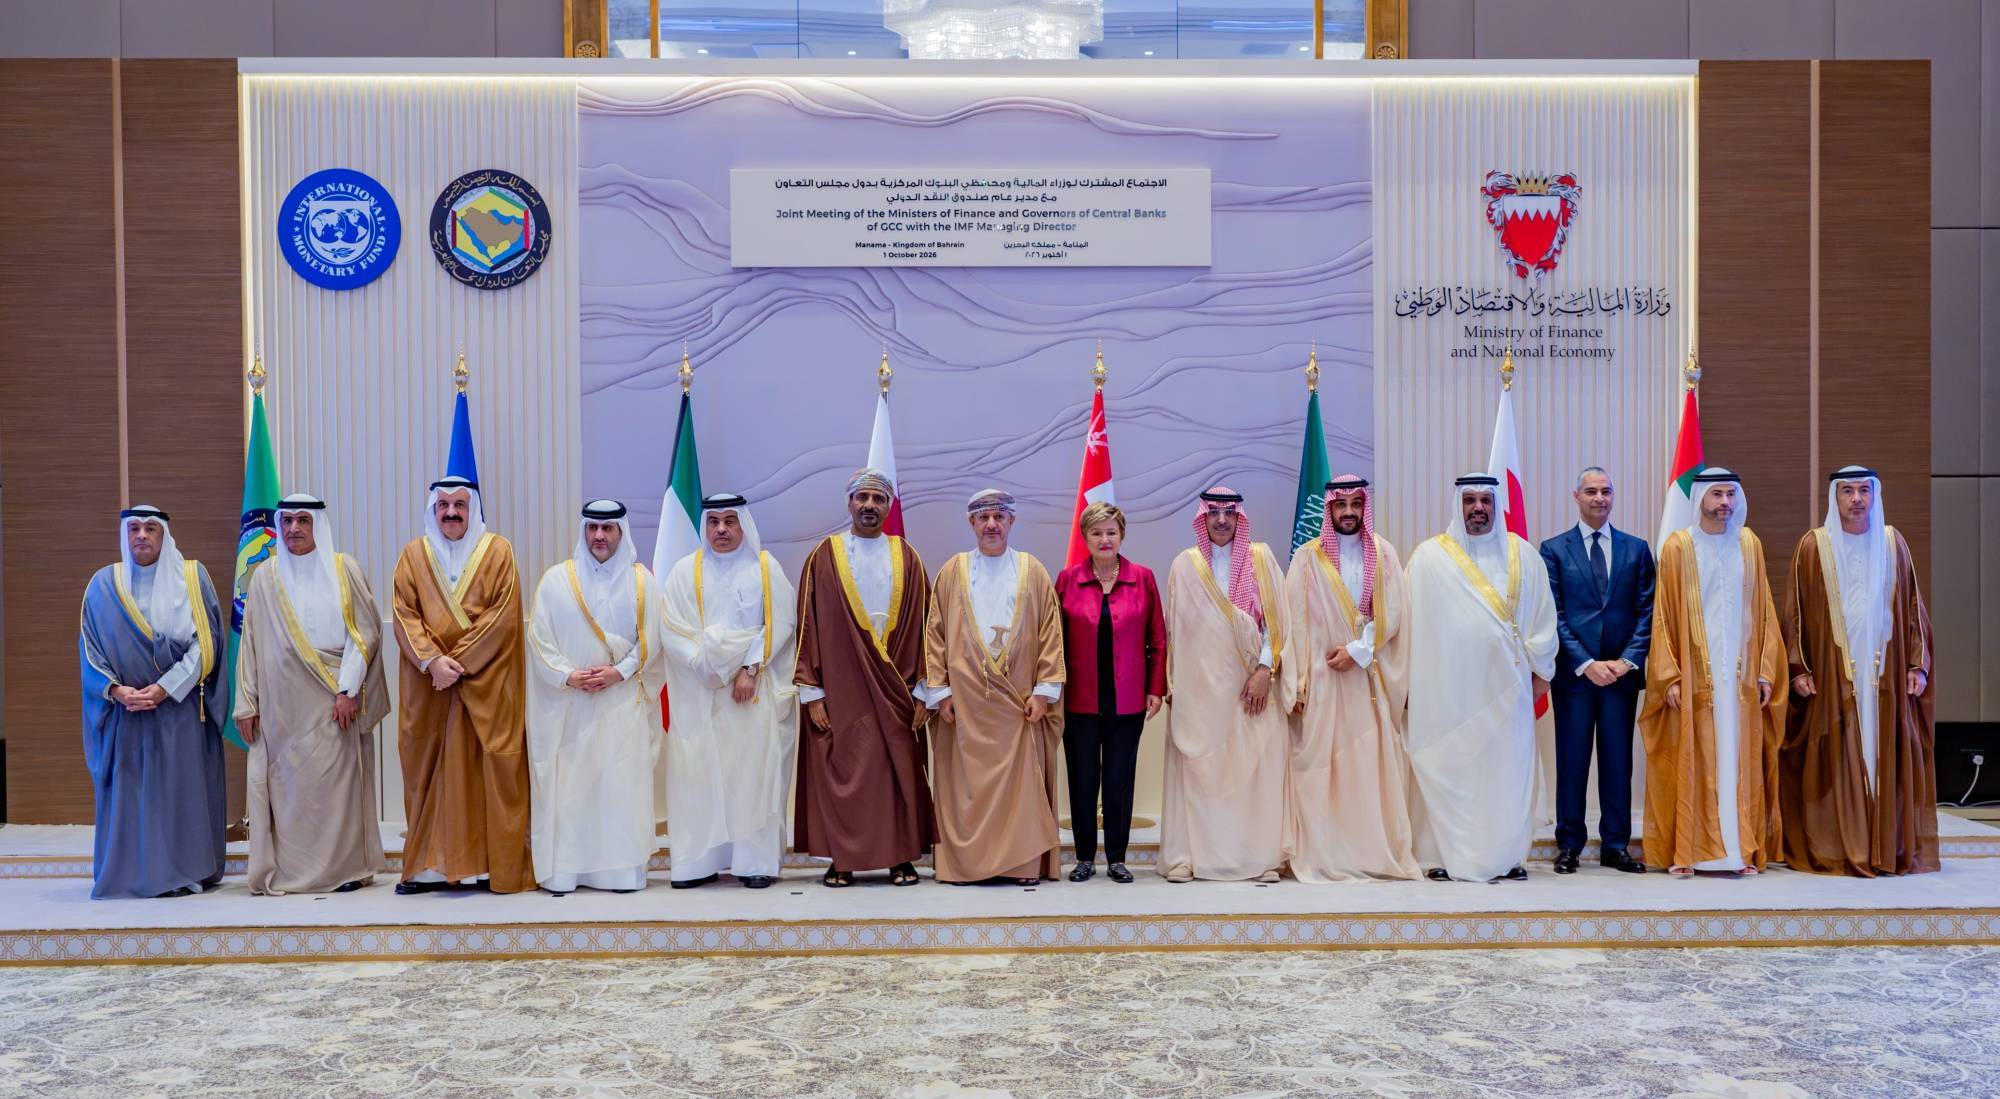
IMF Managing Director Kristalina Georgieva praised the resilience of Gulf Cooperation Council (GCC) economies and their ability to contain the spillovers of regional conflicts. She noted that this resilience is rooted in strong fiscal and economic foundations, ample fiscal and external buffers, a robust banking sector, and strategic investments in energy, logistics, and economic diversification.
This raises a practical question: What makes one economy more capable than another of absorbing shocks and recovering from them? Are financial reserves alone sufficient, or does resilience also require diversified sources of growth, revenue, and trade; deeper financial markets; infrastructure that provides alternatives; and institutions capable of responding rapidly and effectively?
According to Tim Callen, former head of the IMF mission to Saudi Arabia and visiting fellow at the Arab Gulf States Institute in Washington, economic resilience reflects an economy’s ability to endure a negative shock with minimal disruption to domestic activity. Measuring resilience, he says, involves not only assessing the initial damage but also evaluating the speed of recovery.
Callen argues that comparing economies exposed to the same shock offers a practical way to assess resilience. The issue is not merely the extent of the initial damage, but also how quickly and strongly economic activity rebounds. The smaller the initial impact and the faster the recovery, the greater the economy’s resilience.
Resilience Goes Beyond Financial Reserves
Callen stresses that resilience cannot be reduced to the size of reserves or the strength of public finances, despite the importance of having fiscal space and adequate foreign-exchange reserves to absorb shocks. A truly resilient economy combines these buffers with greater diversification in production and exports, a broader range of trading partners, and alternative transportation and export routes.
He warns that heavy reliance on a single export product, one trading partner, or a single route for transporting goods and energy makes an economy more vulnerable when external shocks occur. He also highlights the role of effective policymaking and governance, noting that a country's ability to translate financial resources into a rapid and effective response depends on institutional quality, the speed of decision-making, and the capacity to reallocate resources as circumstances change.
From this perspective, fiscal buffers are only one component of resilience rather than a substitute for it. They give governments room to act and support economic activity during difficult periods, but their effectiveness is significantly enhanced when accompanied by diversified sources of growth, trade, and transportation.
When Alternatives Are Put to the Test
This aspect of resilience is especially evident in Saudi Arabia’s energy sector, where the importance of having multiple export routes becomes clear whenever traditional shipping channels are disrupted.
Callen says the attacks targeting the East-West Pipeline highlighted the value of the alternatives Saudi Arabia has developed over recent years. The pipeline, which transports oil from production areas in eastern Saudi Arabia to Yanbu on the Red Sea coast, provides an additional export route and reduces reliance on maritime shipping lanes.
However, these alternatives are facing a new test amid continuing risks to navigation in the Red Sea and the Bab al-Mandab Strait, alongside developments in the Strait of Hormuz. Callen notes that the extent to which these alternatives can mitigate disruptions depends on the scale of the damage and how long it lasts, adding that the situation has become "more challenging than it was a month ago."
Nevertheless, he believes that the existence of alternative routes remains a critical factor in an economy’s ability to deal with shocks, as it allows trade and energy flows to be redirected and adjusted in response to evolving circumstances, rather than being dependent on a single route.
Saudi Arabia: A Transformation in Response Capability
Callen does not believe that Saudi Arabia’s improved resilience is solely the result of changes in the structure of the economy or the growing contribution of non-oil sectors. In his view, the most significant transformation in recent years has been the improvement in policy-making quality and the speed of response, together with the development of institutions and tools better equipped to manage crises.
He points out that this progress became particularly evident during the COVID-19 pandemic, when the government was compelled to make rapid decisions and address a large-scale shock within a short period. According to Callen, that experience demonstrated how the ability of institutions to respond and adapt can be a crucial element of economic resilience, even before structural transformations are fully realized.
He also believes that advances in debt and financing management have expanded the government's room for maneuver. He highlights the role of the National Debt Management Center in building greater expertise in international debt markets, thereby providing broader financing options, whether through borrowing, the use of assets, or a combination of different instruments depending on the nature of the shock and the economy’s needs.
Shock Testing: From Absorption to Recovery
Dr. Ahmed bin Nasser Al-Rajhi, Vice Chairman of the Saudi Economic Association, views economic resilience as a multi-stage capability that begins with anticipating a shock, then absorbing its initial impact, recovering from it, adapting to its consequences, and ultimately redirecting the economy toward a new growth path.
From this perspective, he argues that economic strength should not be measured solely by the size of financial resources, but by the ability to use those resources effectively while diversifying sources of growth, production, and financing.
Al-Rajhi believes that Saudi Arabia’s experience in recent years provides practical evidence of improvements in this capability, citing the continued growth of the non-oil sector during periods of declining oil prices and its ability to keep expanding even in years when the oil sector experienced slower growth.
He notes that the non-oil sector grew by around 5 percent between 2016 and 2019, despite lower oil prices, and maintained growth of approximately 5 percent between 2022 and 2025, despite weak growth in the oil sector. In his view, these developments reflect the increasing independence of non-oil growth drivers and the declining share of the oil sector in GDP to around 20 percent.
Al-Rajhi adds that foreign investment inflows have become another important factor in broadening the base of economic activity. He points to Ministry of Investment data showing a fivefold increase in investment inflows, accompanied by a significant rise in the number of foreign companies operating in the Kingdom, boosting foreign direct investment.
Latest data from the General Authority for Statistics also show that net foreign direct investment inflows into Saudi Arabia reached SAR19.1 billion during the second quarter of 2026. Al-Rajhi says that achieving this level of inflows despite the geopolitical challenges facing the region reflects the economy’s continued ability to attract foreign capital, as well as the expanding base of companies and business activities operating in the Kingdom.
COVID-19: An Early Test of Resilience
Al-Rajhi also cites the COVID-19 pandemic as a real-world test of the economy’s ability to absorb a large and sudden shock. Following the sharp contraction caused by lockdown measures, economic activity returned to growth at a rapid pace, increasingly driven by private-sector demand and investment rather than solely by government spending or improvements in oil revenues.
He argues that the speed of the recovery, particularly in non-oil activities, reflects a change in the nature of the Saudi economy compared with earlier periods, when declines in oil prices were transmitted more directly to other components of economic activity. From this perspective, the growth of non-oil sectors has become, in his view, a tool for resilience rather than merely a diversification objective.
Al-Rajhi stresses that this resilience does not mean the economy has become immune to shocks. Supply-chain disruptions, rising shipping and energy costs, and geopolitical tensions can still affect the economy through inflation, financing costs, and trade. However, the Kingdom’s strategic logistics position, combined with the experience it has accumulated in crisis management, provides additional capacity to adapt to such shocks.
Fiscal Buffers: Room to Maneuver
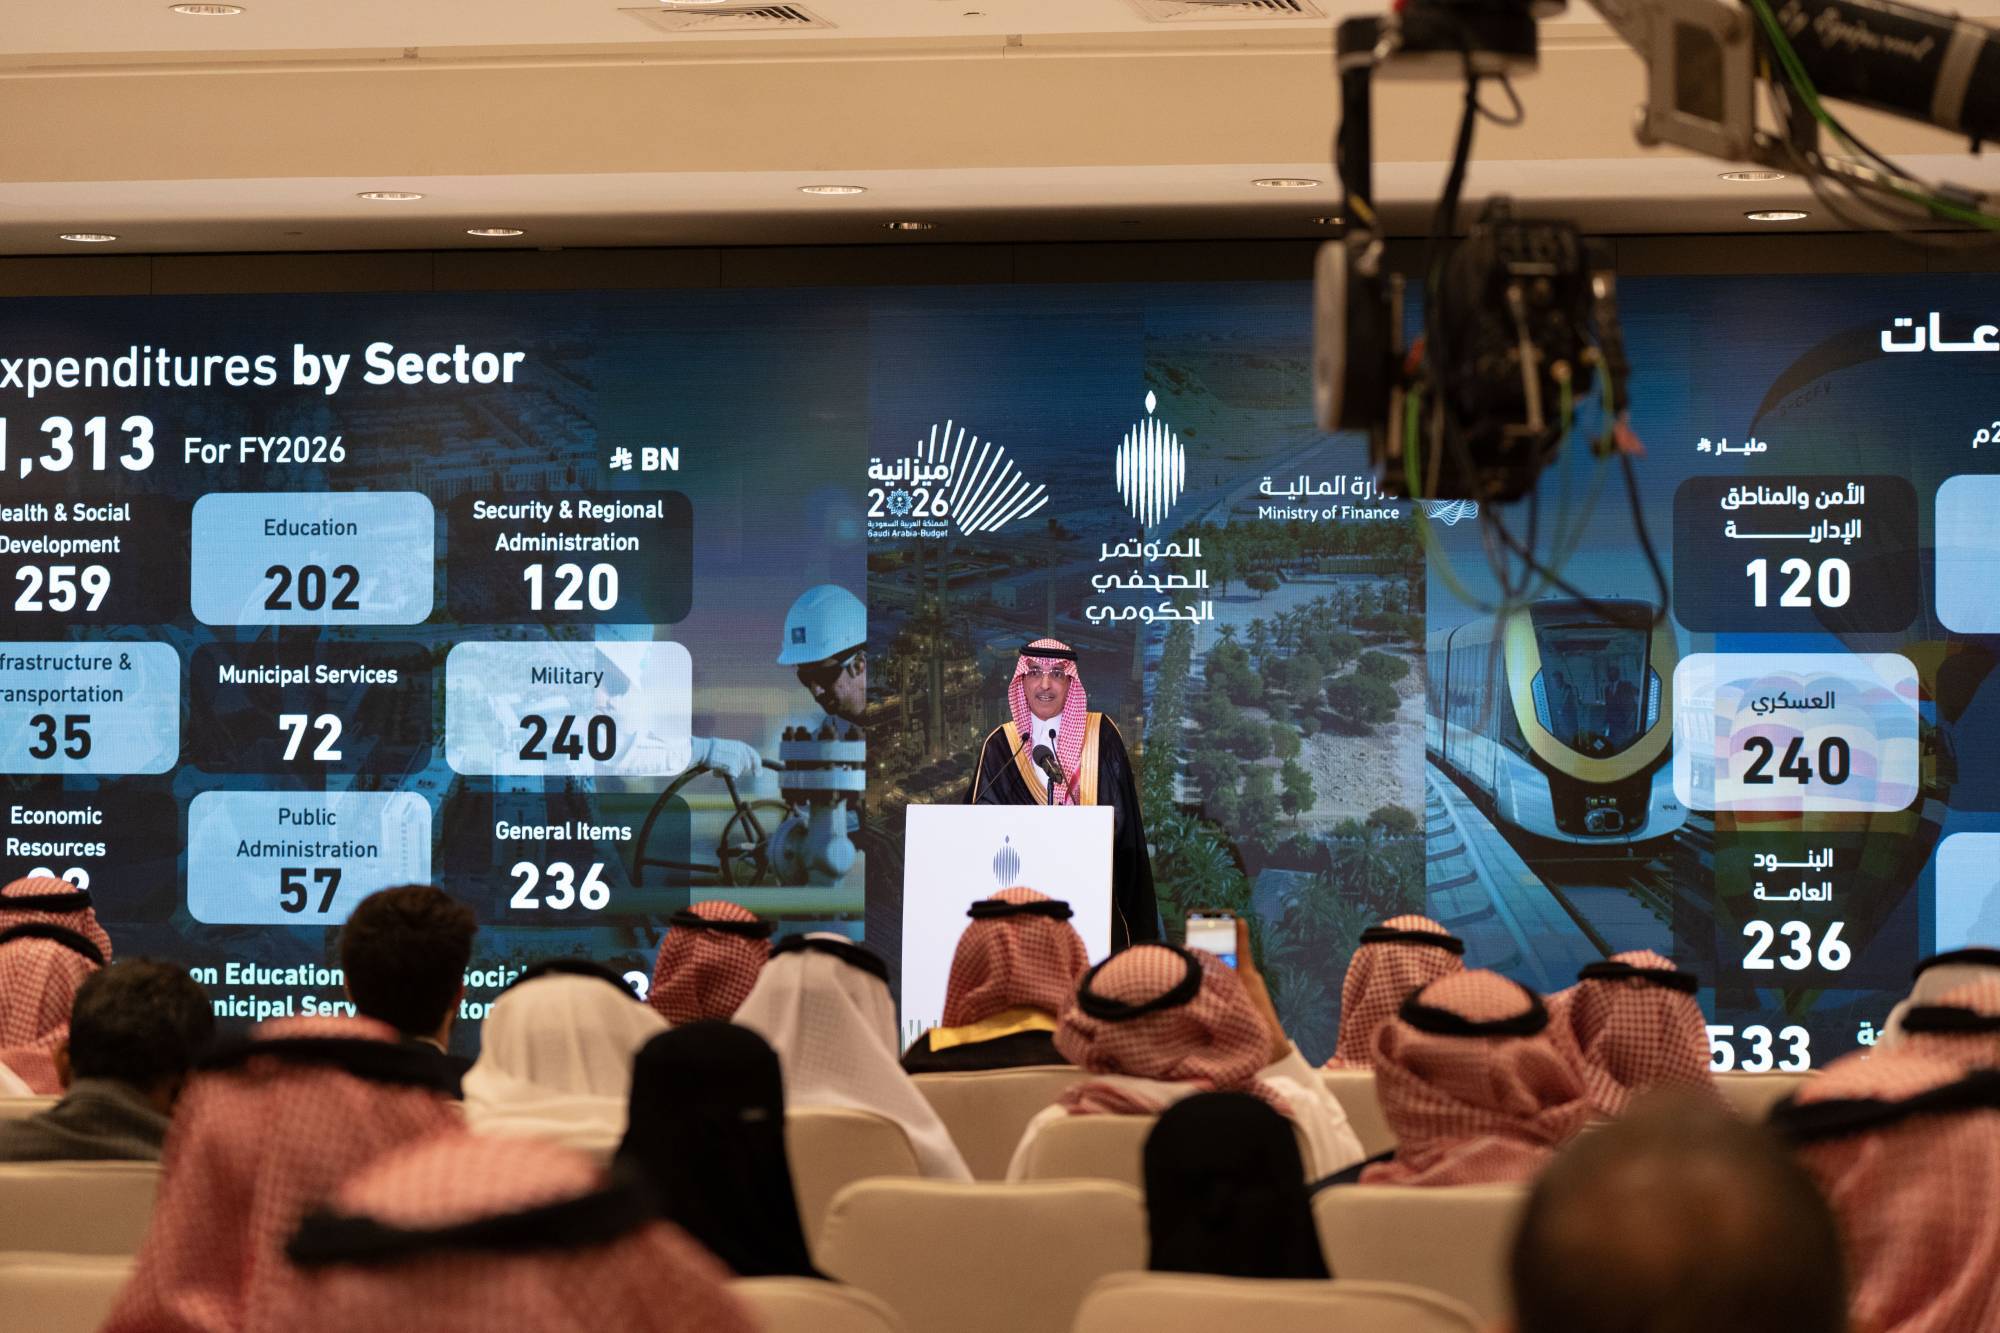
On the financial front, Al-Rajhi believes that government reserves and assets, together with the strength of the banking sector, provide an important cushion against external shocks. According to data from the Saudi Central Bank (SAMA), the Kingdom’s reserve assets stood at $487.3 billion at the end of August 2026, while the banking sector maintains high levels of capital and liquidity and continues to benefit from deposit growth, supporting its ability to finance the economy during periods of disruption.
However, these buffers are not unlimited. Rising government borrowing alongside growing corporate financing needs could increase pressure on domestic liquidity, particularly in a high-interest-rate environment. Al-Rajhi argues that reducing reliance on domestic financing while making greater use of international markets could ease liquidity pressures and create more room for financing the private sector, particularly small and medium-sized enterprises (SMEs).
Financing Costs: A New Test of Resilience
Financing costs are emerging as one of the next major tests of resilience, especially given the riyal’s peg to the US dollar and the transmission of US interest rate changes into the local market.
Al-Rajhi notes that higher financing costs may affect investment and spending decisions, but the extent of the impact varies according to financing structures. Fixed-rate loans, for example, are not affected in the same way as new borrowing or variable-rate financing facilities.
Accordingly, he argues that debt management strategies should emphasize diversification of funding sources, alignment of debt maturities with cash flows, and prioritization of projects according to their economic returns. He also suggests reducing the relative dependence on domestic financing as one option that could provide greater access to credit for the private sector, particularly SMEs.
Logistics Alternatives: A Key Component of Resilience
Al-Rajhi does not limit resilience to public finances or the performance of the non-oil economy. He also links it to the Kingdom’s ability to maintain the flow of trade and energy during periods of disruption.
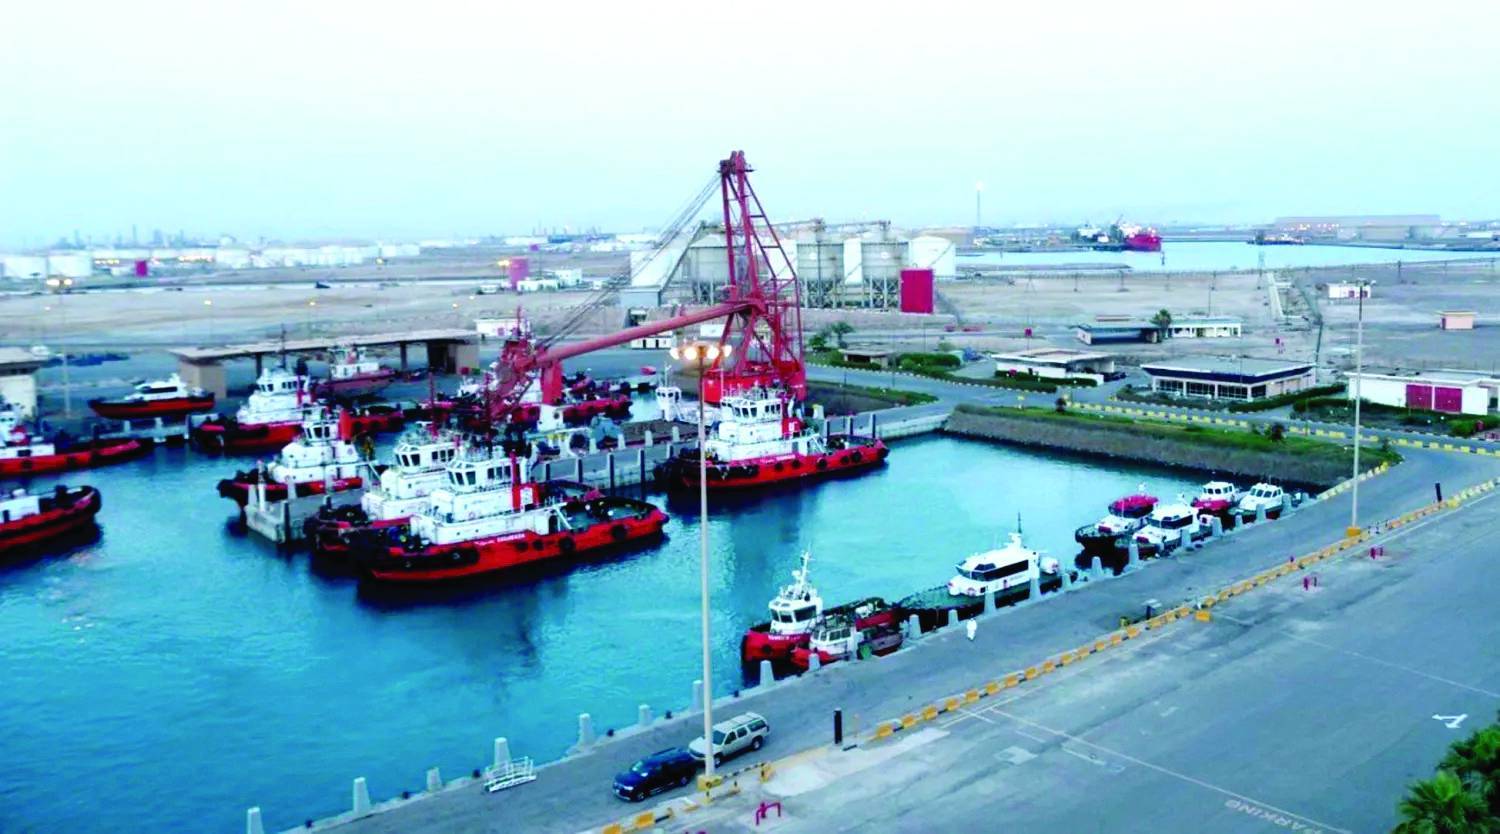
He believes recent geopolitical developments underscore the importance of diversifying oil export outlets and investing in infrastructure that provides alternatives to traditional transport routes. He points to the East-West Pipeline and the need for additional logistics options, as well as a more integrated railway network connecting different regions of the Kingdom.
In his view, investment in such infrastructure serves not only the energy sector but also reduces reliance on a limited number of trade and transportation routes, enhancing the economy’s capacity to adapt to disruptions. Infrastructure itself, therefore, becomes an element of economic resilience.
Yet Al-Rajhi argues that the most important indicator in the years ahead will not simply be the reduced sensitivity of growth to oil prices, but the economy’s ability to build a broader productive base founded on human capital.
He places investment in education and youth development at the center of this equation, noting that a growing working-age population and an expanding middle class can support domestic demand and broaden investment opportunities in services and value-added industries.
Al-Rajhi further argues that Saudi Arabia’s attractiveness to foreign investors represents another factor expanding the economy’s activity base. He points to Ministry of Investment data showing that foreign investment inflows have increased fivefold, alongside a substantial rise in the number of foreign companies operating in the Kingdom, boosting the stock of foreign direct investment.
Recent data from the General Authority for Statistics show that net FDI inflows reached SAR19.1 billion in the second quarter of 2026. According to Al-Rajhi, achieving this level of inflows despite ongoing geopolitical tensions in the region demonstrates the economy’s continued ability to attract foreign capital and reflects the expansion of the Kingdom’s corporate and business landscape.
Diversification: From a Growth Driver to a Resilience Tool
This perspective aligns with the views of Dr. Abdullah Almeer, Assistant Professor of Economics at King Fahd University of Petroleum and Minerals, who argues that economic resilience rests on a combination of structural diversification, fiscal buffers, deep local financial markets, human and institutional capital, and diversified trade and investment partnerships.
Almeer believes these elements work together to reduce dependence on any single source of income, financing, or trade. Deep domestic financial markets, for example, provide companies and the broader economy with additional funding channels when external capital flows weaken. At the same time, a broader base of economic sectors and activities helps distribute the effects of shocks rather than concentrating them in one sector.
He maintains that GDP growth rates and debt levels alone are insufficient measures of economic resilience. Other important indicators include the contribution of the non-oil sector to growth, the ability of revenues to cover debt-servicing obligations, the distribution of debt maturities, import-cover ratios, net foreign assets, and the share of non-oil revenues in total government revenues.
According to Almeer, the picture also includes indicators related to the depth of the financial system and labor market, such as the volume of domestic credit relative to GDP and the economy’s ability to generate jobs outside the public sector. The broader the base of economic activity, financing sources, and employment opportunities, the more capable the economy becomes of absorbing shocks without their effects rapidly spreading to other sectors.
Resilience and the Cost of Financing
The importance of resilience extends beyond managing crises themselves; it also shapes how investors and lenders view an economy. Almeer notes that strong economic fundamentals and a country's ability to cope with shocks can influence sovereign risk assessments and financing costs. They can also support both foreign and domestic investment flows and contribute to the deepening of financial markets.
Investors do not look solely at the size of a shock. They also assess an economy’s ability to finance its needs, maintain liquidity, sustain economic activity, and return to a growth trajectory once the shock subsides.
The Gulf and Saudi Arabia: Broadening the Growth Base
This aspect is particularly important in Gulf economies, where public finances and economic activity have historically been closely linked to energy price cycles. Almeer says that diversification is no longer merely about boosting growth rates or creating new sectors; it has become an integral part of risk management and the promotion of long-term economic sustainability.
This includes diversifying sources of revenue and exports, developing new sectors such as technology, artificial intelligence, mining, tourism, financial services, and the digital economy, while also expanding the role of the private sector and foreign investment. The broader this economic base becomes, the more widely the effects of shocks are distributed, rather than being concentrated in a single sector or source of income.
In Saudi Arabia, this transformation is evident in the expanding base of non-oil economic activity and the growing role of private and foreign investment. Almeer believes that diversifying trade and investment partnerships adds another dimension by expanding markets and sources of investment while reducing reliance on a limited number of partners. This becomes especially important during periods of global trade disruption and rising transportation and insurance costs.
Fiscal Resilience and the Challenge After the Crisis
However, possessing fiscal buffers does not mean exhausting them every time a shock occurs.
On this point, Callen notes that governments may need to increase spending or draw on part of their assets during crises to mitigate disruptions and maintain economic activity. The real challenge, however, comes after the crisis has passed, when those buffers need to be rebuilt.
An economy that depletes a significant portion of its fiscal capacity in response to a single shock becomes more vulnerable to subsequent shocks if it does not gradually restore its safety margins. Fiscal resilience, therefore, is not only about having the resources needed to weather a crisis, but also about preserving and replenishing those resources in preparation for future challenges.
From Response to Preparedness
This places economic resilience within a broader framework than simply reacting to crises. Financial reserves, funding markets, diversified production and export bases, multiple transport and export routes, and efficient institutions are not separate tools; rather, they are interconnected elements that collectively strengthen an economy’s ability to withstand shocks.
In the Saudi case, recent developments have highlighted the importance of this integration. Fiscal buffers provide room for maneuver, economic diversification broadens the base of activity, alternative export routes offer additional options for the energy sector, and the efficiency of institutions and speed of decision-making determine how effectively these tools can be deployed when circumstances change.
Yet the nature of risks is itself evolving, making the process of building adaptability a continuous effort rather than a response to any single shock. Consequently, resilience is measured not only by an economy’s ability to weather crises, but also by its capacity to preserve the foundations of growth and stability, and to continuously strengthen its tools and safety buffers in line with changing risks.