Saudi Arabia Records Highest Growth Levels among the G20 Countries

Flags of the G20 countries (Asharq Al-Awsat)
TT

Saudi Arabia Records Highest Growth Levels among the G20 Countries

Flags of the G20 countries (Asharq Al-Awsat)

The IHS Markit Index predicted that the Saudi Arabian economy will record the highest growth levels among the G20 countries in the fourth quarter of 2021, a wide gap of about 4.5 percent from its closest competitor, Italy.

The achievement reflects the efficiency of the economic reforms taken by the Kingdom since the launch of its Vision 2030.

The positive figures come in light of the unlimited support and direct supervision of Crown Prince Mohammad bin Salman, who is also chairman of the Council of Economic and Development Affairs, demonstrating the strength and efficiency of the economic reforms undertaken by the Kingdom since 2016.

The reforms had a significant impact on overcoming the consequences of the COVID-19 pandemic with minimal damage despite sharp declines in oil prices.

The high levels of growth of the Saudi economy come when many countries, including major economies, are still struggling to overcome the repercussions of the pandemic, which are no less than the effects of World War II.

Saudi Arabia's success in achieving great economic growth rates, outperforming G20 countries, is primarily due to the economic plan of Crown Prince Mohammed. It had a significant role in overcoming global challenges, namely the coronavirus pandemic and the decline in oil prices.

The Saudi GDP growth rate reached 7 percent in the third quarter of 2021, the highest annual growth rate since 2012.

It reflects the Kingdom's economic potentials for rapid recovery from the effects of the pandemic and the resumption of economic activities, benefiting from the exceptional efforts adopted by the government while tackling the challenges of the pandemic and the stimulus measures provided for the national economy.

The economic reforms implemented over the past five years by Saudi Arabia played a prominent role in economic diversification efforts.

The COVID-19 pandemic left a significant economic impact on various vital sectors, especially employment.

The results achieved by the Saudi economy were in contrast to that wave, as the pace of Saudi employment in the private sector hit its highest quarterly level ever, according to administrative records, reaching 90,000 during the fourth quarter of 2021.

As a result of the effectiveness of the Kingdom's government policies in creating jobs for Saudis in the private sector, the number of Saudi workers in the private sector exceeded, for the first time, 1.9 million in December 2021.

Meanwhile, the rate of women's participation in the labor market continued to increase, bypassing the 2030 target as it reached 34.1 percent in the third quarter of 2021 due to the Kingdom's social and economic reforms.

The structural reforms witnessed by the Saudi economy and its main drivers, including a legislative environment and an improvement in the contractual environment, contributed to strengthening efforts to diversify the economy and accommodate tens of thousands of job seekers of both sexes.

As a culmination of the Kingdom's efforts to diversify the economy and reduce dependence on oil, non-oil exports amounted to $53 billion by the end of the third quarter of 2021, an increase of 33 percent compared to the previous year.

Saudi Arabia was one of the best performing global economies during the pandemic where the decline in the GDP was minimal, with the Kingdom ranking sixth among the G20 countries when considering the non-oil activities as a determinant of economic performance in the Kingdom.

Economic observers and analysts expect the Saudi economy to continue to prosper, citing the budget surpluses for the first time since 2014, in addition to the expansion in the implementation of ambitious transformation plans and programs beyond 2022.

The economic boom and diversification of the economy will be achieved through several elements that will pump more than $320 billion by 2030.

Meanwhile, the ambitious strategy announced by the Crown Prince to stimulate the Saudi economy by pumping more than $320 billion until 2030, whether through a partner program, sovereign fund investments, or the national investment strategy, will have a considerable impact.

It will increase the competitiveness of the Saudi economy, placing it on top of the most important economies in the region and the most significant economies in the world.


Gold Rises, but on Track for Weekly Loss as Fed Rate Hike Expectations Build

FILE PHOTO: A raw gold bar is displayed at Nigeria’s booth at the 8th China International Import Expo (CIIE) venue in Shanghai, China, November 5, 2025. REUTERS/Maxim Shemetov/File Photo
TT

Gold Rises, but on Track for Weekly Loss as Fed Rate Hike Expectations Build

FILE PHOTO: A raw gold bar is displayed at Nigeria’s booth at the 8th China International Import Expo (CIIE) venue in Shanghai, China, November 5, 2025. REUTERS/Maxim Shemetov/File Photo

Gold prices rose on Friday but was on track for a weekly loss, as rising US Treasury yields and growing expectations of Federal Reserve rate hikes weighed on the metal.

Spot gold was up 0.6% at $4,303.19 per ounce by 1210 GMT, but was down about 1.7% so far this week. US gold futures rose 1% to $4,339.

US and Iranian negotiators in New York are seeking a deal that would involve Tehran reopening the Strait of Hormuz and Washington lifting its economic blockade of Iran, sources close to the talks said.

"Gold finds support today as oil prices pull back on renewed hopes for a US-Iran deal," said Nikos Tzabouras, a senior market analyst at Jefferies-owned Tradu.com.

"That said, the precious metal is heading for weekly losses, as higher Fed rates and bond yields raise the opportunity cost of holding gold."

The Fed raised interest rates by a quarter-point last week, its first hike in three years, and flagged more hikes follow. Traders are pricing in a 71% chance of an October hike and a 95% chance of an increase in December, according to the CME FedWatch Tool.

Although gold is traditionally seen as a hedge against inflation, higher rates dampen demand as investors shift to yield-bearing assets.

Gold demand in India picked up modestly this week as lower prices drew in buyers ahead of the festive season.

Oil prices fell, and the dollar eased about 0.3%, making greenback-priced bullion more affordable for holders of other currencies.

"Lingering deficit fears could revive the debasement trend that drives investors toward hard assets like gold. Alongside persistent central bank demand, the precious metal has a credible case for a strong fourth-quarter recovery, should the macro winds begin to shift," said Tzabouras.

Spot silver gained 1.4% to $64.82 per ounce, platinum added 1.7% to $1,777.38 and palladium fell 0.4% to $1,269.77. All three metals were poised for weekly losses.


Dollar Falls as Oil Eases, Yen Rallies on Japan Remarks

US dollar banknotes (Reuters)
TT

Dollar Falls as Oil Eases, Yen Rallies on Japan Remarks

US dollar banknotes (Reuters)

The dollar fell on Friday as oil prices eased, but was poised for a second straight weekly advance on growing rate hike bets, while the yen rallied after Japan said Tokyo and Washington remain committed to the stance behind July's joint intervention.

The dollar was on track to snap a four-day streak of gains as crude prices fell more than 1%.

Global oil prices have eased but still they remain above $100 a barrel, maintaining upward pressure on inflation.

Comments from central bank officials flagging inflation concerns and support for more rate increases after last week's rate hike of 25 basis points have boosted market expectations for a more aggressive path of monetary policy and helped spark a jump in US Treasury yields.

"We've had like a pretty aggressive rally in the dollar over the last couple of days and maybe it's a little stretched, just taking a little breather. So I wouldn't really say that the dollar is really weakening materially today," said Eugene Epstein, head of trading and structured products at Moneycorp in Stamford, Connecticut.

"It's just a combination of those factors that you have not only a slight increase in odds of a second hike before year-end, but also just general bond yields going up and the market getting a bit concerned about that, so that's really what we have, what's been driving the dollar stronger overall."

DOLLAR INDEX POISED FOR BIGGEST DROP IN THREE WEEKS

The dollar index, which measures the dollar against five other currencies, fell 0.34% and was on track for its biggest daily percentage drop since September 3, to 100.95. The euro was up 0.2% at $1.1402 but on pace for a third straight weekly decline.

Expectations for a rate hike from the Fed at its October meeting stood at about 66%, according to CME FedWatch, up from about 58% a week earlier.

On the data front, new orders for US-manufactured capital goods increased more than expected in August and data for the prior month was revised sharply higher, pointing to another quarter of robust growth in business spending as part of artificial intelligence infrastructure is created.

In a separate report, the University of Michigan's Surveys of Consumers said its Consumer Sentiment Index ticked up to 48.1 from the prior reading of 47.8, above the 47.6 estimate of economists polled by Reuters.

Sterling strengthened 0.24% to $1.3247, supported by hawkish comments from Bank of England Governor Andrew Bailey. Yet it remained close to a three-month low hit on Thursday.

YEN STRENGTHENS AS JAPAN STEPS UP INTERVENTION WARNINGS

The Japanese yen strengthened 1.09%, on pace to snap a four-day streak of declines and its biggest daily gain against the dollar since September 7, to 157.13.

The currency rose after Japan's Finance Minister Satsuki Katayama said US President Donald Trump raised concern about yen weakness during a summit with Japanese Prime Minister Sanae Takaichi earlier this week.

Katayama said this reaffirmed the shared US-Japan stance behind July's joint intervention, adding she and Treasury Secretary Scott Bessent would stay in close contact as policymakers stepped up warnings over renewed yen weakness.

Still, the yen was on track for a second weekly fall, after markets judged the Bank of Japan's rate hike last week to a 31-year high and its latest guidance as insufficiently hawkish.

Elsewhere, the dollar strengthened 0.14% to 6.725 versus the offshore Chinese yuan, as a Trump-Xi summit in Washington showed no signs of breakthroughs at a closed-door meeting on thorny issues such as AI, trade, Taiwan and the Iran war.


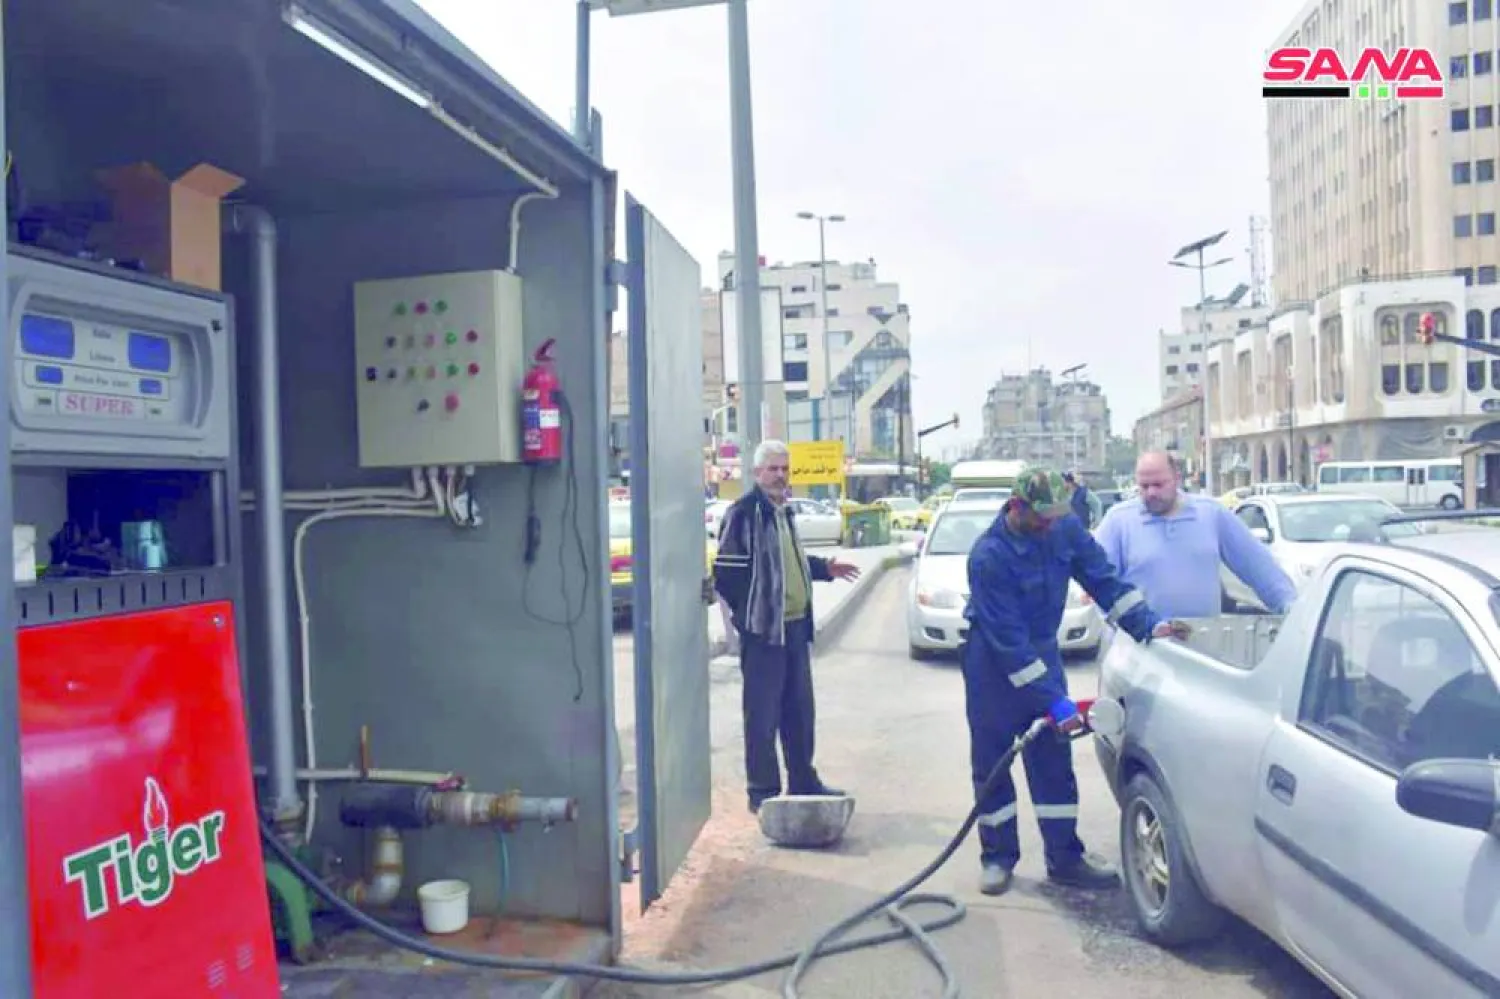
Gasoline Shipped to Syria Begins Moving by Road to Iraq, Syrian Official Says

FILE - This file photo released on April 7, 2019, by the Syrian official news agency SANA, shows a worker filling a pickup at a gas station, in Homs, Syria. (SANA via AP, File)
TT

Gasoline Shipped to Syria Begins Moving by Road to Iraq, Syrian Official Says

FILE - This file photo released on April 7, 2019, by the Syrian official news agency SANA, shows a worker filling a pickup at a gas station, in Homs, Syria. (SANA via AP, File)

Gasoline shipped to Syria has begun moving by road to Iraq, a senior Syrian oil official told Reuters, establishing a two-way energy corridor through a route Baghdad has used to export fuel since disruption to shipping through the Strait of Hormuz.

Iraq began using the Syrian route after the Iran war cut off the Strait of Hormuz, its main Gulf trade route. Baghdad has said it plans to develop alternative routes through Syria even if traffic through Hormuz normalizes.

Transport of fuel oil had so far been from Iraq to Syrian ports before establishment of the return leg.

The first cargo to Iraq, about 32,800 metric tons of gasoline aboard the Marshall Islands-flagged tanker Avanti, was unloaded into storage tanks at Syria's Baniyas refinery before being loaded onto trucks this week, said Tareq Shallash, director of the Refining Directorate at state-owned Syrian Petroleum Company (SPC).

Shallash said 77 tanker trucks have already left Baniyas for the Iraqi border and loading was continuing, adding that further shipments were expected.

The gasoline was neither produced in Syria nor drawn from stocks intended for the Syrian market, he said.

The operation is being carried out under a transit contract between SPC and Qatar's UCC Holding, which Shallash said was the supplier and was overseeing transportation.

"A contract was signed between SOMO and the Qatari company to supply Iraq with improved gasoline through the port of Banias by road tankers, and the supplies have in fact been delivered on a regular basis," Iraqi oil ministry spokesperson Saleem al-Rikabi told Reuters on Friday when asked for comment.

Another Marshall Islands-flagged tanker, Gaita, loaded gasoline at the Port of Houston before sailing to Baniyas for discharge, LSEG shipping data showed.