Investors in US Push Into a Resurging Market: House Flipping

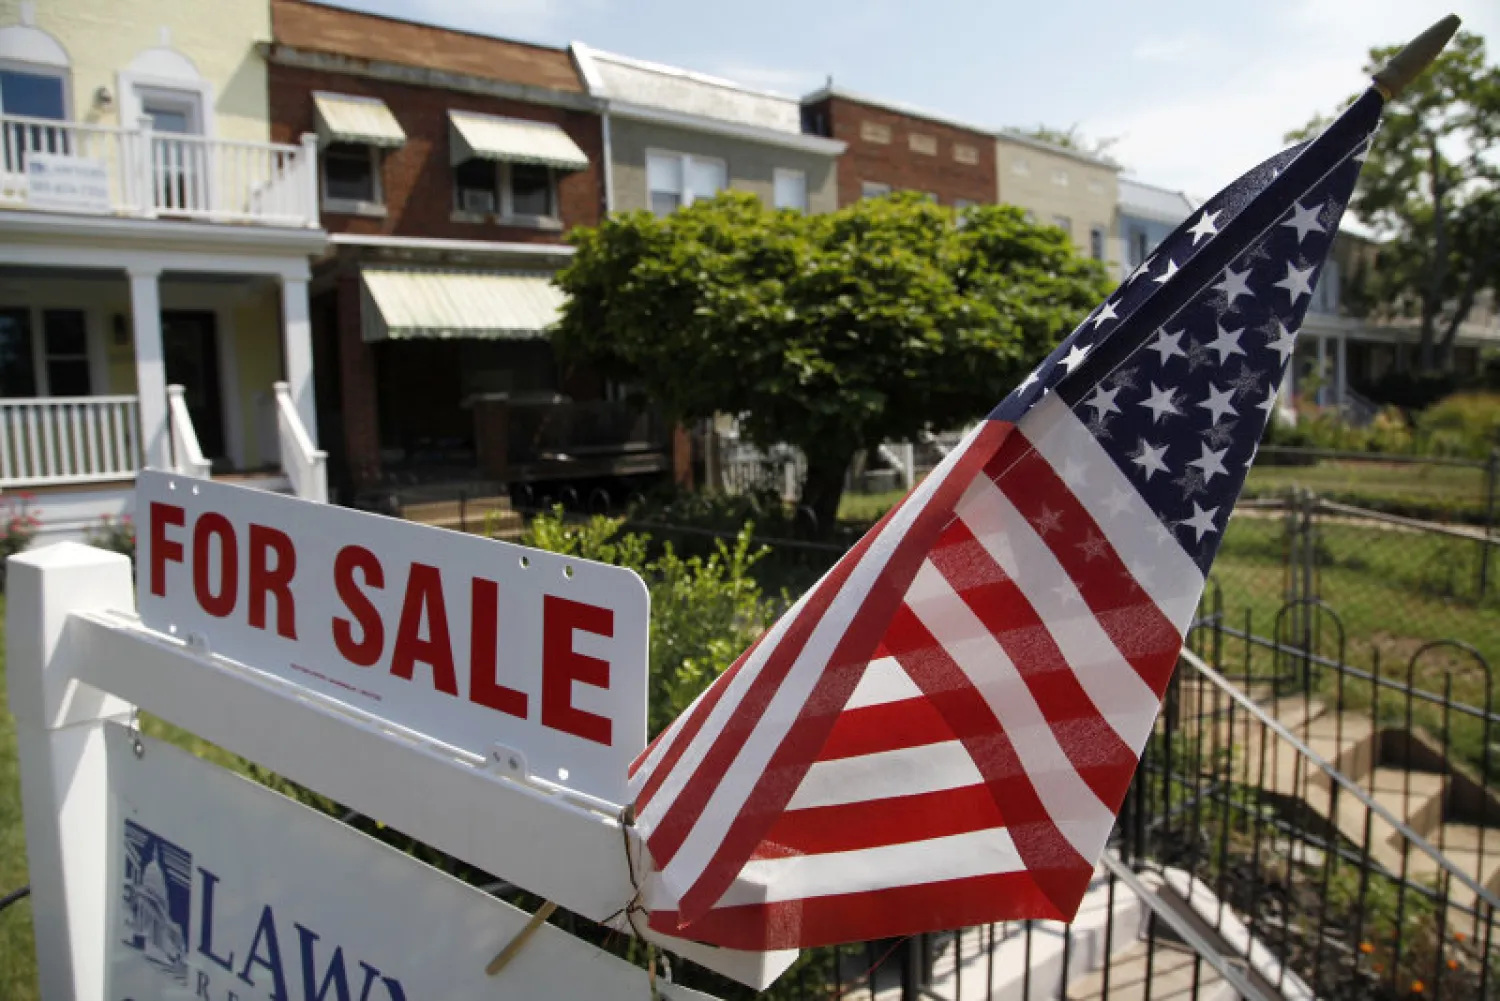
A US flag decorates a for-sale sign at a home in the Capitol Hill neighborhood of Washington, August 21, 2012. REUTERS/Jonathan Ernst
TT

Investors in US Push Into a Resurging Market: House Flipping

A US flag decorates a for-sale sign at a home in the Capitol Hill neighborhood of Washington, August 21, 2012. REUTERS/Jonathan Ernst

House flipping, which declined after the financial crisis in 2008, is on the rise again, thanks to low interest rates and rising home prices. And with the renewed interest come investors looking for a high return.

But that real estate strategy — in which a home is bought, renovated and resold quickly — requires fast access to money, and developers are willing to pay higher interest rates for it. The loans are backed by the property and are short, typically running for a year or less. And the funds that finance them offer reliable returns of about 8 percent, for those who can meet minimum investments, generally $100,000.

The finance industry around house flipping has been active for decades, and it has been ticking up lately. Last year, 5.7 percent of all home sales were flips, the highest level since 2006, according to Attom Data Solutions, a national property database. The trend, popularized on TV series like “Flip or Flop” on HGTV and “Flipping Out” on Bravo, is attracting the interest of Wall Street: Last week, Goldman Sachs bought Genesis Capital, a leading lender to house flippers.

But the loans — sometimes referred to as fix-and-flip or hard-money loans — come with risks, including developers unable to pay them back and a drop in real estate prices that could make properties hard to sell or even rent.

Chris Gutek, a former equity analyst at Morgan Stanley who has been an independent investor in Grand Rapids, Mich., for the last decade, said he lost money on loan funds in 2008 but remained bullish on the sector.

“I was getting nice 12 to 13 percent interest for a few years, but I had one very bad experience in 2008,” Mr. Gutek said. “I lost a bunch of money. It was not good underwriting.”

Funds set up these days by lenders like Genesis Capital in Los Angeles and Anchor Loans in Calabasas, Calif., say they are more transparent and conservative in their underwriting. Mr. Gutek has put about 20 percent of his liquid assets in a fund managed by Broadmark Capital, an investment bank in Seattle that has $350 million in 200 short-term loans.

“Since 2009, the fund hasn’t been tested, and I’m very, very aware of that,” Mr. Gutek said. “There is some risk that real estate values will reset, but I feel good about the meaningful investment process.”

For skeptics, the quick turnaround on real estate speculation might evoke the go-go thinking that led to the mortgage crisis just a decade ago. But investors say hard-money loans are more stable than a bank mortgage because they are secured by properties at a lower loan-to-value ratio, a risk assessment used by lenders.

The average loan-to-value ratio in the industry is about 55 percent, compared with 75 percent to 80 percent for a typical mortgage. This provides a substantial cushion to protect against a property’s falling in value. It also ensures that developers do not walk away from the properties, because they have put a substantial amount of their own money into a project.

“When the loan matures — let’s say it’s 11 months — we want our borrower to be successful,” said Stephen Pollack, the chief executive and president of Anchor Loans.

If the developer runs into a problem, “we’ll try to help them come up with a solution,” he said. “Maybe we’ll ask them to put a tenant in there and take out a rental loan. But if the risk of the loan has changed and it’s at a higher leverage amount, we want to do something to get us in a safer position.”

In other words, the developer needs to put more money in, which Mr. Pollack said most of them agree to because they want to continue their relationship with Anchor.

And because the length of the loan is shorter than a mortgage, the risk is smaller.

“There’s an asset bubble in stocks and a bond rally,” said Shannon L. Saccocia, managing director of Boston Private Wealth. “Is this creating the opportunity for another bubble in real estate? The reality is for us, given the short duration of the loans, they’re easy for us to monitor. They’re very different from securitization.”

To make their portfolios more stable, some lenders diversify across several states so they are not stuck in one market or move into different types of real estate, like retail and land.

“The benefit for a high-net-worth investor coming in is, they’re instantly diversified,” said Joseph L. Schocken, president of Broadmark Capital. “And to have that kind of diversified portfolio producing the yield we’ve produced — roughly 11 percent — is very unusual. What will get your attention is the stability.”

His firm runs two funds and is about to start a third. All three focus on booming cities like Atlanta, Denver and Seattle. He said his goal was to make the book of loans as transparent as possible.

The average loan varies in size depending on the lender, ranging from several hundred thousand to $15 million. At Rubicon Mortgage Lending, loans range from $800,000 to $1 million. Douglas C. Watson, a principal at the firm, said that although Rubicon was focused on the San Francisco Bay Area, it had diversified into retail, storage and land.

Hard-money lenders boast of the speed in which they finance loans, typically in less than a week, compared with several months for a traditional bank. For the smaller builders and house flippers who rely on these loans to do business, the speed with which these lenders can have the money ready trumps the high interest rates they charge.

Jeff Walker, a principal at Square One Homes in Renton, Wash., which builds multifamily homes in Seattle, said he had been using hard-money lenders for more than a decade. He has borrowed often from Broadmark and tries to laugh off the rates he gets — usually around 12 percent interest with 4 percentage points of fees for a one-year loan: “That’s outrageous, but what are you going to do?”

It’s the company’s timeliness that matters to him when he needs to move quickly in the hot Seattle real estate market.

“I can say, I’ll close on it within 48 hours, and I can get them to help me do it,” he said. “I can compete against a cash buyer, even though I’m not a cash buyer.”

But even Mr. Walker, who said he typically made 35 to 40 percent return on his projects, is cautious that too much of a good thing can be, well, too much.

“Seattle is a booming market,” he said. “It’s going to come to an end at some point, but why not make it while you can?”

Investors seem undaunted by the risk of a collapse.

Richard Mulcahy, president of the Washington division of Northwest Bank, said he had started investing his personal money in hard-money loans after seeing how well the builders did with the loans.

“The vast majority of builders could graduate to the national bank stage, but many are willing to pay that cost of credit because they know they can get a loan,” he said.

Mr. Mulcahy said he had invested about 50 percent of his wealth in one of the Broadmark funds. “Various people who are professionals in the industry, including one of my sons, say it’s too high,” he said. “It speaks to my absolute feeling of security and the way they’ve set up the fund,” which has no debt and invests only in first mortgages.

Goldman Sachs’s acquisition of Genesis Capital might demonstrate the evolution of the industry.

The firm had expanded rapidly after a 2014 investment of at least $250 million from Oaktree Capital Management that Genesis used to buy out its early, individual investors and grow nationally, said Rayman Mathoda, co-chief executive of Genesis.

Ms. Mathoda said the company focused now on small to midsize real estate businesses, not individual borrowers.

“A lot of folks make the mistake of thinking of this as a ‘once in a cycle’ opportunity when real estate is booming,” she said. “It’s driven by the metropolitan areas. We’re improving the super-aged housing stock in America.”

But the business is still driven by wealthy investors able to meet minimum investments of $100,000 or more.

“In these markets, the risks feel reasonable,” Mr. Gutek said. “If Seattle’s real estate is cratering, the stock market has already cratered.”

The New York Times


Lucid Gets Crucial $1.75 Billion Liquidity Boost From PIF

A Lucid Air Grand Touring electric car is displayed during the New York International Auto Show in New York City, US, April 1, 2026. REUTERS/Jeenah Moon/File Photo 
TT

Lucid Gets Crucial $1.75 Billion Liquidity Boost From PIF

A Lucid Air Grand Touring electric car is displayed during the New York International Auto Show in New York City, US, April 1, 2026. REUTERS/Jeenah Moon/File Photo 

Lucid Group, an American electric vehicle (EV) manufacturer, said on Monday a $1.75 billion increase in a loan facility from Saudi Arabia's Public Investment Fund (PIF), its largest investor, would help fund the ‌electric-vehicle maker into the fourth quarter of 2027, according to Reuters.

The larger delayed-draw term loan lifts the company’s pro forma liquidity to $3.75 billion, strengthening new CEO Silvio Napoli's hand as he seeks to turn around the company facing an industry-wide demand weakness following the expiry of a federal ⁠tax credit last year.

Lucid said it expects its liquidity to fund operations until production of its midsize vehicle begins in the second half of 2027.

The company’s shares were down about 5% in extended trading.

Lucid cut its third-quarter cash outflow to $1.04 billion from $1.48 billion in the previous quarter by cutting production, including eliminating a second shift at its Arizona factory and reducing inventory and operating costs.

“These actions are already showing through in Q3, ‌with ⁠free cash flow consumption 30% lower sequentially,” CFO Alexander De Bock said.

Lucid said it would provide 2027 guidance and a mid-term plan with its year-end results. It had withdrawn its annual production forecast earlier this year amid a sweeping operational ⁠review by its newly appointed CEO.

The company said headcount fell about 28% between the first and third quarters. It said it had achieved $800 million of a targeted $1.4 ⁠billion cash flow improvement this year through lower inventory, operating costs and capital spending.

New chief technology, finance, customer and transformation officers joined early in ⁠the third quarter, the company said. Lucid is also cutting management layers and tying incentives to four priority projects.


Saudi Real Estate Market Maintains Investment Momentum Despite War Fallout

Residential developments in Saudi Arabia (Ministry of Municipalities and Housing)
TT

Saudi Real Estate Market Maintains Investment Momentum Despite War Fallout

Residential developments in Saudi Arabia (Ministry of Municipalities and Housing)

Saudi Arabia's real estate market continues to attract investment despite geopolitical challenges weighing on economic activity worldwide, supported by new housing developments and efforts to expand residential supply.

The Ministry of Municipalities and Housing announced that more than 15,000 residential land plots had been made available through the Sakani platform across the Kingdom between the beginning of 2026 and the end of October, alongside additional projects launched by private-sector developers.

The developments underscore the sector's continued momentum and its importance to the Saudi economy.

Government initiatives and private-sector projects aim to expand housing supply and meet growing demand, reinforcing real estate's position as a key driver of economic growth and diversification.

Strong domestic demand and ongoing urban development projects continue to underpin the market's appeal, attracting investment from both Saudi and international investors.

Against a backdrop of geopolitical uncertainty and war-related disruptions to trade, supply chains, financing costs and construction expenses, the real estate sector has gained importance as an industry driven largely by domestic demand and capable of sustaining economic activity.

Private-Sector Investment

Despite mounting global economic volatility and geopolitical tensions, Saudi Arabia's real estate market continues to attract international investment, supported by clear economic policies, expanding development opportunities and strong housing demand.

Real estate developer Arada recently announced its entry into the Saudi market through a partnership with local company XTOPIA, backed by a SAR 50 billion ($13.3 billion) portfolio of land and development opportunities.

The partnership's first project is a SAR 14 billion residential development in Riyadh's Al Rimal district.

Riyadh Region Municipality, the Ministry of Municipalities and Housing, and the National Center for Privatization & PPP also recently announced the launch of the expression of interest, prequalification and proposal submission stages for a joint land investment project.

The initiative involves developing a municipal land plot in northern Riyadh through a 50-year partnership with the private sector, marking the municipality's first project under the joint investment model.

Real estate specialists described the initiative as an important step toward enabling private investors to develop property assets into sustainable projects with significant economic value.

They said the extended investment period would encourage developers to improve construction quality and services, strengthen project feasibility, diversify real estate offerings and increase supply in one of the capital's most expensive neighborhoods.

Balancing the Real Estate Market

The importance of releasing more residential land lies in achieving greater balance in the property market, a government objective outlined by Crown Prince and Prime Minister Mohammed bin Salman.

The strategy seeks to increase housing supply by making more land available, broadening the options accessible to Saudi citizens and enabling more households to move from searching for a home to building and owning one.

Increasing the availability of residential land, particularly in cities and governorates experiencing rising demand, could ease pressure on land prices over the medium term, provided that plot locations and sizes correspond to actual market needs.

The release of additional land also creates opportunities for real estate developers, contractors, engineering firms and building materials suppliers to benefit from anticipated demand for construction projects.

As a result, businesses across the real estate and construction supply chain could see stronger activity despite the impact of the geopolitical crisis on other economic sectors in the region.

The initiative also expands housing choices, supports efforts to increase homeownership rates and improve quality of life, and encourages urban development beyond major metropolitan centers.

Lowering Prices

Real estate developer Ahmed Omar Basoudan believes the main challenge facing Saudi Arabia's property market in the coming period will not simply be increasing the number of land plots and housing units available.

Rather, he said, the priority must be ensuring that homes reach buyers at prices they can afford, while providing adequate infrastructure and services and keeping development and construction costs under control.

Speaking to Asharq Al-Awsat, Basoudan explained that genuine balance in the real estate market depends on the availability of housing that meets buyers' needs in terms of price, location and quality, rather than simply increasing overall supply.

He said the release of more than 15,000 residential land plots during the first 10 months of the year, together with recently announced private-sector projects, reflected the government's continued commitment to expanding housing supply and providing more residential options.

Basoudan stressed that the latest real estate developments represent an important step toward addressing one of the market's most pressing challenges: achieving a sustainable balance between supply and demand, particularly amid the Kingdom's population growth and continued urban expansion.


Saudi Stocks Rebound 0.9%, Recouping Previous Session's Losses

An investor monitors stock market data on a screen at the Saudi Exchange (Tadawul) in Riyadh (Reuters)
TT

Saudi Stocks Rebound 0.9%, Recouping Previous Session's Losses

An investor monitors stock market data on a screen at the Saudi Exchange (Tadawul) in Riyadh (Reuters)

Saudi stocks closed higher on Monday, recovering some of the losses sustained in the previous session as heavyweight shares strengthened and the banking sector advanced.

The benchmark Tadawul All Share Index (TASI) rose 0.90% to close at 10,106 points, gaining 90 points. Total trading value reached approximately SAR 3.5 billion ($933 million).

The index had fallen 0.8% on Sunday amid selling pressure on heavyweight stocks.

Anaam International Holding Group, Fitaihi Holding Group and Raoom were among the session's top gainers, rising between 7% and 9% to close at SAR 11.93, SAR 2.11 and SAR 72.30, respectively.

On the losing side, Almunajem Foods led the declines, shedding 9.20% to SAR 49.94, followed by Saudi Paper Manufacturing Co., which fell 6.18% to SAR 48.88, and Alamar Foods, which dropped 4.63% to SAR 44.06.

At the sector level, banks led the gains, advancing 1.60%, supported by a 2.06% rise in Bank AlJazira shares, which closed at SAR 10.89.