Sanctions-Hit Iran Props up Economy with Bartering, Secret Deals

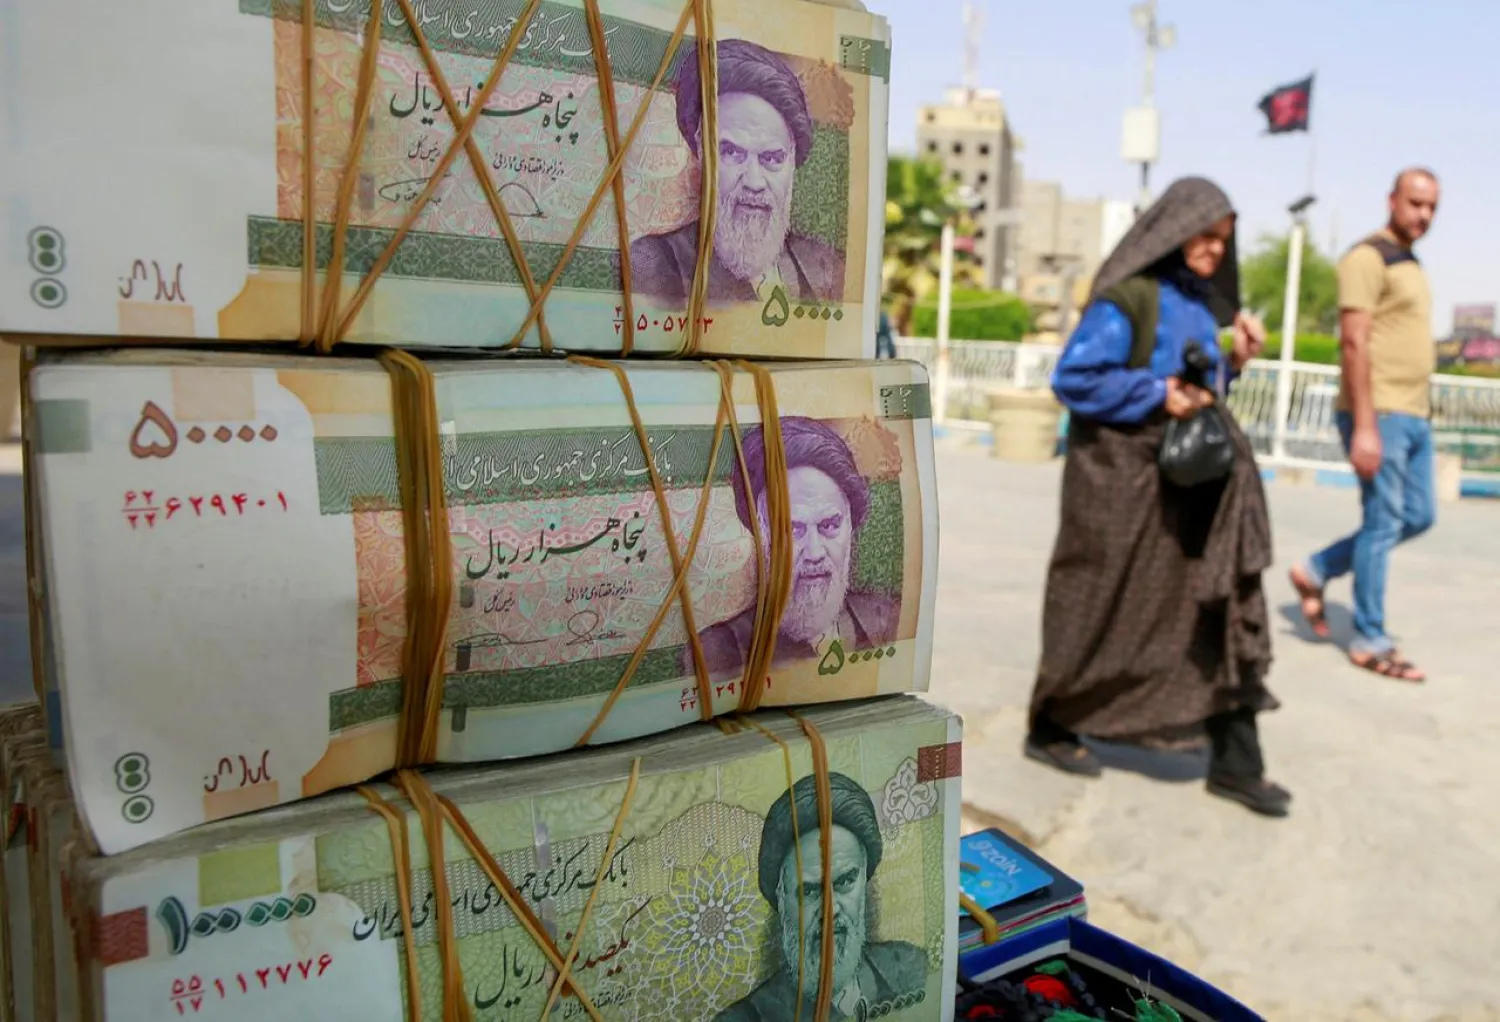
Iranian rial currency notes are seen at a market in the city of Najaf, Iraq September 22, 2019. (Reuters)
TT

Sanctions-Hit Iran Props up Economy with Bartering, Secret Deals

Iranian rial currency notes are seen at a market in the city of Najaf, Iraq September 22, 2019. (Reuters)

Washington’s policy of applying “maximum pressure” on Iran with wide-ranging sanctions has shredded the country’s oil revenues, sent its economy into recession and devalued its national currency.

Yet Iran remains defiant in the face of US efforts to compel it to accept tougher restrictions on its nuclear program and scale back support for proxy wars across the Middle East.

Iranian officials, business people and analysts say the country is staying on its feet by stepping up exports of non-oil goods and increasing tax revenues, but most importantly resorting to bartering, smuggling and back-room deals.

To circumvent US banking and financial sanctions, Iran’s rulers have built up a network of traders, companies, exchange offices, and money collectors in different countries, they say.

“America cannot isolate Iran,” said one senior Iranian official, who like other officials asked not to be named.

Ali Vaez, Iran Project Director at the International Crisis Group, said although the Iranian economy was in dire straits, it was far from being overwhelmed.

“Iran is quite experienced in living under economic duress ... In the past few years, its non-oil exports have grown significantly and so has their trade with neighboring countries like Iraq and Afghanistan,” Vaez said, according to Reuters. “Iran can also smuggle oil and generate some revenue.”

Tough sanctions

Western companies raced back to Iran’s market and its oil income surged a year after a 2015 nuclear pact agreed with six major powers ended the sanctions regime imposed in 2012 over its disputed nuclear program.

New sanctions brought in after President Donald Trump withdrew from that agreement last May are the most painful ever imposed by Washington, targeting nearly all sectors of Iran’s economy including how it finances its international trade.

The OPEC member’s crude exports have been slashed by more than 80 percent since last year, against 2012 when exports plummeted to less than 1.3 million barrels per day (bpd) from about 2.5 million bpd.

Although food and medicine are exempt, lack of access to the global financial system has given rise to a humanitarian crisis with shortages of specialized medicine.

The International Monetary Fund has forecast that Iran’s economy will contract in 2019 by 3.6 percent because of dwindling oil revenues. The World Bank anticipates inflation jumping to 31.2 percent in 2019-20 from 23.8 percent in 2018-19 and 9.6 percent the year before that. Some economists believe inflation has actually topped 40 percent.

Iranian officials repeatedly contend that the country can weather the storm, but the reality on the ground is harsh.

The sharp devaluation of Iran’s national currency and difficulty paying for urgent import needs have led to spikes in the prices of bread, rice and other staples.

“It is easy for officials to talk about resisting America’s pressure. They don’t have to be worried about the rent or increasing prices of goods,” said Ali Kamali, a 63-year-old retired teacher in Tehran. “Prices are going up every day.”

An end to sanctions is not in sight anytime soon, with Trump saying on Tuesday that pressure will intensify on Iran. Iranian President Hassan Rouhani will give a speech at a UN General Assembly on Wednesday that will likely determine whether Tehran will re-engage with the United States.

Tensions have been further raised by September 14 attacks on Saudi Arabia’s oil sites that Washington, Riyadh and the European Union blame on Iran. Tehran denies involvement in the attacks, which were claimed by Iran-aligned Houthi militias in Yemen.

“Iran doesn’t have many other sources of income, beyond oil, so their economy is in a tailspin ... They do have considerable budgetary reserves ... to get them past the next few months, but the situation is not tenable,” said Chuck Freilich, senior fellow at the Belfer Center for Science and International Affairs.

Finance has dried up

The financial sanctions have hit banks, institutions, individuals and front companies in several countries like Turkey and Qatar.

Iran has used the barter system to evade such sanctions in the past, but the scale is bigger this time, especially with neighboring countries, including Iraq, Pakistan and Afghanistan.

“We are a rich country with long borders with so many countries. If you sell anything below its market price, you can find dozens of buyers ... And transfer the cash by land, sea or even through a third country,” said another Iranian official.

The majority of Iran’s non-oil exports are from the petrochemical industry, whose output reached 44.8 million tons in the first ten months of the last Iranian year that ended in March. Exports generated over $9.7 billion.

Iran is still managing to export cargoes of petrochemical products and liquefied petroleum gas to Asia, including to China and Malaysia.

“Our customers come to Iran or we meet them in a neighboring country. This is business and when the price is lower than the market price, you can find many buyers,” said a third official.

On a recent visit to Istanbul, Reuters was invited to a meeting of three young Iranians with a small group of foreign traders to discuss non-oil export deals.

After hours of discussions and several calls to Tehran to get guidance on the price and location of delivery, two deals worth around two billion dollars were finalized.

“No insurance, no banks ... just cash,” said one of the Iranians, who ran a government-linked import-export company.


Gulf Railway Enters Implementation Phase, Targets 2030 Completion

Members of the GCC Transport and Communications Ministers Committee pose for an official photo in Manama (GCC). 
TT

Gulf Railway Enters Implementation Phase, Targets 2030 Completion

Members of the GCC Transport and Communications Ministers Committee pose for an official photo in Manama (GCC). 

Gulf Cooperation Council (GCC) countries signed an agreement in Manama on Sunday to advance a 2,117-kilometer railway linking all six member states by 2030, as shipping disruptions in the Strait of Hormuz underscore the need to diversify trade and supply routes.

The agreement establishes a common framework for building and operating the network and integrating national transport systems, amid regional tensions that have disrupted cargo movements, raised shipping and insurance costs, and highlighted the importance of alternative routes.

The Gulf railway is intended to strengthen regional logistics rather than replace maritime transport, which remains essential to Gulf and international trade.

The signing ceremony was held under the patronage and in the presence of Bahrain’s Crown Prince and Prime Minister Prince Salman bin Hamad Al Khalifa, with GCC transport ministers and Secretary-General Jasem Mohamed Albudaiwi attending.

The planned network will connect Kuwait, Saudi Arabia, Bahrain, Qatar, the United Arab Emirates and Oman, with full operations targeted for December 2030.

The agreement sets out member states’ obligations, coordination mechanisms, technical and operational standards, and safety requirements to ensure compatibility with national railway systems.

Bahrain’s Minister of Transportation and Telecommunications, Dr. Sheikh Abdulla bin Ahmed Al Khalifa, told Asharq Al-Awsat that each country would finance and implement the section within its territory.

He explained that GCC states had not signed prior agreements with international partners to finance or execute the project, although global companies could provide expertise and technical and technological services according to national requirements.

Project 55.9% Complete

Albudaiwi announced that the Gulf railway project had reached 55.9% completion, describing the agreement as a framework governing member states’ commitment, implementation procedures and the timetable for bringing the network into service.

While full operations are scheduled for December 2030, cross-border connections between neighboring countries could open individually once the necessary infrastructure and operational requirements are met.

This would allow completed sections to enter service progressively rather than waiting for the entire 2,117-kilometer network to be finished.

Projections indicate that the railway will carry approximately 6 million passengers and 200 million tons of freight in 2030, rising to more than 8 million passengers and 271 million tons by 2045.

Passenger trains are expected to reach speeds of 200 kilometers per hour, while freight services will operate at 80 to 120 kilometers per hour.

The network will connect economic and industrial centers, ports and logistics hubs across the Gulf, facilitating trade and the movement of passengers and goods while creating investment and employment opportunities in transport and related services.

National Financing and Potential Partnerships

Earlier estimates put the cost of the project’s core infrastructure at between $15.4 billion and $16 billion.

The Bahraini minister explained that these figures were under review because of rising costs for construction materials, services and building works. No revised estimate for the overall project has been announced.

Although each country will fund its own section, private-sector participation remains possible in certain components, subject to economic and financial feasibility studies.

The minister added that potential partnerships would depend on the requirements of individual sections, with no single financing or implementation model envisaged for the entire network.

Bahrain’s connection to the Gulf railway depends on the proposed King Hamad Causeway, which would link the island kingdom to Saudi Arabia through a railway alongside a road connection.

The project would connect Bahrain’s international passenger terminal with the Saudi railway network, providing a direct link to the wider GCC system.

Bahrain currently relies on the King Fahd Causeway for road transport to Saudi Arabia. Studies and procedures concerning the proposed King Hamad Causeway, including its railway component, remain underway as part of efforts to complete the cross-border connection.

Shipping Disruptions Highlight Logistics Challenges

The agreement has taken on added significance following recent disruptions to regional shipping, particularly reduced vessel traffic at Bahrain’s Khalifa bin Salman Port, which has increased reliance on road transport and alternative ports in neighboring countries.

Albudaiwi praised Saudi Arabia, the UAE and Oman for their cooperation during the period of Iranian attacks, citing logistical facilities, coordination and alternative cargo routes that helped maintain supply chains to other GCC countries.

He stressed the need for greater integration among transport systems, more diversified supply routes and stronger preparedness and coordination to manage future crises.

The GCC’s transport and storage sector recorded real growth of 5.7% in 2025, making it one of the fastest-growing non-oil economic activities, he noted.

At the 19th consultative meeting of the GCC Supreme Council in Jeddah on April 28, 2026, Gulf leaders called for a study on strengthening logistics integration among member states as part of broader efforts to develop transport networks and diversify trade and supply routes.

Rail and Maritime Transport to Work Together

Despite the renewed focus on rail connectivity amid shipping disruptions, the project is designed to complement maritime transport rather than compete with it.

Rail services could move goods from ports to industrial centers and domestic markets while providing additional distribution routes between GCC countries. Ships would continue to carry the bulk of international freight over long distances.

Integrating the railway into wider international logistics corridors would require further studies, agreements and coordination among governments and relevant authorities, beyond completing the rail infrastructure within the GCC.

The network is also expected to stimulate intra-Gulf trade, improve connections between production and consumption centers, and attract investment in transportation, logistics and related industries.

Additional employment opportunities are anticipated in construction, operations, maintenance and supporting services.

From a 2009 Proposal to Regional Implementation

The Gulf railway initiative dates to December 2009, when the GCC Supreme Council approved plans for a network connecting member states to facilitate trade, improve mobility for citizens and residents, and strengthen regional economic integration.

In December 2021, the council approved the establishment of the GCC Railways Authority to coordinate national efforts, monitor connectivity and operational requirements, and provide an institutional framework for cooperation.

Implementation has since progressed across member states, with completion exceeding 50% by May 2026.


Saudi Gold Refinery Obtains 10 Gold Exploration Licenses in Tanzania

A gold mine in Saudi Arabia (SPA) 
TT

Saudi Gold Refinery Obtains 10 Gold Exploration Licenses in Tanzania

A gold mine in Saudi Arabia (SPA) 

Saudi Gold Refinery Company (SGR) announced Sunday it has secured 10 licenses to explore gold in the Republic of Tanzania, covering a total area of nearly 1,000 square kilometers, in a move aimed at expanding the company’s mining operations outside the Kingdom.

The company said it has allocated an initial investment of $10 million to carry out exploration activities, within an ambitious plan to gradually increase total investments to $100 million. These investments will support the development, establishment, and operation of gold mines, with commercial production targeted to commence by 2030.

The announcement follows a visit to Tanzania by Faisal Suliman Al-Othaim, Deputy Chairman of the Board of Directors at SGR.

According to the company, this milestone is supported by the Ministry of Investment and the Saudi Embassy in Tanzania, highlighting the importance of strengthening Saudi investments abroad and creating new opportunities for national companies in the global mining industry.

SGR continues to advance its global expansion strategy through its international investment arm, UGM Tanzania co, which oversees its operations and investment activities in Tanzania and Ethiopia.

The company also maintains ongoing projects and business activities in Egypt and the Sultanate of Oman, while actively exploring opportunities in additional markets to further expand its global footprint and create sustainable value across the mining sector.

In the Saudi market, the company plans to develop six to ten mines before 2030, at an average rate of two mines per year. These plans are supported by the Ministry of Industry and Mineral Resources, the Saudi Industrial Development Fund, financial institutions and other relevant authorities and stakeholders.


Oil Falls as Trump Says New Iran Attacks ‘Unlikely’

A worker walks past oil pipes at a refinery in Wuhan, Hubei province March 23, 2012. (Reuters)
TT

Oil Falls as Trump Says New Iran Attacks ‘Unlikely’

A worker walks past oil pipes at a refinery in Wuhan, Hubei province March 23, 2012. (Reuters)

Oil prices fell at Monday's open after US President Donald Trump said he was highly unlikely to order new Iran attacks while talks to end the conflict make progress, despite both nations' reports of attacks on ships in or near the Strait of Hormuz.

Brent was down 84 cents, or 0.85%, to $97.48 a barrel by 0138 GMT, while West Texas Intermediate fell 32 cents, or 0.35%, to $90.51 a barrel.

The fall reversed minor gains made on Friday’s settlement as the market assessed the possibility of further US ‌strikes on Iran, ‌although Brent fell 17% last week, the ‌steepest ⁠weekly drop since the ⁠start of the COVID pandemic and the biggest in absolute terms, according to LSEG data dating back to 1988.

"It depends on whether or not they sign a very strong agreement," Trump told CNN in a phone interview. "The answer is, highly unlikely it's going to be necessary."

Trump had hinted at renewing attacks on Iran after ⁠last week's US midterm elections, but there has ‌been no sign of a large-scale ‌US military operation. Iran has said it would respond by striking US and ‌Israeli targets.

Tim Waterer, chief analyst at KCM Trade, called ‌Trump's comments "more measured" but said "the market is still waiting to see whether the midterms have produced a lasting shift in Trump’s approach to the conflict, or whether this is just another temporary change in tone."

Oil is headed ‌for a glut again as recovering Middle Eastern oil flows, rising production from other countries and ⁠weak demand have ⁠pushed global supply above consumption, JPMorgan said in a report on Friday, estimating a surplus of 1.1 million barrels per day in September, widening to 1.4 million bpd in October.

On Sunday, Iraq reached an understanding with the US to allow Iraqi oil exports through the Strait of Hormuz via a shipping lane near Oman, Foreign Minister Fuad Hussein said in an interview with Al Jazeera.

He said Iraq's losses from the Iran war and disruptions to oil exports had reached $60 billion.