Lebanon's Economic Collapse in Numbers

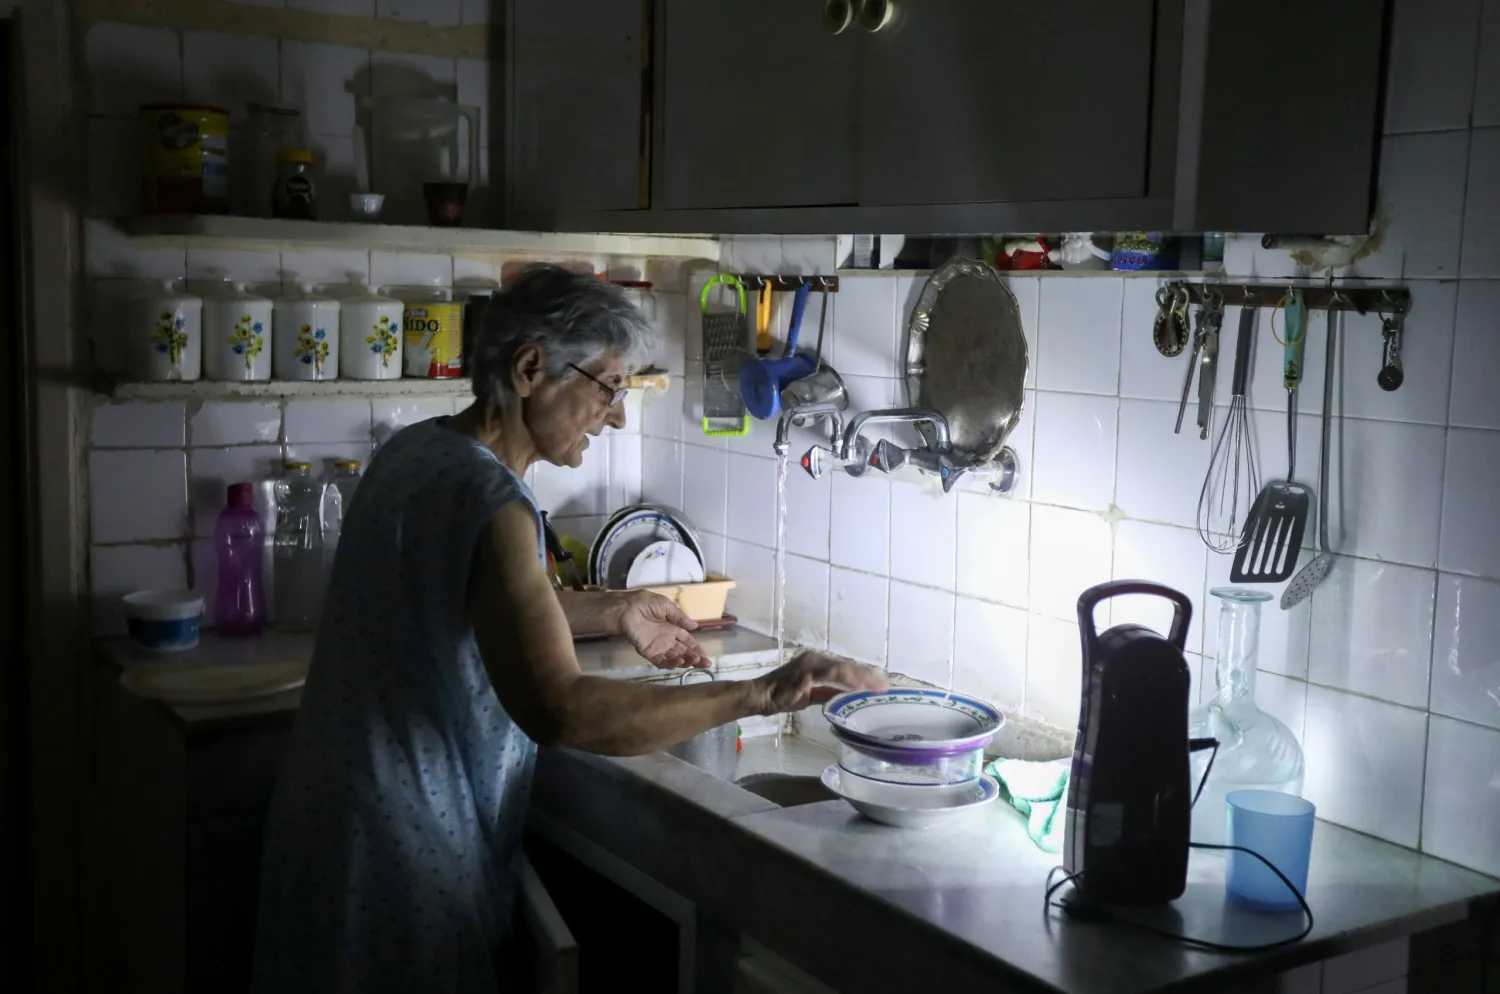
A woman washes dishes in her kitchen as she uses a portable electric light due to a power cut, in Beirut, Lebanon July 6, 2020. Picture taken July 6, 2020. Reuters
TT

Lebanon's Economic Collapse in Numbers

A woman washes dishes in her kitchen as she uses a portable electric light due to a power cut, in Beirut, Lebanon July 6, 2020. Picture taken July 6, 2020. Reuters

Lebanon is battling its worst economic crisis since the 1975-1990 civil war. The national currency is in freefall, while poverty and unemployment are on the rise.

Here are some numbers:

Plummeting pound
The Lebanese pound has lost around 90 percent of its value against the dollar on the black market in 18 months of crisis.
While the currency remains officially pegged to the greenback at 1,507 Lebanese pounds, the exchange rate has shot up to around 15,000 on the black market.

Poverty
Some 55 percent of Lebanese live below the poverty line of 3.84 dollars a day, the United Nations says.

Up to 23 percent of Lebanese live in extreme poverty, compared with just eight percent in 2019.

Inflation
Consumer prices rose by almost 146 percent during 2020, official statistics show.

Food prices overall rose by more than 400 percent last year, the World Food Program says.

The price of a basket of key survival items such as rice, pasta and cooking oil has almost tripled since October 2019, the WFP says.

The price of subsidized bread has risen by 91.5 percent since May 2020, as the cash-strapped government has gradually increased the price of a large packet of flatbread while also diminishing its weight.

The price of meat has increased by 110 percent over the past year, while the cost of chicken has risen by 65 percent, the World Bank says.

Median salary
Before the economic crisis broke in 2019, the median salary in Lebanon was more than 950,000 Lebanese pounds, official statistics show, according to Agence France Presse.

While that salary was worth around $630 dollars before the crisis, its value on the black market on Tuesday was just $63.

Unemployment
In late 2020, unemployment stood at 39.5 percent.

From 2019 to 2020, full-time employment dropped by 40 percent in the construction sector, while it fell by 31 percent in the hotel and restaurant sector, the United Nations says.
Aid

A World Bank loan of $246 million is to provide aid to around 786,000 hardest hit Lebanese.

Recession
Lebanon's gross national product fell by 25 percent last year, the International Monetary Fund says.

Debt
Public debt reached $95.6 billion in late 2020, the country's third largest lender, Byblos Bank, says.

That is equivalent to 171 percent of GDP, the International Monetary Fund says.

Foreign currency reserves
On March 15, the central bank had $17.5 billion in reserves, its website said, even if analysts have alleged the figure is likely lower.

At the end of February 2020, it had stood at $30.3 billion, Byblos Bank analysts said, explaining the drop was mainly due to spending on subsidies including wheat and fuel.
Trade deficit

Lebanon's balance of payments deficit reached $10.2 billion by the end of November 2020, almost double that registered a year before, central bank statistics showed, according to a report by top lender Bank Audi.

Electricity
The government has spent $40 billion on the power sector since 1992, accounting for 40 percent of public debt, a report by the American University of Beirut has said.

Yet the state utility covers only 63 percent of electricity demand, which results in rolling blackouts, a December study by the AUB said.

Now just two weeks remain before a nationwide blackout unless emergency funding is secured to buy fuel oil to operate power plants, the caretaker energy minister has warned.

Coronavirus
Even as it battles with economic crisis, Lebanon has recorded at least 418,448 Covid-19 cases since early last year, 5,380 of them fatal.

Port explosion
A massive explosion at Beirut port last year killed more than 200 people and ravaged swathes of the capital.

It caused between $6.7 billion and $8.1 billion in damage and economic losses, the World Bank said.

Refugees
Lebanon's more than six million inhabitants include around 1.5 million Syrians who have fled war in their homeland, of whom almost one million have been registered as refugees with the United Nations.

Nine out of 10 Syrian refugee families in Lebanon live in extreme poverty, the UN says.

Nearly 180,000 Palestinians also live in Lebanon, according to an official census.

In a May 2020 survey, 80 percent of respondents said they had lost their job or seen their salary reduced, the UN agency for Palestinian refugees said.


Sudanese Energy Minister to Asharq Al-Awsat: Joint Teams with Saudi Arabia to Turn Agreements into Projects

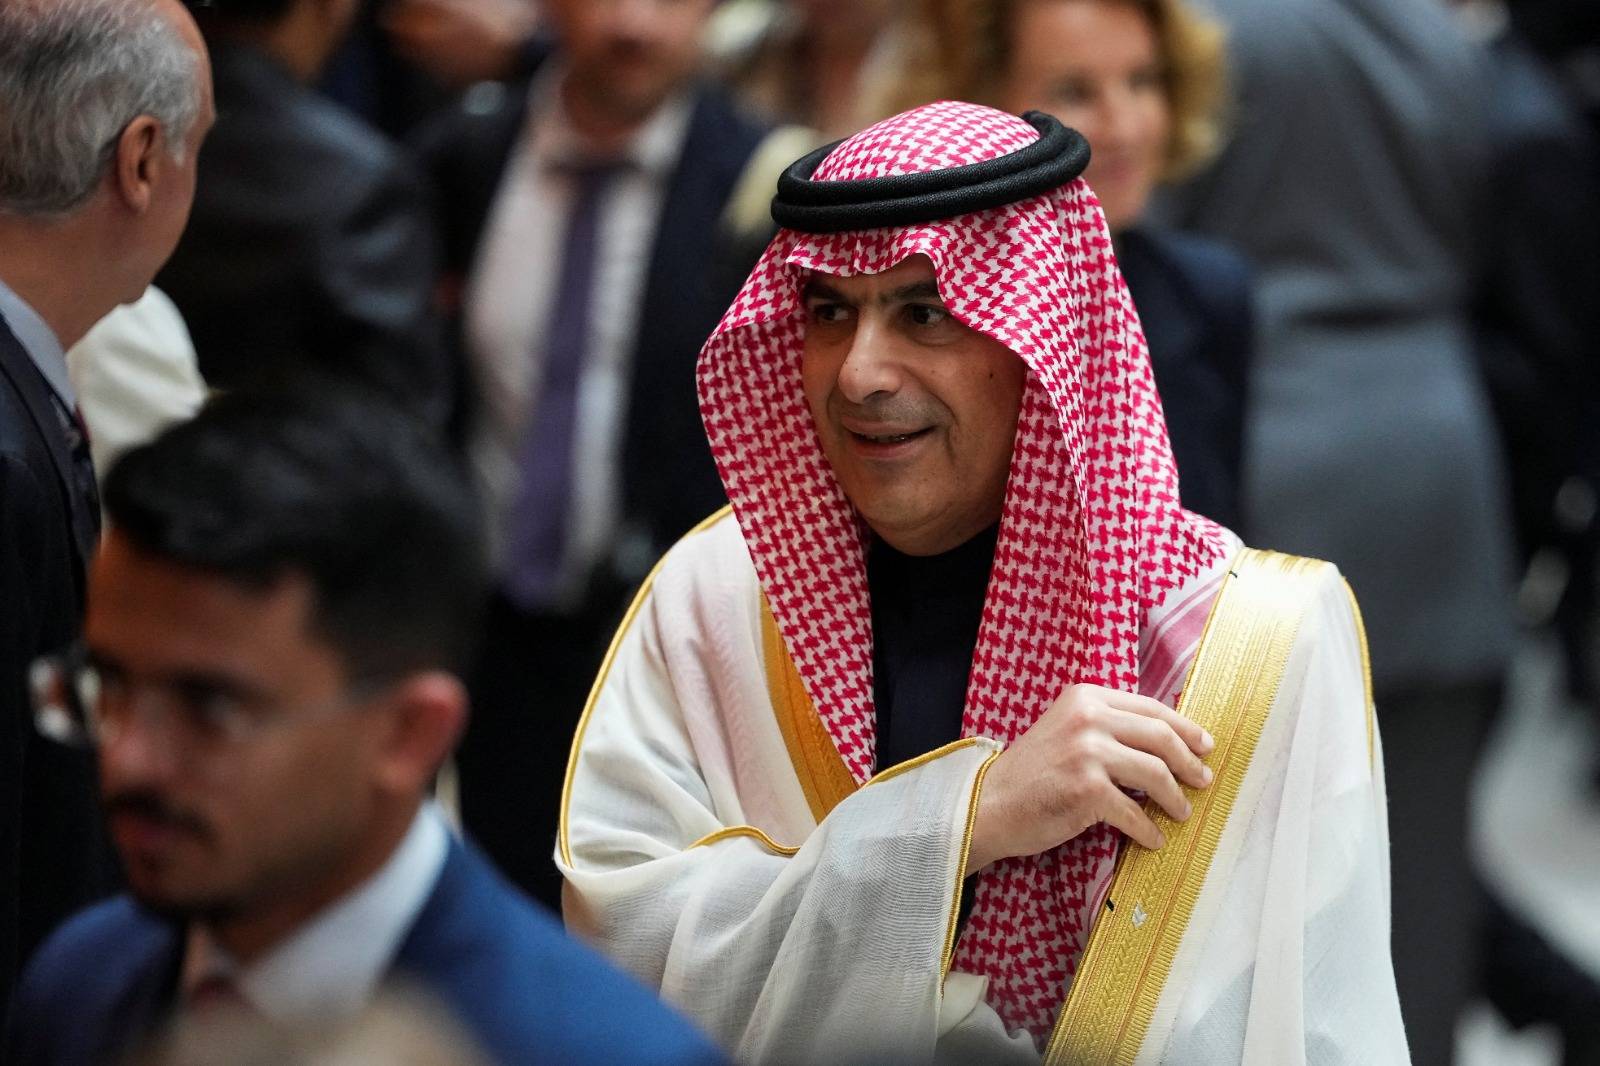
Sudanese Minister of Energy and Petroleum Al-Mutasim Ibrahim meets Saudi Assistant Minister of Energy Mohammed Abdulrahman on the sidelines of the World Petroleum Congress (X)
TT

Sudanese Energy Minister to Asharq Al-Awsat: Joint Teams with Saudi Arabia to Turn Agreements into Projects

Sudanese Minister of Energy and Petroleum Al-Mutasim Ibrahim meets Saudi Assistant Minister of Energy Mohammed Abdulrahman on the sidelines of the World Petroleum Congress (X)

Sudan has established working teams to explore energy partnerships with Saudi Arabia, paving the way to turn bilateral discussions into projects aimed at rehabilitating war-damaged facilities and restoring the country's oil refining and electricity generation capabilities.

Sudanese Minister of Energy and Petroleum Al-Mutasim Ibrahim told Asharq Al-Awsat that cooperation is focused on four main areas: securing fuel supplies, developing oil exploration blocks in the Red Sea, establishing a refinery in Port Sudan, and rehabilitating electricity infrastructure.

The initiative comes as Sudan seeks to restore its energy sector following extensive damage to its facilities, particularly the Al-Jaili refinery, which previously met more than 60 percent of domestic demand. The country currently relies on imports of petroleum products.

Ibrahim said discussions with Saudi officials focused on investment opportunities and technical cooperation, with working teams established to assess the scope of the proposed projects and the mechanisms for implementing them.

He explained that his participation in the World Petroleum Congress, held in Riyadh last week at Saudi Arabia's invitation, provided an opportunity to strengthen consultations on energy issues of mutual concern.

The meetings also explored ways to attract the investment and expertise needed to rebuild and develop Sudan's energy sector, supporting the country's economic recovery.

Ibrahim said he met officials from the Saudi Ministry of Energy and its affiliated entities, as well as representatives of Saudi Aramco, SABIC, ACWA Power and the Saudi electricity regulator.

He explained that cooperation with Aramco focuses on importing petroleum products and ensuring regular supplies to Sudan, particularly given the damage caused by the war to its energy facilities.

Among the most severely affected is the Al-Jaili refinery, which previously supplied more than 60 percent of the country's domestic petroleum needs.

The minister said the visit resulted in understandings to establish working teams to explore partnership and investment opportunities in rehabilitating damaged energy facilities.

These include electricity grids, power and water facilities, restarting the Al-Jaili refinery, and expanding refining capacity in Port Sudan and the Red Sea region.

Four Areas of Partnership

Ibrahim said discussions with Saudi Assistant Minister of Energy Mohammed Abdulrahman focused on four main areas of cooperation.

The first involves strengthening the partnership with Aramco to secure regular supplies of petroleum products and support stability in Sudan's domestic market, particularly after the war damaged the country's production and refining facilities.

The second focuses on opportunities to develop oil exploration blocks in the Red Sea, including encouraging Saudi private-sector investment in exploration and production activities and capitalizing on opportunities in Sudan's petroleum industry.

The third concerns a proposed oil refinery in Port Sudan, which the minister said presents opportunities for technical and investment cooperation with Saudi Arabia, enhancing Sudan's refining capabilities and strengthening energy security.

The fourth involves rehabilitating electricity infrastructure and rebuilding facilities damaged during the war, including exploring ways to provide necessary equipment, exchange technical expertise and develop local capabilities.

Ibrahim stressed that the joint working teams would assess the nature and scale of cooperation required to rehabilitate electricity grids, power stations and water facilities.

Their findings would help determine the next steps and translate the understandings reached into concrete programs and projects.

Rehabilitating Refineries

Ibrahim unveiled a plan to rehabilitate and rebuild Sudan's refinery infrastructure, electricity networks, thermal and hydropower stations, and solar energy facilities.

He explained that the first phase accounts for 20 percent of the overall rehabilitation plan.

Sudan is simultaneously working on refinery designs and promoting investment opportunities in the sector.

The minister said a Sudanese engineering team has been in China for more than a month, working with Chinese counterparts to oversee the required designs and incorporate modern technologies.

He added that a Sudanese engineering and technical team is working to complete the first phase of the rehabilitation plan.

Meanwhile, Khartoum is seeking to attract Turkish, Belarusian and Russian investment across various stages of the energy industry, including exploration and prospecting.

Ibrahim said Sudan is also looking to attract Saudi investment in refining, particularly the proposed Port Sudan refinery, which remains under study.

Other options being examined include expanding refining capacity and developing an additional refinery in the Red Sea region, either as a reserve facility or for commercial operations.

He added that the Al-Jaili refinery in Khartoum has been offered to investors with the aim of restarting operations using the latest technologies after the damage it sustained during the war.

Electricity Needs

Ibrahim said the Ministry of Energy is working to secure electricity and energy supplies for vital sectors, including industry and agriculture.

He noted that the ministry has provided energy supplies for agricultural projects, including the Gezira Scheme.

The minister said the ministry has managed to supply Khartoum with electricity covering more than 80 percent of its needs.

However, he cautioned that fully restoring power generation capacity at stations and dams, along with the associated infrastructure, would require approximately three years.

Ibrahim emphasized that drawing on Saudi Arabia's experience in developing and improving the efficiency of electricity systems is a key area of cooperation.

He said the partnership could also include providing equipment and exchanging technical expertise to help rehabilitate damaged networks and facilities.

Shipping Disruptions

Ibrahim acknowledged that disruptions to shipping through the Strait of Hormuz and the Bab el-Mandeb Strait amid the US-Iranian war have affected energy prices in Sudan.

He attributed the impact to rising maritime insurance costs and associated price premiums.

However, he stressed that Sudan is not currently experiencing shortages of imported petroleum products.

The ministry's plan, he said, aims to secure the energy requirements of vital sectors while rehabilitating domestic facilities and strengthening refining capacity.

Ibrahim added that Sudan's participation in the International Energy Forum and the World Petroleum Congress in Saudi Arabia provided an opportunity to learn about modern technologies and solutions in energy and related industries.

He said the experience could open the door for Sudan to benefit from Saudi expertise in developing its energy sector.


SAMA Governor: Saudi Infrastructure Sustains Oil Supplies, Regional Trade Amid Conflict

Officials at the meeting of the International Monetary and Financial Committee of the International Monetary Fund in Bangkok. (X)
TT

SAMA Governor: Saudi Infrastructure Sustains Oil Supplies, Regional Trade Amid Conflict

Officials at the meeting of the International Monetary and Financial Committee of the International Monetary Fund in Bangkok. (X)

Saudi Arabia’s diversified energy infrastructure and logistics networks have enabled the Kingdom to maintain oil supplies and regional trade despite the widening economic fallout from the Middle East conflict, said Saudi Central Bank (SAMA) Governor Ayman Al-Sayari.

Addressing the International Monetary and Financial Committee (IMFC) of the International Monetary Fund in Bangkok, chaired by Saudi Finance Minister Mohammed Al-Jadaan, Al-Sayari highlighted the Kingdom’s ability to withstand the crisis, supported by prudent policies, substantial financial and nonfinancial buffers, and a well-capitalized banking sector.

He stressed Saudi Arabia’s commitment to supporting economic activity and preserving monetary and financial stability without compromising fiscal sustainability.

Al-Sayari stressed that energy security depended not only on the availability of supplies but also on their reliable and affordable delivery to international markets.

He called for sustained investment throughout the energy supply chain, from production and refining to storage and diversified transport routes, as well as across all energy sources, including oil and gas.

The conflict’s initial impact, concentrated in energy markets and major shipping corridors, had gradually spread to trade, transportation, inflation, financing conditions and investor confidence.

Disruptions had also extended beyond crude oil and natural gas to refined petroleum products, particularly transportation fuels, as well as fertilizers and essential production inputs, increasing price pressures and threatening food security and production.

While rerouting supplies and drawing down inventories had helped cushion the immediate shock, those measures had reduced the capacity to absorb further disruptions, Al-Sayari cautioned.

Banking sector withstands shocks

Turning to the domestic economy, Al-Sayari highlighted the resilience of Saudi banks, whose capital and liquidity positions remain robust, with financial soundness indicators among the strongest in the region.

He attributed the Kingdom’s ability to preserve domestic stability to decades of prudent economic management, effective risk management and strategic investment, explaining that its extensive energy and logistics infrastructure had also helped maintain oil supplies and regional commerce and mitigate the impact of disruptions in global energy markets.

He underlined that Saudi Arabia would continue adjusting its response as the conflict evolved, preserving room to address further developments while maintaining fiscal discipline.

Saudi Central Bank (SAMA) Governor Ayman Al-Sayari. (IMF)

Vision 2030 strengthens economic foundations

Al-Sayari said Saudi Vision 2030, now entering its tenth year, had reinforced the Kingdom’s economic foundations by expanding non-oil activity, increasing private sector participation and strengthening institutions and reform implementation.

He underlined the government’s commitment to productivity-enhancing reforms, greater private investment opportunities, more efficient public spending and sound public finances.

The next phase would focus on further diversification, deeper financial markets and human capital development, alongside improvements in infrastructure and institutional capacity to support sustainable and inclusive growth.

IMF urged to implement institutional reforms

On international cooperation, Al-Sayari called on the IMF to prioritize the implementation of recently reviewed institutional reforms covering economic surveillance, program design and conditionality, financial sector assessments and the debt sustainability framework for low-income countries.

Fund-supported programs should reflect individual countries’ circumstances, needs and capacity to implement reforms with conditions focused on measures essential to their success, he remarked.

He also advocated closer coordination between surveillance, lending and technical assistance, as well as timely and orderly resolution of unsustainable debt and stronger cooperation among creditors.

Al-Sayari reiterated Saudi Arabia’s support for IMF capacity development, including its $279 million pledge and backing for the Fund’s regional office in Riyadh.

He also drew attention to risks stemming from volatile capital flows, rising sovereign bond yields and the expanding role of nonbank financial institutions.

Artificial intelligence and stablecoins presented implications for both productivity and financial stability, underscoring the importance of strengthening analysis and oversight to address emerging risks, he noted.


Asian Shares are Mixed with Tech Stocks Volatile, and Oil Falls on Trump's Russian Sanctions Waiver

Passersby walk past a stock market indicator board in Tokyo, Japan, 15 October 2026. EPA/FRANCK ROBICHON
TT

Asian Shares are Mixed with Tech Stocks Volatile, and Oil Falls on Trump's Russian Sanctions Waiver

Passersby walk past a stock market indicator board in Tokyo, Japan, 15 October 2026. EPA/FRANCK ROBICHON

Asian shares were mixed Monday as volatility in technology stocks persisted, while US equity futures edged higher ahead of another week of American corporate earnings results.

Oil prices fell more than 1% after US President Donald Trump’s decision to waive sweeping sanctions on Russia, including on Russian energy, The Associated Press said.

A sell-off of technology shares from Asia to Wall Street recently put downward pressure on stock markets, as investor concerns grow over the sustainability of the artificial intelligence boom.

South Korea’s benchmark Kospi index was up 1.1% to 5,729.58 on Monday, after falling sharply last week. The Kospi is down more than 18% over the past month, and still well below the 9,000 mark it crossed in June at its peak on the global AI frenzy.

Samsung Electronics was up 0.7%, while memory chipmaker SK Hynix fell 0.9%.

Japan’s Nikkei 225 lost 0.8% to 64,799.03. Japanese chip equipment maker Tokyo Electron lost 2.1%, and OpenAI investor SoftBank Group dropped 3.6%.

Hong Kong’s stock market was closed because of a holiday. The Shanghai Composite index edged 0.2% higher to 3,722.20, after China reported better-than-expected growth of 4.5% for its economy in the July-September quarter.

CXMT, China’s leading memory chipmaker, fell more than 7% despite the company forecasting a strong profit for the first nine months.

Taiwan’s Taiex fell 1%. Shares of Taiwan Semiconductor Manufacturing Co., or TSMC, the world’s biggest contract chipmaker, were down 0.6%.

Australia’s S&P/ASX 200 was 0.3% higher at 8,832.20.

India’s Sensex edged down 0.1%.

Indonesia’s benchmark stock index fell another 5% to its lowest level since 2020, after it plunged over 11% on Friday following a warning from index provider MSCI that it would downgrade the country from its “emerging market” status.

On Friday, Wall Street’s benchmark S&P 500 declined 1.1%. The Dow Jones Industrial Average fell 0.3%, and the technology-heavy Nasdaq composite sank 2.1%.

Investors this week are watching for more big corporate earnings results from the US, including Meta, Netflix, General Motors, Tesla and IBM. Strong company earnings have been one factor that’s been keeping US stocks robust lately.

Oil prices were down early Monday, with Brent crude, the international standard, falling 1.8% to $107.86 per barrel.

Benchmark US crude dropped 1.6% to $97.43 per barrel.

Oil fell after Trump on Friday signed an executive order to put new broad US sanctions against Russia on hold just days before they were to come into effect, drawing disappointment from Ukraine, with the move likely resulting in more energy exports from Russia.

Trump's decision came not long after he said earlier this month he had reached a diesel deal with Russia in an attempt to bring down elevated US fuel prices ahead of the Nov. 3 midterm elections.

But even with the decline, oil prices have remained elevated compared with those seen before the Iran war. Global oil supply risks are still high amid tensions in the Middle East, including uncertainty surrounding oil transport in the Strait of Hormuz, adding upward pressure to prices.

The US dollar fell slightly to 158.09 Japanese yen from 158.10 yen. The euro was trading at $1.1231, down from $1.1234.