Developing Countries Swapping Out of Dollar Debt

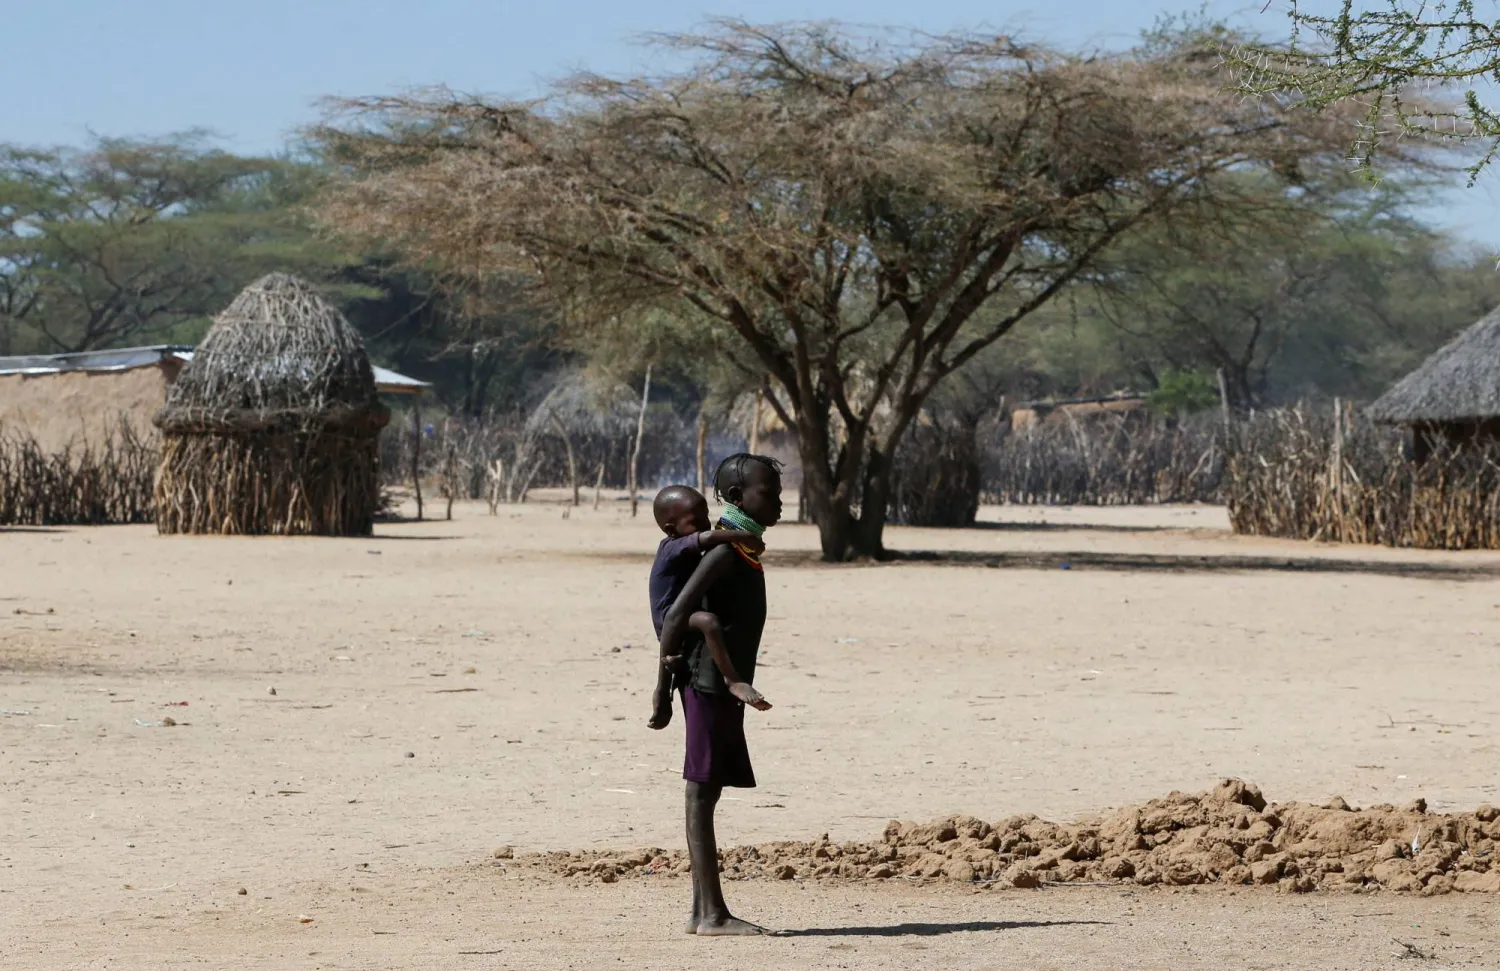
FILE PHOTO: A child affected by the worsening drought due to failed monsoon seasons, carries her sibling as they stand near their makeshift shelter within Sopel village in Turkana, Kenya September 27, 2022. REUTERS/Thomas Mukoya/File Photo
TT

Developing Countries Swapping Out of Dollar Debt

FILE PHOTO: A child affected by the worsening drought due to failed monsoon seasons, carries her sibling as they stand near their makeshift shelter within Sopel village in Turkana, Kenya September 27, 2022. REUTERS/Thomas Mukoya/File Photo

Developing countries are moving out of dollar debts and turning to currencies with rock bottom interest rates such as the Chinese renminbi and Swiss franc, The Financial Times reported.

It said the shift, embarked upon by indebted countries including Kenya, Sri Lanka and Panama, reflects the higher rates set by the US Federal Reserve, which have angered President Donald Trump as well as increasing other countries’ debt servicing costs.

“The high level of interest rates and a steep US Treasury yield curve... has made USD financing more onerous for [developing] countries, even with relatively low spreads on emerging market debt,” said Armando Armenta, vice-president for global economic research at AllianceBernstein.

“As a result, they are seeking more cost-effective options.”

But he described many such shifts to cheaper, non-dollar financing as “temporary measures” by countries that had to “focus on lowering their financing needs."

A switch to renminbi borrowing — which comes as the Chinese currency hits its highest level against the dollar this year — is also a consequence of Beijing’s $1.3tn belt-and-road development program, which has lent hundreds of billions of dollars for infrastructure projects to governments across the globe.

While overall figures for new renminbi borrowing are not widely available, since Beijing bilaterally negotiates loans with other governments, Kenya and Sri Lanka are seeking to convert high-profile dollar loans into the currency.

Kenya’s treasury said in August it was in talks with China ExIm Bank, the country’s biggest creditor, to switch to renminbi repayments on dollar loans for a $5bn railway project weighing down its budget.

Sri Lanka’s president also told parliament last month his government was seeking lending in renminbi to complete a key highway project that stalled when the country defaulted in 2022.

With the benchmark US federal funds rate at a range of 4.25 percent to 4.5 percent — far higher than equivalent rates set by other major central banks — the outright cost of new borrowing in dollars is relatively high for many developing nations — even if spreads for such debt are at their lowest premiums over US Treasuries in decades.

The Swiss National Bank cut rates to zero in June while China’s benchmark seven-day reverse repo rate is 1.4 percent. “It seems that the cost of funding might be the reason for conversion into renminbi,” said Thilina Panduwawala, economist at Colombo-based Frontier Research.

Many “Belt and Road” loans of the 2010s were in dollars, at a time when US interest rates were far lower. The cost for both Kenya and Sri Lanka of such debt has since risen markedly, increasing the incentive to shift away from dollar financing. By borrowing in currencies such as the renminbi and the Swiss franc, countries can access debt at much lower interest rates than those offered by dollar bonds.

But Yufan Huang, fellow at the China-Africa Research Initiative at Johns Hopkins University, argued that progress for Beijing’s wider efforts to adopt lending in the currency remained limited.

“Even now, when renminbi rates are lower, many borrowers remain hesitant,” he said. “For now, this looks more like a case-by-case operation, as with Kenya.”

Since governments rarely have export earnings in currencies such as the renminbi and Swiss franc, they also may have to hedge their exposure to exchange rates through derivatives.

Panama tapped the equivalent of nearly $2.4bn in Swiss franc loans from banks in July alone, as the Central American nation’s government battled to contain its fiscal deficit and avoid a downgrade in its credit rating to junk status.

Felipe Chapman, Panama’s finance minister, said the access to cheaper financing saved more than $200mn compared with issuing debt in dollars and that the new loans had been hedged.

He added that the country had “diversified” its sovereign debt management into both euros and Swiss francs “instead of relying solely on US dollar capital markets.”

Colombia also appears to be moving towards Swiss franc loans to refinance dollar bonds.

Last week, a group of global banks launched an offer to buy discounted Colombian bonds in what investors saw as part of arranging a Swiss franc loan to the government that would use the existing debt as collateral.

While Bogotá has yet to confirm such a loan, the country’s finance ministry signaled plans to diversify its external currency borrowing in June, The Financial Times reported.

Andres Pardo, head of Latin America macro strategy at XP Investments, said Colombia could borrow at low Swiss-based rates of 1.5 percent to buy back dollar debts that have yields of 7 to 8 percent, and local peso bonds paying up to 12 percent.

The country’s local currency debt was downgraded to junk by S&P that month after the government suspended a key fiscal rule.

Investors said Swiss franc issuance by governments could help limit interest bills, but in the long run such borrowing cannot replace access to the larger public market for dollar bonds.

“They are helpful to underlying fundamentals, if you are cleaning up your maturity profile...however, we need to see that policymakers are making improvements to open up [dollar] markets to them again,” said one emerging markets debt fund manager.

Companies in emerging markets are also selling more bonds in euros this year, with the amount of this debt in issue rising to a record $239bn as of July, according to JPMorgan. The overall stock of emerging market corporate bonds in dollars totals about $2.5tn.

“This year’s euro issuance is growing more than we see in dollar issuance,” said Toke Hjortshøj, senior portfolio manager at Impax Asset Management. Asian issuers account for a third of the outstanding euro stock, up from 10 to 15 percent 15 years ago, he added.


ECB Says Will Have to Act Again if 2nd-round Inflation Effects Appear

European Central Bank (ECB) President Christine Lagarde (CL) and Gabriel Makhlouf (CR), Governor of the Central Bank of Ireland during the family photo at the Informal meeting of EU Finance Ministers in Dublin Castle, Dublin, Ireland 18 September 2026. EPA/BRYAN MEADE
TT

ECB Says Will Have to Act Again if 2nd-round Inflation Effects Appear

European Central Bank (ECB) President Christine Lagarde (CL) and Gabriel Makhlouf (CR), Governor of the Central Bank of Ireland during the family photo at the Informal meeting of EU Finance Ministers in Dublin Castle, Dublin, Ireland 18 September 2026. EPA/BRYAN MEADE

European Central Bank will have to raise interest rates again if high energy prices feed through to other areas but so far there is no sign of such second-round inflation effects, ECB policymaker ⁠Gabriel Makhlouf said on ⁠Wednesday.

"Although inflation is above our target, we're not seeing the sorts of second round effects ⁠that start feeding through to prices," Makhlouf, Ireland's central bank chief, told national broadcaster RTE in an interview.

"If that happens (energy prices remain high and feed into other areas), we will have to take ⁠action ⁠again to meet our target."

Makhlouf cautioned earlier this month following the ECB's second interest rate hike this year that raising interest rates "a great deal more" risked damaging economic growth.

Also Wednesday, the ECB said the European Union could close a third of its productivity gap with the United States if it had as many large companies, adding its voice to calls for reforms that make it easier for businesses to scale up.

European policymakers are trying to tackle the EU's economic underperformance relative to the United States, which is home to many of the world's largest companies and is leading the race to develop artificial intelligence.

EU workers produce ⁠20% less output ⁠per hour than their US counterparts, according to academic studies. They were almost on an even keel in 1995.

ECB staff found that if Europe had the same distribution of large and small firms as the United States – without changing how productive each ⁠type of company is – the productivity gap would shrink by roughly one-third.

Large firms are significantly more productive than smaller ones. Companies with at least 250 employees generate an average of €86,800 in value added per worker annually, while firms with fewer than 10 employees produce less than half that amount.

The ECB said Europe's weaker productivity performance also reflects lower innovation, fragmented regulation and less developed capital markets, all of which ⁠make it ⁠harder for companies to grow and compete internationally.

The central bank backed the proposed "EU Inc" framework, an EU-wide corporate law regime aimed at reducing barriers to cross-border business activity.

Modelled loosely on Delaware's corporate framework in the United States, EU Inc would create a single legal structure operating across the bloc, bypassing a patchwork of 27 national company law systems and dozens of corporate forms.

"EU Inc. has the potential to support the Single Market, by strengthening competition, innovation and productivity growth," the ECB said.


Surveys: Europe's Economy Surprisingly Resilient amid War-Driven Energy Shock

A view of the European Parliament in Brussels, Belgium, 23 September 2026. EPA/OLIVIER HOSLET
TT

Surveys: Europe's Economy Surprisingly Resilient amid War-Driven Energy Shock

A view of the European Parliament in Brussels, Belgium, 23 September 2026. EPA/OLIVIER HOSLET

Europe's economy is showing unexpected signs of health even as conflicts in the Middle East and Ukraine drive up energy costs for firms and households, key business surveys showed on Wednesday.

Business activity across the euro zone accelerated in September at its fastest rate in over three years, S&P Global said, with solid growth registered across both the manufacturing and service sectors.

The S&P Global Flash Euro Zone Composite PMI Output Index — where readings above 50.0 signal an expansion in activity — jumped to 53.1 in September from August's 52.0, defying expectations in a Reuters poll ⁠for a dip ⁠to 51.7. The highest forecast in the poll was for 52.6.

"All in all, today’s PMI readings are almost too good to be true," said Carsten Brzeski at ING.

"A euro zone economy that remains completely unharmed by an energy price shock and supply chain disruptions is a welcome surprise. Let’s hope it doesn’t turn out to be a mirage."

S&P said the latest rise in output was broad based across geographies covered by its data.

Business activity in Germany, Europe's largest ⁠economy, expanded solidly in September despite firms facing increased inflationary pressures while in France it grew at its fastest pace in just over two years, driven by a rebound in services demand.

But in Britain, outside the European Union, growth cooled this month as inflation pressure built, its PMI showed, an awkward backdrop for finance minister John Healey ahead of his first budget next month.

Overall new orders in the currency union surged at their fastest pace in over four years supported by a further rise in exports — which include intra-euro zone trade.

The bloc's services PMI bounced to its highest in nearly a year and was well ahead of estimates for a fall, while the manufacturing index held steady.

A gauge of output - ⁠which feeds into ⁠the composite PMI - nudged higher.

To meet the rise in demand firms took on more staff but faced a jump in input costs due to elevated energy prices stemming from the US war with Iran. They were able to pass some of this on to customers.

"September’s big improvement in the euro zone’s composite PMI supports our view that despite the weakness in the official activity data in July, GDP will increase in Q3," said Jack Allen-Reynolds at Capital Economics. "The output price PMIs rose too, but there is still no sign of 'second-round' effects on wages."

Earlier this month the European Central Bank raised interest rates for the second time this year to quell an energy-driven inflation rise and warned price pressures could prove lasting.

Markets are pricing three more ECB rate hikes by the end of June 2027.

"Today's PMI readings make it more difficult for even the ECB's most dovish policymakers to rule out another rate hike," said ING's Brzeski.


What Do Saudi SMEs Need to Grow?

What Do Saudi SMEs Need to Grow?
TT

What Do Saudi SMEs Need to Grow?

What Do Saudi SMEs Need to Grow?

Financing alone is no longer enough to propel Saudi Arabia’s small and medium-sized enterprises into their next phase of growth, as their needs increasingly extend to accessing markets and contracts, securing operating liquidity, reducing business costs and boosting productivity, competitiveness and their ability to expand.

Financing available to the sector has nevertheless continued to grow. Cumulative credit facilities extended to micro, small and medium-sized enterprises reached about SAR 467 billion ($124.5 billion) by the end of 2025, up 33% year on year.

At the same time, Saudi Arabia’s National Strategy for Entrepreneurship and SMEs is seeking to address challenges beyond the financing gap by improving access to markets, procurement and supply chains, reducing the cost of doing business and strengthening companies’ capacity for sustainable growth.

In the latest financing initiative, the Small and Medium Enterprises General Authority, known as Monsha’at, signed a cooperation agreement with STC Bank in September 2026 for a financing portfolio of up to SAR 5 billion ($1.33 billion) for micro, small and medium-sized enterprises.

The portfolio includes short-, medium- and long-term facilities covering working capital, operating needs, purchases of assets and equipment, and financing for contracts, projects and supply chains.

Businesses also require more than long-term financing. The Social Development Bank’s Working Capital product offers financing ranging from SAR 150,000 ($40,000) to SAR 10 million ($2.67 million), with repayment periods of up to 12 months, to cover day-to-day operating costs and strengthen cash-flow management.

The bank distinguishes between working-capital financing for operating costs and capital-expansion financing for assets and expansion.

From financing to growth

Rayan bin Ibrahim Alfayez, Monsha’at’s deputy governor for enterprise services, said the 13 initiatives under the National Strategy for Entrepreneurship and SMEs are designed to directly address priority challenges facing business growth and create a more efficient environment that supports expansion and sustainability while strengthening competitiveness in the coming period.

Alfayez explained that one initiative aimed at expanding opportunities for businesses focuses on empowering SMEs and startups in industrial cities and special economic zones. It seeks to help them capitalize on opportunities available in those areas and provide support and incentives suited to the nature of their businesses, supporting their growth and strengthening their presence in industrial and economic activities and value chains.

He added that the strategy also includes an initiative to increase SMEs’ share of procurement by large companies, broadening their access to opportunities and contracts, strengthening their participation in supply chains and helping build sustainable commercial relationships that support business growth and expansion.

Alfayez noted that another initiative aimed at reducing the cost of doing business addresses one of the challenges affecting enterprise growth by examining fees and requirements in coordination with the relevant authorities and developing mechanisms to support fees based on carefully considered criteria. The initiative is intended to ease the financial burdens associated with doing business and create a more favorable environment for companies’ growth and sustainability.

He said the initiatives work together to address a range of factors linked to business growth, from the operating environment to opportunities, markets and value chains, strengthening SMEs’ ability to grow and expand while increasing their competitiveness and contribution to the national economy.

Markets after financing

Financial and economic adviser Hussein Al-Attas told Asharq Al-Awsat that the increase in financing directed toward SMEs reflected clear progress in Saudi Arabia’s financing ecosystem, but the challenge was no longer financing alone. Rather, it was an enterprise’s ability to turn that financing into sustainable growth.

Al-Attas explained that an enterprise needs three interconnected elements: appropriate financing, access to markets, and operational and competitive capacity.

He said a company may secure financing, but in the next stage it needs contracts and sales opportunities that allow it to increase revenue, alongside managerial and technological development to boost productivity and the ability to manage cash flows and expand without allowing growth to become a financial burden.

Al-Attas added that access to markets and contracts represents the link most closely associated with an enterprise’s transition from survival to growth. Financing gives a business the capacity to act, while contracts and markets turn that capacity into revenue and cash flow.

He further stated that greater SME participation in government procurement and the supply chains of large companies, along with opening export channels, could have a direct impact on their ability to expand, alongside efforts to reduce the cost of doing business and raise productivity.

The next phase requires moving from the concept of “financing the enterprise” to “financing the enterprise’s growth,” he underlined, meaning that financing should be linked to markets, contracts, technology, productivity and expansion.

Strategy broadens its scope

The focus on markets forms part of the wider National Strategy for Entrepreneurship and SMEs, which includes 13 initiatives addressing sector challenges in access to markets and opportunities, financing, the business environment, innovation, data and expansion.

The strategy also aims to raise SMEs’ contribution to gross domestic product to 35% by 2030 and create more than 500,000 direct and indirect jobs.

Some initiatives seek to turn market access from a broad objective into direct contracting opportunities by qualifying enterprises and connecting them with the supply chains of large companies and projects.

This approach is reflected in Monsha’at’s Jadeer service, which aims to improve businesses’ readiness, qualify them to enter supply chains and enable them to benefit from procurement opportunities.

The equation for SME growth therefore does not stop at increasing available financing. It also depends on businesses’ ability to use that financing first to fund operations, then gain access to demand and contracts, improve productivity and reduce costs before moving into expansion and investment.

This reflects a shift from addressing the financing gap to addressing the growth gap: liquidity gives an enterprise the ability to continue operating and move forward, while access to markets and operational efficiency determine its ability to turn financing into revenue and sustainable growth.