Alternative Routes for Middle East Oil and Gas Due to Hormuz Disruption

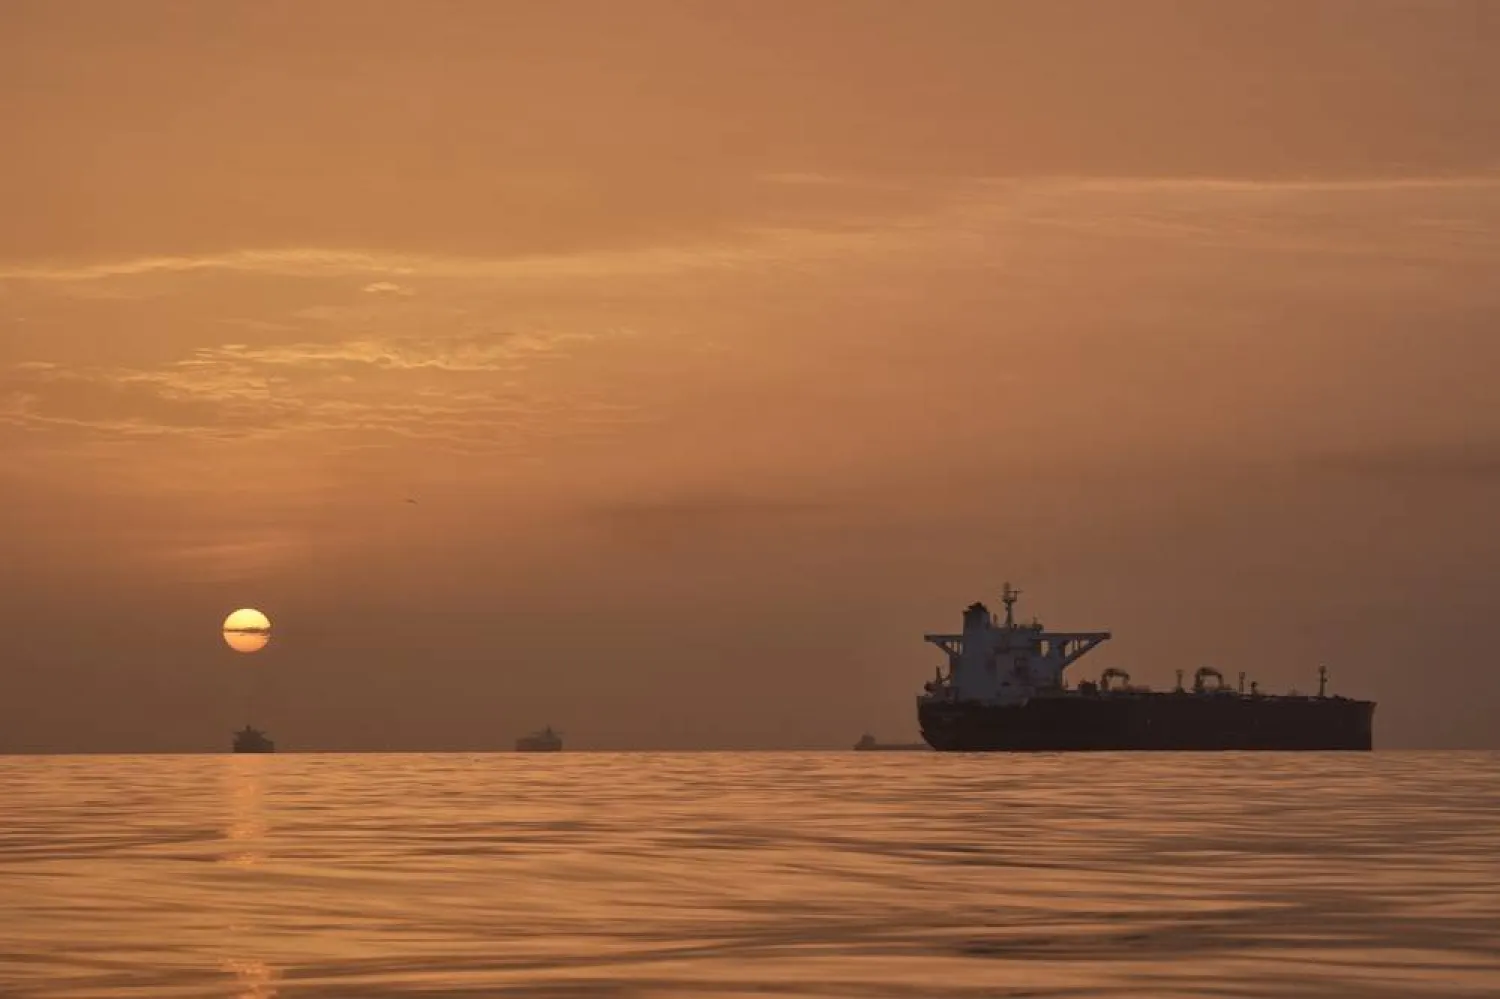
 The sun rises behind tankers anchored in the Strait of Hormuz off the coast of Qeshm Island, Iran, Saturday, April 18, 2026. (AP)
The sun rises behind tankers anchored in the Strait of Hormuz off the coast of Qeshm Island, Iran, Saturday, April 18, 2026. (AP)
TT

Alternative Routes for Middle East Oil and Gas Due to Hormuz Disruption

 The sun rises behind tankers anchored in the Strait of Hormuz off the coast of Qeshm Island, Iran, Saturday, April 18, 2026. (AP)
The sun rises behind tankers anchored in the Strait of Hormuz off the coast of Qeshm Island, Iran, Saturday, April 18, 2026. (AP)

The US-Israeli war with Iran has disrupted shipping through ‌the Strait of Hormuz, the world's most important oil chokepoint, exposing the Middle East's limited alternatives for exporting its hydrocarbons.

The International Energy Agency (IEA) called it the largest supply disruption on record, bigger than the oil shocks of the 1970s and the loss of Russian pipeline gas after Moscow's invasion of Ukraine combined.

These are the existing and possible alternative oil and gas export bypasses of the Strait of Hormuz:

EXISTING PIPELINES:

EAST–WEST PIPELINE (SAUDI ARABIA)

Saudi Arabia's 1,200-km East–West pipeline can transport up to 7 million barrels per day (bpd) of crude to the Red Sea port of Yanbu, with effective exports estimated at around 4.5 million bpd, depending on tanker and jetty availability.

From Yanbu, shipments can travel ‌to Europe via ‌the Suez Canal or south via the Bab el-Mandeb ‌strait ⁠to reach Asia, ⁠a route carrying security risks from Yemen's Houthi militants, who have attacked tankers during the Gaza war.

HABSHAN–FUJAIRAH PIPELINE (UAE)

The Abu Dhabi Crude Oil Pipeline (ADCOP) runs from Abu Dhabi's Habshan onshore fields to Fujairah on the Gulf of Oman, outside Hormuz. Operated by ADNOC and commissioned in 2012, the 360-km pipeline has capacity of about 1.5–1.8 million bpd. Oil loadings at Fujairah, however, have been affected by drone attacks since the Iran war started ⁠at the end of February.

KIRKUK-CEYHAN PIPELINE (IRAQ- TÜRKIYE)

Iraq's main northern export route ‌runs from Kirkuk to Türkiye's Mediterranean port of ‌Ceyhan via the Kurdistan region. The pipeline restarted last September after a 2-1/2-year shutdown following an ‌interim deal between Baghdad and the Kurdistan Regional Government. On March 17, Iraq began ‌pumping 170,000 bpd, with plans to reach 250,000 bpd, after Iraq's national oil company SOMO signed export contracts via Türkiye, Jordan and Syria.

GOREH-JASK PIPELINE

Iran may be able to utilize the Jask terminal, fed by the 1 million bpd Goreh-Jask pipeline, to bypass the Strait, the ‌IEA said in its latest oil market report. The construction of the terminal is not fully complete but a loading ⁠from Jask was tested ⁠in 2024, it said.

POSSIBLE ALTERNATIVE ROUTES:

IRAQ–OMAN PIPELINE Iraq said last September it was considering a pipeline from Basra to Oman’s port of Duqm on the Gulf of Oman.

The project remains at an early conceptual stage, with routes under study including an overland line via neighboring countries or a costly subsea pipeline.

IRAQ–JORDAN PIPELINE

The proposed 1 million bpd pipeline would ship crude from Basra to Jordan's Red Sea port of Aqaba, bypassing Hormuz.

First proposed in the 1980s and approved in principle in 2022, the project remains stalled by cost, security and political hurdles.

GULF–SEA OF OMAN CANAL

A canal bypassing Hormuz - similar to the Suez or Panama Canals - remains purely conceptual. A project to cut through the Hajar Mountains toward Fujairah would face extreme engineering challenges and could cost hundreds of billions of dollars.


Georgieva: More Work Needed on Lebanon Program

IMF Managing Director Kristalina Georgieva speaks during the Annual Meetings Plenary at the Annual Meetings of the International Monetary Fund (IMF) and the World Bank Group (WBG) at the Queen Sirikit National Convention Center (QSNCC) in Bangkok on October 16, 2026. (Photo by Lillian SUWANRUMPHA / AFP)
TT

Georgieva: More Work Needed on Lebanon Program

IMF Managing Director Kristalina Georgieva speaks during the Annual Meetings Plenary at the Annual Meetings of the International Monetary Fund (IMF) and the World Bank Group (WBG) at the Queen Sirikit National Convention Center (QSNCC) in Bangkok on October 16, 2026. (Photo by Lillian SUWANRUMPHA / AFP)

International Monetary Fund Managing Director Kristalina Georgieva said on Saturday that ‌there were "intense" ‌discussions on support ‌for Lebanon ⁠reflecting significant progress ⁠towards a loan program.

"In the case ‌of ‌Lebanon, we are ‌in very intense ‌discussions with the Lebanese authorities," Georgieva told a closing news conference at ‌IMF and World Bank annual meetings in ⁠Bangkok.

"We ⁠have made significant progress towards the program. We have still a bit more work to do together, and I'm confident we will be successful."


Al-Jadaan: Wars and Supply Disruptions Heighten Risks to Global Economy

Al-Jadaan during his participation in the meeting of Arab governors with the President of the World Bank Group on Friday (X)
TT

Al-Jadaan: Wars and Supply Disruptions Heighten Risks to Global Economy

Al-Jadaan during his participation in the meeting of Arab governors with the President of the World Bank Group on Friday (X)

Saudi Arabia's Finance Minister Mohammed Al-Jadaan, Chair of the International Monetary and Financial Committee (IMFC), said that ongoing wars, conflicts and supply chain disruptions were imposing significant human and economic costs worldwide and adding to price pressures, particularly in the poorest and most vulnerable countries.

In remarks at the Committee's 54th meeting in Bangkok, Jadaan stressed the need to strengthen economic and financial stability, step up international cooperation and end conflicts to achieve sustainable growth and long-term stability.

A statement issued following the Committee’s meeting said the global economy had weathered a series of recent shocks better than expected, but warned that the buffers underpinning its resilience had eroded, making its continued resilience uncertain.

The statement cautioned that escalating conflicts, trade tensions, rising public debt and higher refinancing costs could exacerbate economic and financial vulnerabilities, as economies undergo rapid structural transformations driven by technological advances, demographic shifts and climate risks.

The Committee stressed the need to address fiscal vulnerabilities, strengthen debt sustainability, and protect the most vulnerable groups and investments that support productivity and growth. It also underscored the importance of central bank independence, secure energy flows, freedom of navigation and enhanced international cooperation to address economic and financial challenges.

The Committee commended Saudi Arabia’s leadership and welcomed the extension of Al-Jadaan’s term as chair for one year.

It said the global economy had weathered recent shocks better than expected but warned that the buffers underpinning its resilience had eroded, making its continued resilience uncertain.

Wars and conflicts continue to impose immense humanitarian burdens and significant economic costs, while supply chain disruptions and trade tensions heighten uncertainty and price pressures.

Conversely, rapid advancements in advanced artificial intelligence technologies have contributed to supporting investment and trade, with the potential to boost productivity. The Committee explained that these developments have so far coincided with generally stable global growth, but economic gains remain uneven, while low-income countries and fragile states face the risk of widening the gap between them and other economies.

The Committee warned that risks are skewed to the downside, noting that escalating conflicts and trade tensions could disrupt vital trade routes and increase pressure on commodity prices, including refined energy products, in addition to exacerbating risks to energy and food supply security.

It also cautioned that rising sovereign bond yields in systematically important economies could affect global financial conditions, especially given high levels of public debt and refinancing needs in many countries. These pressures, along with the uncertainty surrounding the impact of advanced artificial intelligence technologies on the economy and financial sector, could further increase economic and financial vulnerabilities.

It added that accelerating technological transformations, demographic changes, increasing extreme weather events and natural disasters, as well as geoeconomic fragmentation, further complicate the choices and tradeoffs facing policymakers.

Fiscal Consolidation

The Committee emphasized that strengthening economic and financial stability requires sound and consistent macroeconomic policies and multilateral cooperation, supporting strong and broad-based growth.

It called for urgently addressing fiscal vulnerabilities and advancing efforts to consolidate spending and revenue, supported by credible medium-term fiscal frameworks, to ensure fiscal and debt sustainability and rebuild precautionary buffers, in line with each country's circumstances. At the same time, it stressed the need to protect the most vulnerable groups and priority investments that foster productivity and growth.

Regarding monetary policy, the Committee reaffirmed central banks' commitment to ensuring price stability in line with their mandates, while continuing to adjust policies based on data and clear communication regarding decisions. It emphasized that central bank independence is a fundamental pillar for policy credibility and maintaining stable inflation expectations.

It also underscored the importance of adhering to international standards and closely monitoring and addressing vulnerabilities and risks threatening financial stability. It welcomed the "Bangkok Blueprint," which aims to strengthen safeguards related to digital finance, enhance resilience against cyberattacks, and advance international efforts to combat digital fraud.

Concerning growth and productivity, the Committee called for continuing reforms that enhance the role of the private sector and leveraging advanced artificial intelligence technologies and digital transformation to boost productivity, while addressing the risks associated with these technologies and expanding the scope of their benefits.

It further stressed the necessity of international cooperation to address global challenges and ensure the stability and effective functioning of the international monetary system, tackle excessive global imbalances and trade tensions, avoid distortionary policies, and enhance supply chain resilience through reforms that consider each country's circumstances and multilateral cooperation, thereby supporting a fair and open global economy.

Regarding energy, the Committee emphasized the importance of ensuring safe and reliable energy flows and upholding the principle of freedom of navigation, considering them essential elements for global economic stability. It also reaffirmed adherence to the exchange rate commitments outlined in the April 2021 understanding.

Supporting Heavily Indebted Countries

The Committee also stressed the importance of assisting countries in implementing reforms and addressing debt-related vulnerabilities through sound macroeconomic policies, domestic resource mobilization, and improved governance.

It paid particular attention to the challenges facing low-income countries and the most vulnerable middle-income countries, including fragile and conflict-affected states and small developing states.

Regarding sovereign debt, the Committee stressed the need to continue improving restructuring operations, including within the "Common Framework," building on progress made, and advancing work at the "Global Sovereign Debt Roundtable" to ensure the orderly, coordinated, timely, and predictable implementation of restructuring operations.

It also called on all stakeholders, including private sector creditors, to enhance debt transparency.

The Committee encouraged increased support for countries with sustainable debt, strong reform programs, and robust growth plans, but which face short-term financing challenges, by accelerating the implementation of the IMF and World Bank Group's three-pillar approach.

It expressed gratitude to members who provided necessary assurances to support the self-sustaining lending capacity of the Growth and Poverty Reduction Trust Fund, looking forward to other members promptly providing the required guarantees.

IMF Reforms

The Committee welcomed the Managing Director of the International Monetary Fund's Global Policy Agenda and the recent approval of a comprehensive set of policy reviews aimed at strengthening economic surveillance, debt analysis, lending, and capacity development.

It called for the swift and effective implementation of these reforms, ensuring their fair and consistent application among members, and supported strengthening the integration between capacity development, economic surveillance, and lending.

It clarified that these changes would help countries identify risks, manage uncertainty, and implement sound policies and reliable frameworks, thereby enhancing resilience and supporting growth.

It also welcomed the Fund's work on the macroeconomic and policy-related implications of advanced artificial intelligence technologies, looking forward to further analysis and advice in this area within the institution's mandate.

Increasing Fund Resources

The Committee reiterated the importance of a strong, quota-based, and adequately resourced International Monetary Fund to ensure its continued pivotal role in the global financial safety net.

It called for the completion of necessary domestic approvals for the quota increase under the Sixteenth General Review of Quotas without further delay.

It also noted that the Diriyah Guidelines will provide a basis for future discussions on quota and governance reforms, including within the framework of the Seventeenth General Review of Quotas.

Modernizing Fund Operations and Enhancing Representation of Women and Regions

The Committee supported the International Monetary Fund's efforts to modernize its operations, strengthen institutional risk management, and invest in its staff, thereby maintaining its flexibility, responsiveness, and readiness for future requirements, including through the thoughtful internal use of advanced artificial intelligence technologies.

It expressed its appreciation for the work and efforts undertaken by Fund staff, within a merit-based system, and called for further improving the representation of regions and women in positions within the institution.

It also emphasized the importance of enhancing the representation of women on the Fund's Executive Board and in leadership positions within the Board, and affirmed the necessity of taking the required measures to achieve the voluntary goals adopted in this area.

It further stressed that the selection of all candidates should be based on the merit criteria adopted by each member country.

Finally, the Committee noted that its next meeting is expected to be held in Washington D.C. in April 2027.


Pakistan Says Attacks on Gulf Energy Infrastructure 'Worrying' for Outlook

Pakistan Finance Minister Muhammad Aurangzeb gestures during a Reuters interview in the IMF/World Bank 2026 Annual Meetings at the Queen Sirikit National Convention Center (QSNCC) in Bangkok, Thailand, October 12, 2026. REUTERS/Patipat Janthong
TT

Pakistan Says Attacks on Gulf Energy Infrastructure 'Worrying' for Outlook

Pakistan Finance Minister Muhammad Aurangzeb gestures during a Reuters interview in the IMF/World Bank 2026 Annual Meetings at the Queen Sirikit National Convention Center (QSNCC) in Bangkok, Thailand, October 12, 2026. REUTERS/Patipat Janthong

Pakistan's finance minister on Saturday told AFP the country had so far withstood the shock from skyrocketing energy prices due to the Iran war, but that attacks on infrastructure in Saudi Arabia and other Gulf countries were "worrying" for the country's longer-term economic outlook.

In an interview on the sidelines of the IMF-World Bank Annual Meetings in Bangkok, Muhammad Aurangzeb said the South Asian country had procured enough energy supplies to last through November, and was now planning for the winter months, when household needs typically spike.

"The first-order impact has been negotiated well by Pakistan," he said.

"We've had no shortage, no queues at the gas stations, and no law and order situation, which at times we have seen in some of the countries."

He added that unless the government saw "an absolute dire need", it would not be procuring spot cargoes on the LNG front, which tend to be far more expensive than previously contracted shipments.

Since the United States and ally Israel launched the war on Iran in February, global energy prices have surged as Tehran's retaliatory action has targeted Washington's Gulf allies and curtailed oil and gas supplies.

With Yemen's civil war flaring back to life as well, the Houthis there have repeatedly attacked Saudi infrastructure, including energy facilities and airports, in recent days.

Aurangzeb expressed alarm at the escalation, saying damage to such sites would delay a return to economic normalcy.

"What is now (the) worrying part of it is when the energy infrastructure starts getting hit," he said.

"I, to be very honest, I don't know where that would go. But one thing is very clear: that if the infrastructure continues to get hit, the return to normalcy, even if things subside, will take longer."

- 'Pushback' -

Pakistan has been a frequent customer at the International Monetary Fund (IMF), the lender of last resort to countries on the brink of default.

It is currently in the midst of its 25th program with the Fund -- at least 11 of which have been outright bailouts -- since gaining independence in 1947.

The current program totals around $7 billion over three years, with the Fund reaching an agreement this month to release a $1.2 billion tranche.

With global debt stocks running high, the Fund has called at this year's annual meetings on all economies, even those most vulnerable to the Iran war shock, to engage in fiscal consolidation to avoid a potential crisis.

"Fortunately for us, we have been on this fiscal consolidation path for a while," Aurangzeb said with a rueful smile.

The country's tax revenues have grown significantly in recent years, and the finance minister said the government was targeting the theft of taxes by private sector businesses that collected sales tax from consumers but never deposited it in government accounts.

Such theft accounted for billions of dollars, Aurangzeb said, adding that there remained "room for improvement" on increasing income tax collection as well.

He said the government's reform agenda had faced resistance from industry, lobbying groups and vested interests.

"Every reform, everything that you try to do when you try to change the status quo, there is pushback," he said.

One of the major pillars of the IMF's program criteria is privatizing state-owned assets in Pakistan, where the military runs a vast empire of businesses in sectors from real estate to fertilizer.

Asked about those companies, Aurangzeb denied that they were receiving state funding.

"As far as we are concerned, whichever commercial enterprises (the military) are running, they are running on a standalone basis and profitable on their own basis," he said.

"So, I can confirm to you, we are not providing any funds from the exchequer."

Pakistan's military has directly ruled the country for roughly two-fifths of its history, and under current army chief Field Marshal Asim Munir it has tightened its grip over key pillars of power, even as a civilian government remains nominally in charge of the state.