Saudi Aramco Chief: Any Interruption Can be Fixed 'Within Days'

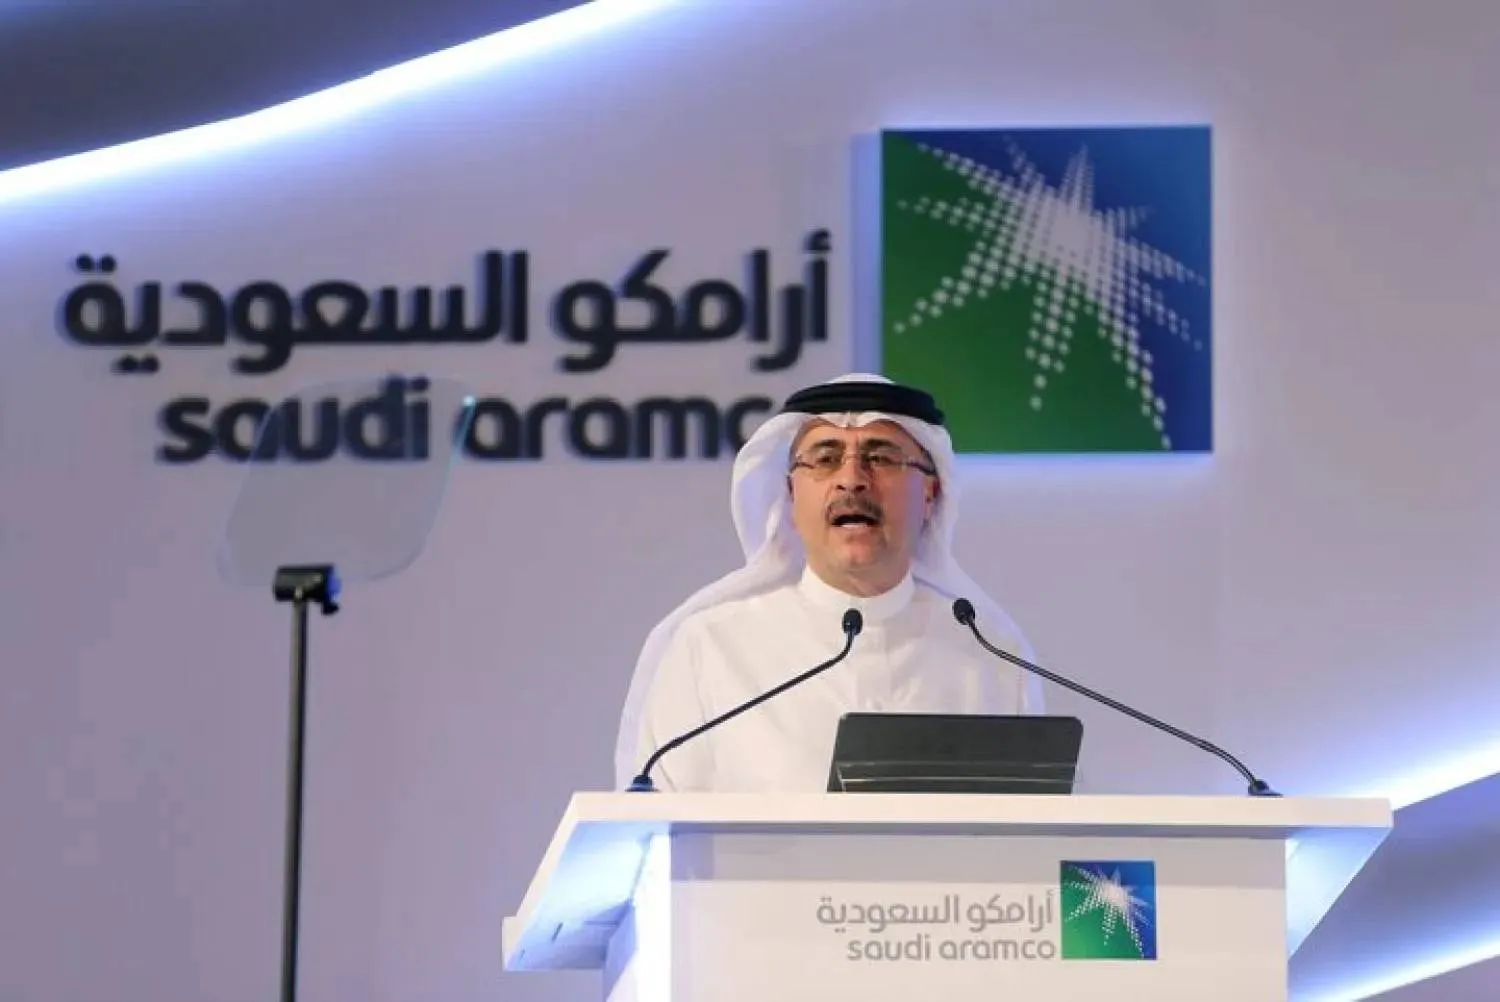
Aramco President and CEO Amin Nasser speaks during a press conference. Reuters file photo
TT

Saudi Aramco Chief: Any Interruption Can be Fixed 'Within Days'

Aramco President and CEO Amin Nasser speaks during a press conference. Reuters file photo

Saudi Aramco can restore disrupted operations within days and is looking at building alternative oil export routes, its President and CEO Amin Nasser said.

Nasser told Nikkei Asia in Tokyo on Thursday that Aramco was studying "a fourth and a fifth route" for crude oil exports in addition to its three primary routes.

Nasser added that the company is considering expanding overseas storage capacity, including in Japan, to strengthen its ability to withstand disruptions.

He stated that Aramco's operations are built with abundant flexibilities in place to continue serving its customers even during disruptions.

He added that observers often assumed Aramco had only two major export pathways, through the Strait of Hormuz or the Bab el-Mandeb Strait at the southern entrance to the Red Sea after using the East-West pipeline. In reality, Nasser said, the company could also access the 320km Sumed pipeline, which carries crude from the Red Sea to the Mediterranean through Egypt.

"People think about interruptions in Hormuz, interruptions in Bab-el Mandeb, [but] we never stopped. We continue to supply our customers," he said. "The only thing you do [is] shift more vessels, one way or the other. ... We do have this multiple optionality that allows us to meet our customers' demand."

The chief executive said that the company was also keen to add more optionality in its oil supplies, including building up additional storage capacities abroad to meet short-term disruptions, as well as "a fourth and a fifth route" for exporting crude.

The company was in discussions with the relevant ministry and its partners in Japan on expanding its storage capacity in the country, as well as "doing the engineering and the feasibility and all of the work that is required" for the additional export routes, Nasser said.


Fed's Williams Says it is Reasonable to See Another US Rate Hike this Year

FILE PHOTO: US dollar banknotes are seen in this illustration taken March 10, 2023. REUTERS/Dado Ruvic/Illustration/File Photo
TT

Fed's Williams Says it is Reasonable to See Another US Rate Hike this Year

FILE PHOTO: US dollar banknotes are seen in this illustration taken March 10, 2023. REUTERS/Dado Ruvic/Illustration/File Photo

New York Federal Reserve President John Williams said on Thursday it was reasonable to think that the US central bank might need to raise interest rates again before the end of the year to help bring down inflation risks.

Forecasts among market participants showed investors thought "it's likely that another rate hike may be appropriate by the end of the year. That seems to me a reasonable way of thinking about it," Reuters quoted Williams as saying.

"But we have to see. We're going to collect the data and do what we did between July and September" in assessing the information, he told ⁠a conference in ⁠London organized by the National Institute of Economic and Social Research, a think tank.

Williams stressed the high levels of uncertainty clouding the economic outlook.

The US central bank under new Fed Chairman Kevin Warsh last week raised its policy rate to the 3.75%-4.00% range and 16 of 18 policymakers signaled the Fed would probably need to deliver ⁠at least one more rate hike before the end of 2026.

Williams — who also serves as vice-chair of the interest rate setting Federal Open Market Committee — said the US and other economies around the world had proven resilient to the shock of higher energy prices caused by the Iran war.

But inflation posed the "big challenge" for policymakers seeking to balance growth and price risks.

"We really want to see not only inflation get back to 2% which is absolutely essential to achieve that, but also we want to see that ⁠happen ... in ⁠a timely manner," Williams said.

The Fed lifted rates last week to target inflation pressures that have overshot its 2% target for years and are building further on the back of President Donald Trump’s trade tariff agenda and the Middle East war.

Fed officials now expect inflation will not be back at target until 2029.

Futures markets are putting strong odds of another increase to borrowing costs at the Fed's October policy meeting, as well as another increase in December.

Asked about the likely timing of the next rate hike, Williams noted that September's move had been triggered by a build-up of pressures rather than a sudden change in data.


EBRD Cuts Growth Outlook Again as Iraq, Lebanon, Ukraine Hit by War Pressures

FILE - A worker collects engine oil as he works at a degassing station in Zubair oil field, near Basra, Iraq, Saturday, March 28, 2026. (AP Photo/Leo Correa, File)
TT

EBRD Cuts Growth Outlook Again as Iraq, Lebanon, Ukraine Hit by War Pressures

FILE - A worker collects engine oil as he works at a degassing station in Zubair oil field, near Basra, Iraq, Saturday, March 28, 2026. (AP Photo/Leo Correa, File)

Growth is slowing across a range of emerging market nations, with economies in Iraq, Lebanon and Ukraine hamstrung by the effects of war, the European Bank for Reconstruction and Development said on Thursday.

High energy prices, rising borrowing costs and issues ranging from drought in Europe to the ongoing closure of the Strait of Hormuz are combining to depress economic growth, the EBRD regional economic outlook found.

Across the 41 economies it covers, the EBRD expects growth of 2.5% this year, 0.6 ⁠percentage points below ⁠its June forecast and its second consecutive downgrade.

"What's a cause for concern is that there are multiple pressure points, from diesel to cost of wheat to cost of borrowing," EBRD chief economist Beata Javorcik said, according to Reuters. "Pressures are building up, and there are considerable downside risks to our forecast."

The sharpest downgrades were for Iraq and Lebanon. The EBRD expects Iraq's economy to contract ⁠by 12% this year after the closure of the Strait of Hormuz curbed oil exports, while Lebanon is expected to contract 5% as conflict with Israel weighs on economic activity.

The EBRD also lowered its forecasts for Ukraine, owing to intensifying Russian attacks, and for Türkiye, where it said persistent inflation pressures were forcing tighter financing conditions.

Price pressures, meanwhile, were less intense than the EBRD had feared. Average inflation in EBRD regions stabilized at around 6%, the report found, and energy accounted for roughly a quarter of the headline figure.

But wheat prices globally are ⁠up roughly ⁠30% since February as Black Sea attacks cut Ukrainian exports to the lowest level since April 2022, Javorcik said.

This could cut Ukrainian wheat, seed oil and metals exports by $5.5 billion this year, equivalent to 2.5% of GDP, as low water levels on the Danube and Russian attacks on rail links limit alternative export routes.

"This of course has big implications for economic activity in Ukraine," Javorcik said, adding that, if farmers cannot export their crops, it could harm their ability to buy fertilizer for the next planting season.

Elevated wheat prices threaten food-importing economies, particularly countries such as Egypt that heavily subsidize bread and grain products.

Russia and Ukraine combined account for roughly a quarter of global wheat exports.


As 5% Treasury Yields Lose Shock Value, Investors Start Worrying about 6%

US Department of the Treasury (Reuters)
TT

As 5% Treasury Yields Lose Shock Value, Investors Start Worrying about 6%

US Department of the Treasury (Reuters)

For years, 5% on the benchmark US 10-year Treasury yield was viewed as the point at which global financial markets would start hitting turbulence. That threshold is beginning to look less like a ceiling and more like a waypoint.

This month's breach of 5% - something that has happened only briefly in recent decades - has forced investors to contemplate an unsettling question: What if 6% is the new number that should be keeping them awake at night? Reuters reported.

The latest move above 5% has not lasted long enough yet to properly test that theory. But it has always been a psychological marker rather than an automatic tripwire, according to BlueBay Asset Management's head of market strategy, Mike Bell.

"People think of it as if there's a magic number for Treasury yields at which it becomes a problem, (but) it's a relative number, not an absolute number," Bell explained.

What matters is how Treasury yields compare with other key investment metrics, particularly the earnings yield on stocks. Bell says that relationship ‌is now approaching ‌an inflection point, potentially setting the stage for an equity selloff.

History offers some guidance. MSCI's main world ‌stocks ⁠index halved in value ⁠the last time the 10-year Treasury yield broke 5%, which was just before the global financial crash. It suffered a similar slump less than a decade earlier when a near 6.8% spike helped pop the dotcom bubble.

JP Morgan's analysts say one of the reasons why the pain-point might now be above 5% again is a "key structural shift" in the global economy, with AI, healthcare and services playing a bigger role. Many of those firms are spending and expanding, regardless of the level of borrowing costs.

That means "the traditional interest-rate channel looks materially less binding" and the "breaking threshold" of stock markets may be "meaningfully higher, potentially in the 5.5%-6.0% range", JP Morgan said, referencing the views of some of the major investors at one of its most recent conferences.

PROFOUND REPRICING

In ⁠the $29-trillion Treasury market, which anchors pricing for virtually all financial assets, a shift from 5% to 6% ‌would represent a profound adjustment in the global cost of capital.

A 6% Treasury yield ‌would imply either significantly higher inflation expectations, growing concerns about US fiscal sustainability, a conviction that interest rates will remain elevated for years - or a mix of ‌all three.

Federal Reserve policymaker Austan Goolsbee said this week that he didn't know whether markets would react differently to a lengthier period of ‌5% yields than they had in the past.

Paul Jackson, Invesco global head of asset allocation research, said investors focus on Treasury yields for a simple reason: Treasuries represent the world's risk-free benchmark and at above 5%, investors can lock in the highest returns on US bonds since 2007.

Jackson's own calculations show world stocks start to drop when the 10-year yield has traded at an average of 4.72% for 12 months and then rises.

That tipping point remains some way off ‌for now - the 12-month average is currently around 4.34% - but Jackson said he was already dialling back on stocks and switching some money into government bonds to cash in on the juicy yields.

"If Treasury ⁠yields keep rising then there ⁠is a risk that the stock market is lower in 12 months' time," he said.

EMERGING QUESTIONS

Emerging markets, which have enjoyed something of a hot streak in recent years, are often among the first casualties when US yields surge.

Higher Treasury returns tend to strengthen the dollar and make dollar-denominated assets more attractive. That sucks capital away from EM economies and can tip hard-up countries into crisis if the cost of servicing their dollar-denominated debt spirals.

Data on investment flows shows last week saw the biggest exodus from EM bond funds in months, with billions also withdrawn from equity funds. Issuance of emerging-market sovereign debt has also been notably lighter than usual this month.

"It's not an optimal picture for EM," said Alison Shimada, Head of Total Emerging Markets Equity, Allspring Global Investments, although she stressed that for now nothing was going "horribly wrong" and therefore remained "constructive".

Perhaps the biggest risk is psychological.

Once investors start asking whether 6% is attainable, the debate shifts beyond a temporary spike in yields. It becomes a broader reckoning with the possibility that the era of abundant liquidity and ultra-cheap money has ended, forcing global asset prices to adapt to a permanently higher cost of capital.

Premier Miton CIO Neil Birrell said while stock markets were showing no sign of collapsing right now, that might be because investors weren't yet plugging in 5%-plus yields into their longer-term profit forecasting models.

"The markets look fine until everyone re-runs their valuation models," Birrell said. "Ultimately, the numbers are the numbers and they've got to come through."