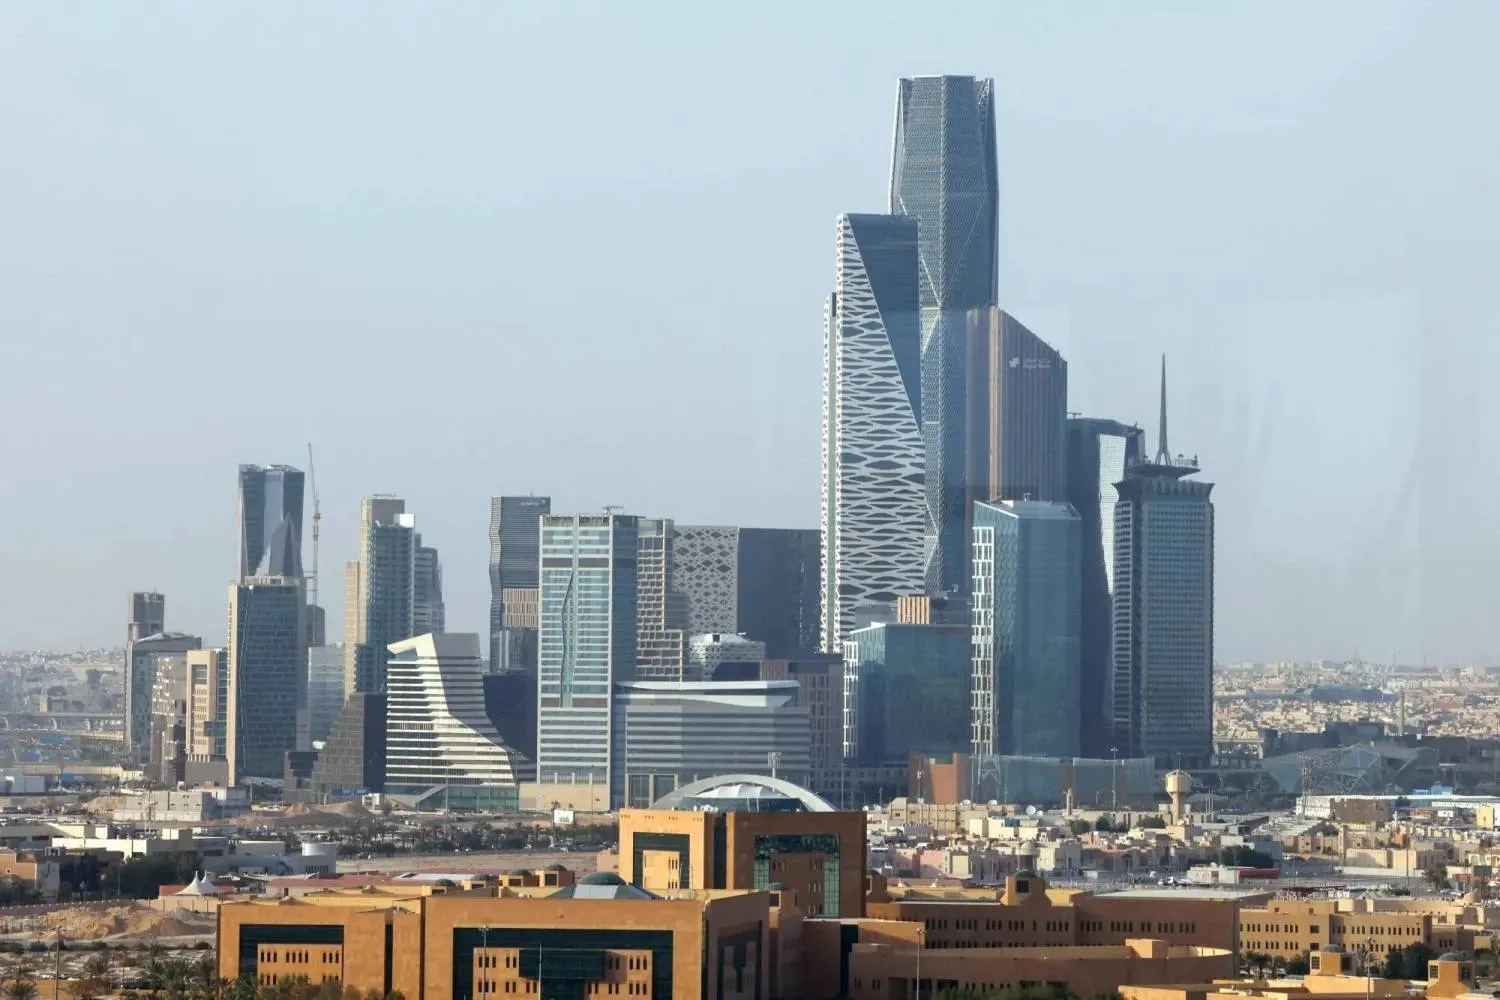
Arab Startups Attract Investors Despite War-Driven Uncertainty

Riyadh, Saudi Arabia (SPA)
TT

Arab Startups Attract Investors Despite War-Driven Uncertainty

Riyadh, Saudi Arabia (SPA)

At a time when geopolitical tensions and regional conflicts cast a shadow over the broader landscape, the Middle East and North Africa's startup ecosystem is showing strong resilience and the ability to attract both local and international capital.

Investment in technology is no longer a complementary option, but a strategic bet, driven by accelerating digital transformation and the stability fostered by leading governments in the region.

“The best time to invest and seize opportunities is when there is fear and uncertainty,” Hassan Haidar, founder and managing partner at Plus VC, told Asharq Al-Awsat.

The firm has backed more than 250 startups across 15 countries in the Middle East and said late last year it plans to fund around 40 startups in 2026, with a focus on deals in Saudi Arabia.

Haidar said the technology and digital services sector continues to benefit, adding that even war cannot halt the region’s rapid shift toward digital services.

Regional tensions have pushed many to rely more on digital tools and online delivery services, creating significant opportunities for startups offering innovative solutions, he said.

Venture capital surge

Startups in the region raised $3.8 billion across 688 deals in 2025, up 74% year on year, according to Magnitt company. Saudi Arabia and the United Arab Emirates took the largest share, with nearly half of the capital coming from international investors.

Haidar said investment is driven not only by current opportunities but also by the ecosystem's growing maturity.

“The past decade was about proving that venture capital can succeed in the region; the next decade will be about proving the scale of these opportunities,” he said.

Structural transformation

Haidar, who began investing in the region in 2010, said the startup landscape has changed fundamentally, from fewer than 100 startups annually across the region about 15 years ago to around 2,000 today.

Markets have become more structured, with governments supporting capital flows and helping establish local and international investment funds. Clearer paths to initial public offerings have emerged, alongside secondary transactions that provide liquidity for investors and founders.

“Markets such as Saudi Arabia and the United Arab Emirates have become regional pillars, belief in the ecosystem is attracting founders, capital and global attention,” he said.

Untapped opportunities

Haidar said the region’s appeal lies in vast untapped opportunities and in key sectors that are still in the early stages of digitization. A generation of ambitious founders with international experience is returning to build technology ventures that address both local and global challenges.

This momentum is backed by clear, strategic government support that gives investors confidence, he said.

Compared with other emerging markets, regions such as Southeast Asia face challenges in exit pathways and liquidity shortages. The Arab region, particularly Saudi Arabia, stands out by offering viable exit channels through public listings and structured secondary transactions.

Trends strengthening competitiveness

Haidar outlined four trends boosting the region’s competitiveness.

First, investors are becoming more financially mature, shifting from development-driven funding to performance-based investment focused on real returns.

Second, exit pathways are becoming more dynamic, supported by strong liquidity, with IPOs and secondary markets offering flexible options to recycle capital.

Third, artificial intelligence is moving beyond hype to real-world applications, addressing complex operational challenges in sectors such as logistics and enterprise software.

Fourth, deep tech and hardware are gaining ground, with a new wave of companies developing advanced solutions to critical issues such as energy security, water and advanced manufacturing, attracting investors willing to back long-term projects.

Challenges and outlook

Despite this progress, access to funding remains a structural challenge. Venture capital still accounts for less than 0.1% of regional GDP, compared with around 1% in the United States, highlighting significant untapped potential.

Still, Haidar expressed strong optimism about the region’s ability to move forward, pointing to the role of governments in maintaining stability.

“We hope for a positive shift and a return to normal conditions, but we strongly believe in our governments’ ability to navigate these difficult times and provide a stable environment that gives us the confidence to continue,” he said.

He said venture capital has moved beyond the stage of doubt.

“We are no longer asking whether startups are important to our economy; we have entered a new strategic phase focused on how to scale and multiply, and on proving the full potential of this ecosystem on the global stage,” he said.


Saudi Minister Says AIIB Success Measured by Development Impact, Not Financing

Saudi Finance Minister Mohammed al-Jadaan at the 11th annual meeting of the Asian Infrastructure Investment Bank’s Board of Governors (X)
TT

Saudi Minister Says AIIB Success Measured by Development Impact, Not Financing

Saudi Finance Minister Mohammed al-Jadaan at the 11th annual meeting of the Asian Infrastructure Investment Bank’s Board of Governors (X)

Saudi Finance Minister Mohammed al-Jadaan urged the Asian Infrastructure Investment Bank to judge its success by the impact of its projects, saying financing volumes and approvals alone do not show whether the bank is improving services, strengthening institutions, or building economic resilience.

Speaking at the 11th annual meeting of the bank’s Board of Governors, which concluded on Tuesday in Doha, al-Jadaan said the AIIB had built strong foundations in its early years.

Progress on regional connectivity, cooperation and private-sector participation had strengthened its ability to meet member countries’ infrastructure needs, he said.

As the bank expands, progress “should not be measured by financing volumes or project approvals alone, but by development impact,” he said.

Success should mean “better infrastructure services, stronger institutions, greater economic resilience and broader private-sector participation,” al-Jadaan said, as the bank enters its second decade and seeks to expand infrastructure financing and mobilize more private capital.

He called for earlier engagement with member countries to better understand their circumstances, infrastructure gaps and priorities, and for multiyear programs aligned with national strategies.

Al-Jadaan also urged the bank to broaden partnerships with multilateral development banks and international organizations to share expertise, avoid duplicating efforts and mobilize more public and private resources.

He said the bank should remain guided by member countries’ needs, taking account of differences in institutional capacity, fiscal space and levels of infrastructure development.

The Doha meeting, held under the theme “Future Infrastructure: Impact and Innovation,” comes as the bank prepares for a new phase of expansion.

The AIIB has said it aims to nearly double annual financing to about $20 billion by 2030, focusing on infrastructure linked to climate resilience, renewable energy, digital transformation and regional connectivity, while mobilizing more private capital.

Saudi Arabia is a founding member of the AIIB, a multilateral development finance institution established in Beijing in 2016.


African Leaders to Gather in Egypt for Business Summit

Friday's forum is expected to bring together more than 20 heads of state and government representatives in the Mediterranean city of Alamein, alongside business leaders, bankers and development institutions. © KHALED DESOUKI / AFP/File
TT

African Leaders to Gather in Egypt for Business Summit

Friday's forum is expected to bring together more than 20 heads of state and government representatives in the Mediterranean city of Alamein, alongside business leaders, bankers and development institutions. © KHALED DESOUKI / AFP/File

African leaders will meet in Egypt on Friday for a business summit that Cairo hopes will bolster its clout across the continent.

Friday's forum is expected to bring together more than 20 heads of state and government representatives in the Mediterranean city of Alamein, alongside business leaders, bankers and development institutions.

"This is an African platform," Egypt's deputy foreign minister for African affairs Mohamed Abu Bakr Saleh told AFP.

"A country in East Africa should be able to sign an agreement with a country in West, North or southern Africa through this platform."

Saleh said the forum would become a biennial event under an African Union mandate, focusing on infrastructure, trade, agriculture, healthcare, mining, technology and renewable energy.

Officials estimate Egyptian investments across Africa at around $14 billion. Among Egypt's flagship ventures is Tanzania's $3 billion Julius Nyerere Hydropower Project, built by a consortium led by Egyptian companies.

Yet trade within Africa remains limited, totalling just $192 billion in 2023 and only accounting for around 15 percent of the continent's total trade, compared with more than 55 percent in Asia and over 70 percent in Europe.

Africa also attracted about $70 billion in foreign direct investment in 2025, a fraction of the roughly $1.6 trillion invested globally, according to the UN.

"Africa possesses vast resources, but they are still not being exploited to the level we would like to see," Saleh said.

The gathering also takes place against the backdrop of an unresolved dispute between Egypt and Ethiopia over the $5 billion GERD, Africa's largest hydroelectric project.

Ethiopia says the dam, inaugurated last year, is vital for economic growth, while Egypt says it could threaten Nile water supplies without a binding operating agreement.

More than a decade of negotiations have failed to yield a settlement.

"Our position on Egypt's water security has not changed and will not change," Saleh said. "It is an existential issue for Egypt."


US Ban on $1 Billion Worth of Canadian Imports Goes into Effect

Shipping containers in the Port of Montreal, Canada (Reuters)
TT

US Ban on $1 Billion Worth of Canadian Imports Goes into Effect

Shipping containers in the Port of Montreal, Canada (Reuters)

US-Canada relations, already tense, are likely to deteriorate further after the United States went ahead early Tuesday with a decision to ban nearly $1 billion worth of Canadian imports, including dairy products and motorcycles.

The ban amounts to barely a ripple in $880 billion worth of a two-way annual trade between the two northern neighbors. But it marks another ratcheting up of President Donald Trump’s second-term trade war with America’s longtime ally and trading partner.

The import ban “certainly won't do anything to help the trade tensions between the United States and Canada,'' said trade attorney Patrick Childress, a partner at Holland & Knight and a former US trade official.

The latest sparring began over the summer when Trump reached back to a Great Depression law to impose 50% tariffs on about $20 billion worth of Canadian imports, charging that Canada discriminates against US dairy and auto producers. Canada promptly counterpunched with tariffs of 15% and 25%, matching US imports dollar for dollar.

To punish Canada for retaliating against his tariffs, Trump decided to ban a list of Canadian products, effective 12:01 a.m. Eastern time Tuesday.

The economic impact is likely to be minimal. Childress noted that the products on the banned list were already facing Trump’s tariffs. “For a lot of these goods, the 50% was already acting as a de facto ban by making importation from Canada into the United States uneconomical,″ he said.

Jacob Jensen, director of trade policy at the center-right American Action Forum think tank, calculates that the ban would cover $967 million worth of Canadian imports, based on 2025 numbers.

“This marks yet another escalation in the trade war that may result in further retaliation on the Canadian side,” Jensen said. He expects Canadian exporters and US importers “impacted by these bans will be highly motivated’’ to demand that trade officials on both sides find some way to reach a “resolution of this whole ordeal.’’