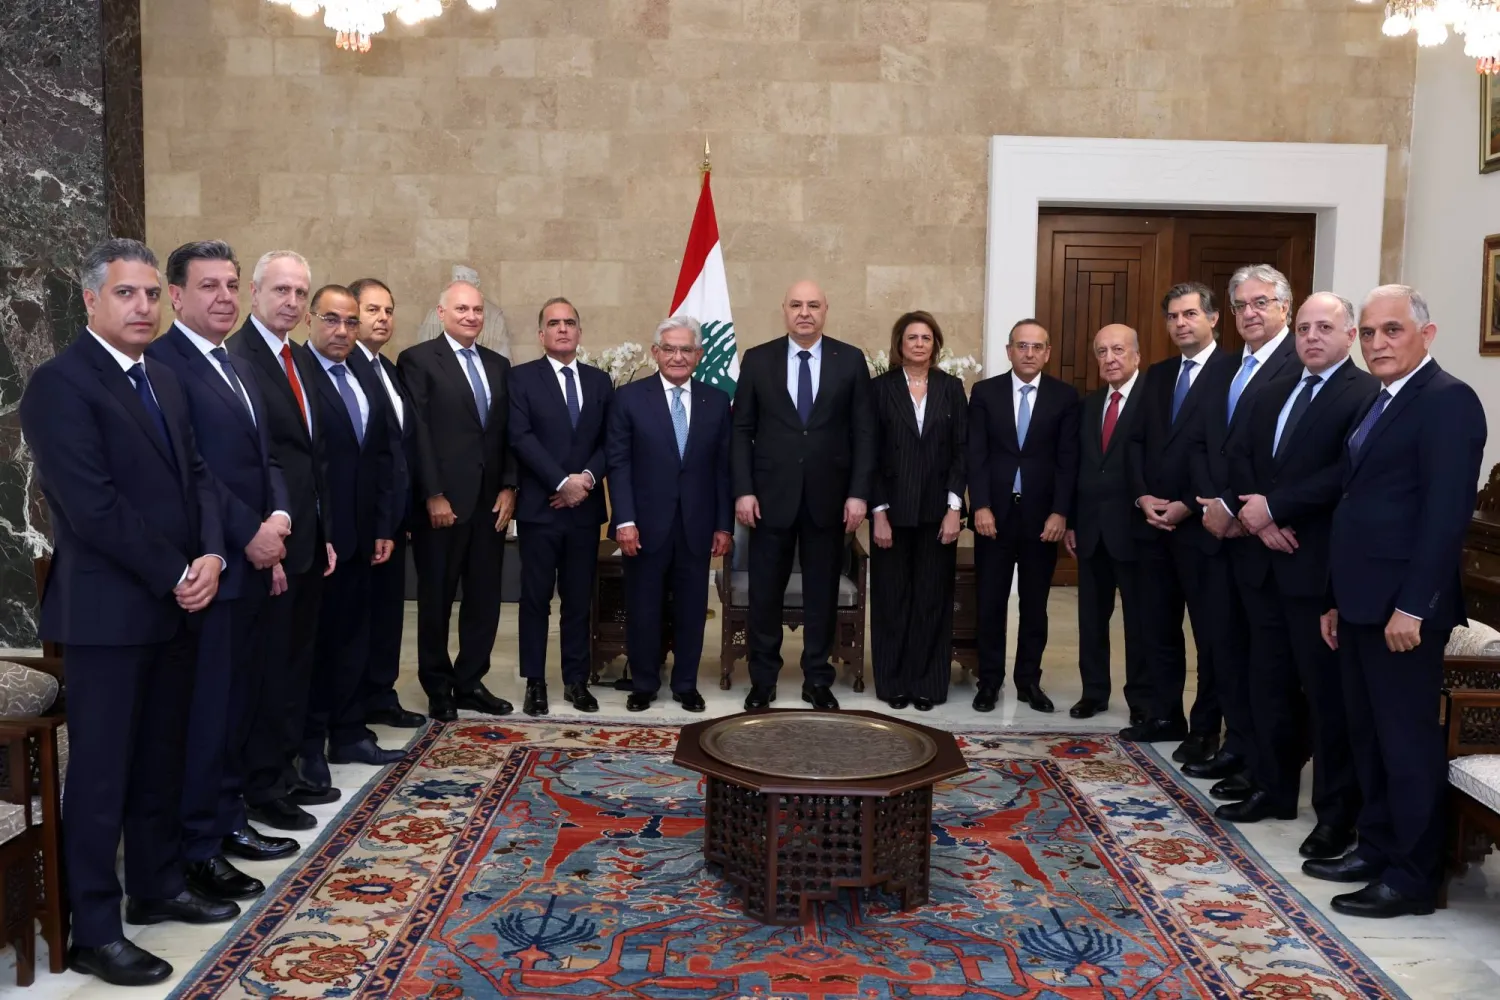
Lebanon's Financial Battles Persist Despite War Priorities

Lebanese President Joseph Aoun meets with a delegation from the Association of Banks in Lebanon (Lebanese Presidency)
TT

Lebanon's Financial Battles Persist Despite War Priorities

Lebanese President Joseph Aoun meets with a delegation from the Association of Banks in Lebanon (Lebanese Presidency)

Lebanon's unresolved financial and monetary issues continue to generate new and pressing obligations for the executive, legislative and monetary authorities. Although they have been partially overshadowed by the storm of war and its devastating human, reconstruction and social consequences, these issues remain high on both the political and economic agenda.

As the government's economic team works on amendments to the draft financial-gap law, including discussions over reservations raised by the central bank, newly proposed changes to the banking reform law, submitted by the government to parliament this month, have reignited the ongoing disputes within Lebanon's financial sector.

These disputes remain centered on the rescue plan and the treatment of structural crises that have persisted into their seventh consecutive year, most notably reflected in the repeated failure to meet reform commitments required to secure a financing agreement with the International Monetary Fund (IMF).

According to information obtained by Asharq Al-Awsat from a financial official, wartime developments and their repercussions have effectively granted Lebanon additional time, at least until the autumn meetings of international financial institutions, to complete legislation forming the roadmap for restoring financial stability and recovering deposits.

This includes the sought-after reforms of the banking sector, alongside compliance with anti-money laundering requirements, particularly measures aimed at curbing the informal economy, shutting down channels used for illicit financial flows, and addressing excessive cash circulation through enhanced source-to-beneficiary verification requirements.

A notable development is expected to influence future deliberations in parliamentary committees and the legislature's general assembly. In an updated report, the IMF classified the crisis affecting Lebanon's banking sector as a "systemic crisis," placing it alongside similar crises experienced by 13 countries worldwide over the past decade, from Angola in 2015 to Vietnam in 2022. This classification is expected to help align Lebanon's reform measures and responsibilities with international standards and draw on rescue plans implemented in comparable cases.

According to the financial official, the IMF's classification could help settle long-running domestic disputes that have prolonged the failure to adopt a comprehensive plan for exiting the financial and monetary crisis and containing its social and economic consequences. Such a plan remains the only viable pathway to restoring confidence in the financial sector and returning gradually to economic recovery, particularly after the enormous reconstruction and economic losses caused by successive destructive wars, estimated to exceed $20 billion at a minimum.
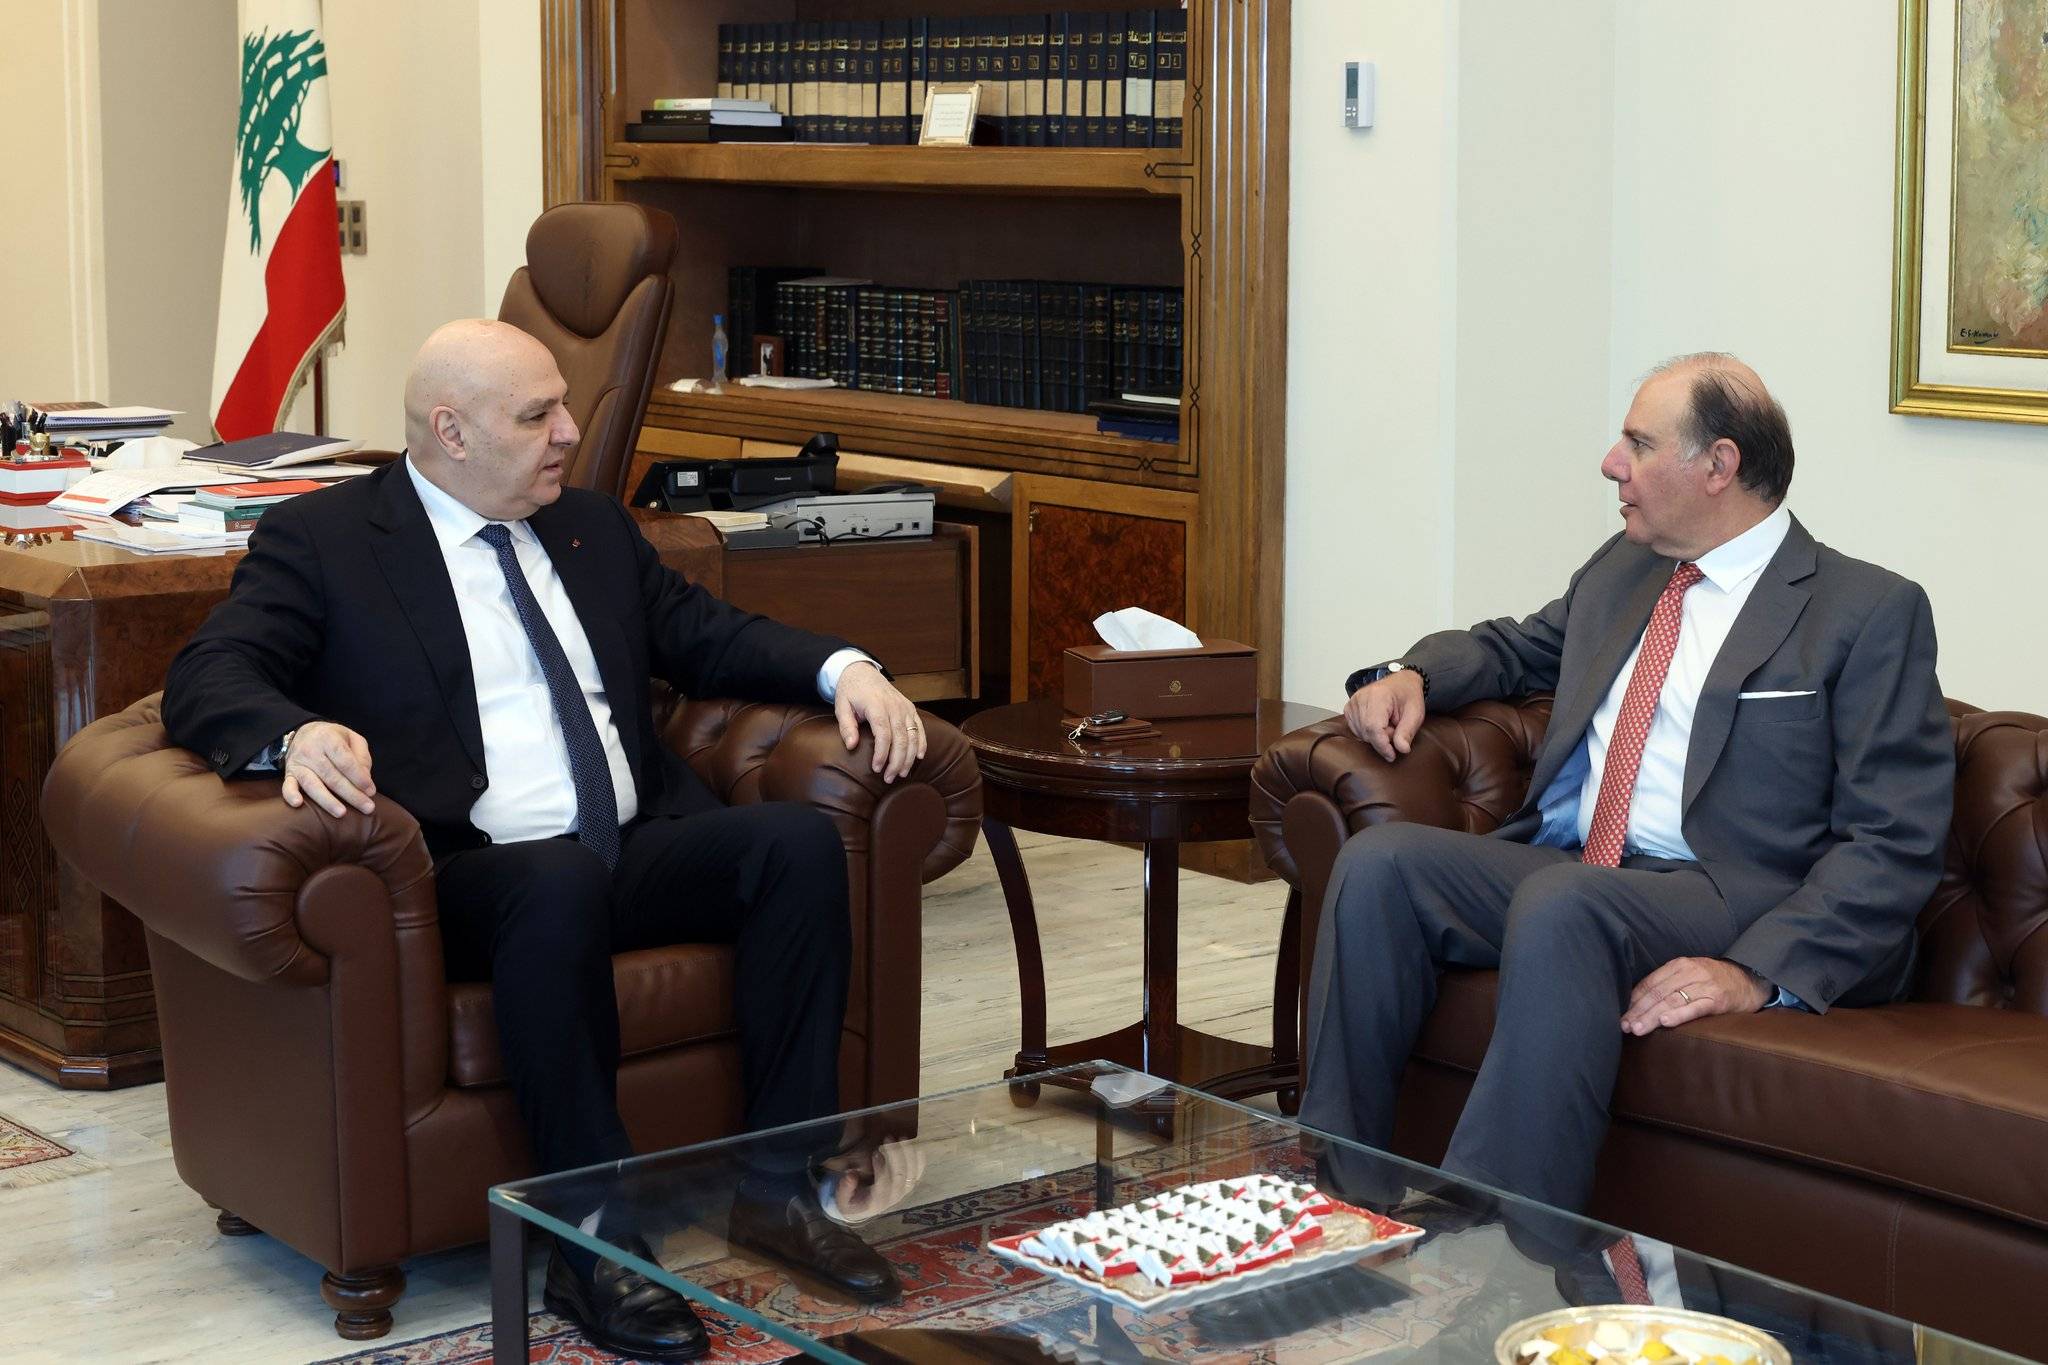
Lebanese President Joseph Aoun meets with Central Bank of Lebanon Governor Karim Souaid on May 7. (Lebanese Presidency)

Systemic Crisis and Financial Sector Restructuring

The official added that this approach takes on added importance amid discussions surrounding the restructuring of the financial sector, particularly the draft law on restoring financial order and recovering deposits submitted by the government to parliament.

"The recognition of the systemic nature of the crisis requires reconsidering some of the proposals currently on the table in a way that ensures a fairer distribution of responsibilities and burdens among all parties concerned, rather than reducing what happened to a narrow framework and placing the full cost of the collapse on depositors and banks," the official said.

This international reassessment is consistent with an opinion issued by Lebanon's State Council more than two years ago, which concluded that Lebanon was not facing an ordinary banking crisis but rather a systemic one, assigning primary responsibility for the financial crisis to the state because of its reliance on borrowing from the central bank to finance budget deficits.

Banks Ready to Shoulder Responsibilities

The issue resurfaced during a meeting between President Joseph Aoun and the board of the Association of Banks in Lebanon, headed by Salim Sfeir. The association conveyed the banking sector's readiness to assume its responsibilities and participate in absorbing losses, provided that reform does not amount to liquidation and that restructuring does not unfairly burden both banks and depositors. It stressed the need for a fair allocation of responsibilities and costs while safeguarding depositors' rights and preserving the sector's viability.

Aoun emphasized "the importance of reaching a fair and comprehensive solution to the banking crisis that satisfies all parties and preserves rights equally."

He stressed the importance of reform without destroying or undermining the sector, adding that "it is the state's duty to stand by the banking sector, reform it and restructure it in order to safeguard the economy and guarantee depositors' rights."

He further noted that "without a sound banking sector, there will be no investment, and there will be no country."
A general view of Beirut, Lebanon. (Reuters/File Photo)

Central Bank Governor Voices Reservations

Earlier, Central Bank Governor Karim Souaid openly expressed reservations about key provisions in the government's proposal, stating that "the draft requires further clarification and strengthening regarding the state's obligations. Since the state is ultimately the entity that used these funds over many years, its contribution must be explicitly defined, measurable, legally binding, and linked to a clear and credible timetable."

In several remarks, Souaid highlighted the challenge of distributing financial burdens and responsibilities among the state, the central bank and commercial banks. He additionally stressed the need to reduce the fiscal deficit by eliminating irregular claims, categorizing deposits into clearly defined groups, and carrying out repayments through a combination of cash payments and asset-backed financial instruments in phases and within available liquidity limits.

Banks continue to insist on their right to participate in discussions that will determine their future. They have outlined an approach that seeks to balance depositor protection with the sector's continued viability. In a memorandum submitted to officials, they argued that "instead of ensuring a fair distribution of responsibilities, the draft law submitted to parliament exempts the state, which bears primary responsibility for the financial gap, from making any clear contribution toward losses. Moreover, the proposal harms both the banking sector and depositors alike."

For instance, the draft law, despite objections from the monetary authorities, requires the removal of impaired assets, meaning assets deemed unrecoverable for depositors, and proposes deducting them from deposits without returning them to their owners. At the same time, banks would be required to absorb their value as losses. In practice, this would impose losses on both depositors and banks, pushing banks toward liquidation rather than enabling them to repay deposits.

Consequently, if banks are burdened with obligations that exceed their responsibilities and capacities, the outcome will be clear: the liquidation of the majority of banks.

The financial official noted that international experience shows that systemic crises, regardless of their severity, can become a starting point for rebuilding stronger and more modern financial systems when political will and serious reforms are present. The current period therefore represents an opportunity to redesign a new economic and financial model that can restore Lebanon's regional financial role and rebuild confidence both domestically and internationally.

In this context, the official said, it is essential to adopt a balanced and inclusive approach that rebuilds confidence in the financial and banking sectors while safeguarding the rights of depositors and investors and ensuring the continuity of financial institutions.

Economic recovery cannot be achieved through confrontational policies or temporary solutions, but rather through a comprehensive reform vision that recognizes the true scale of the crisis and lays the groundwork for a gradual and sustainable recovery.


Türkiye Says It Is Starting Offshore Hydrocarbon Exploration in Pakistan, Plans Drilling Next Year

This handout photograph taken on November 10, 2026 and released by Türkiye's Ministry of Energy and Natural Resources on November 12, 2026 shows Türkiye's Minister of Energy and Natural Resources Alparslan Bayraktar (C) during a session at the 31st United Nations Climate Change Conference (COP31) at the Antalya Expo Center in Antalya. (Handout / Turkish Energy Ministry / AFP)
TT

Türkiye Says It Is Starting Offshore Hydrocarbon Exploration in Pakistan, Plans Drilling Next Year

This handout photograph taken on November 10, 2026 and released by Türkiye's Ministry of Energy and Natural Resources on November 12, 2026 shows Türkiye's Minister of Energy and Natural Resources Alparslan Bayraktar (C) during a session at the 31st United Nations Climate Change Conference (COP31) at the Antalya Expo Center in Antalya. (Handout / Turkish Energy Ministry / AFP)

Türkiye's Oruc Reis seismic research vessel will begin exploration for hydrocarbon resources in offshore fields in Pakistan, Turkish Energy Minister Alparslan Bayraktar said on Friday, adding that drilling was expected to start in 2027.

Last year, Türkiye's state oil company TPAO ‌signed hydrocarbon exploration ‌and production agreements ‌with ⁠Pakistani companies including Mari ⁠Energies, Fatima, OGDCL, PPL, Prime and GHDL for three offshore and two onshore fields in Pakistan.

Bayraktar, who attended a ceremony to welcome Oruc ⁠Reis at Karachi Port alongside ‌Pakistan's Foreign ‌Minister Ishaq Dar and Petroleum Minister ‌Ali Pervaiz Malik, said on ‌X the vessel would carry out two- and three-dimensional seismic survey operations in the Indus and Makran basins ‌to "uncover the potential there".

The step marked a "strong ⁠turning ⁠point" in energy cooperation between the two countries, he said, noting that it came at a time of turbulence in global oil and gas markets.

Last month, Bayraktar said the planned operations off Pakistan had been delayed by about six months due to the war in Iran.


ECB's Lagarde: Cyber Threat Boosted by AI is My Top Worry

President of the European Central Bank (ECB) Christine Lagarde addresses guests at the 36th Frankfurt European Banking Congress (EBC) at the Old Opera (Alte Oper) in Frankfurt am Main, western Germany on November 20, 2026. (Photo by Kirill KUDRYAVTSEV / AFP)
TT

ECB's Lagarde: Cyber Threat Boosted by AI is My Top Worry

President of the European Central Bank (ECB) Christine Lagarde addresses guests at the 36th Frankfurt European Banking Congress (EBC) at the Old Opera (Alte Oper) in Frankfurt am Main, western Germany on November 20, 2026. (Photo by Kirill KUDRYAVTSEV / AFP)

The greatest immediate challenge facing the world of finance may be cyber threats supercharged by increasingly sophisticated AI agents, European Central Bank President Christine Lagarde said on ⁠Friday.

Attackers are often ⁠anonymous, and difficult to track, and rely on dubious funding often from "toxic ⁠states" that have a vested interest in disrupting the world, Lagarde said.

"The one (worry) that keeps me awake, and many of you awake as well ... is AI ⁠applied ⁠together with cyber threat," Lagarde told the European Banking Congress in Frankfurt, adding that policymakers have not paid enough attention to this threat.

She also said that the ECB will make its currency swap lines with other countries more accessible to shield the euro area from outside financial shocks and boost the euro's global role.

The ECB only has swap lines with major central banks such as the US Federal Reserve and the People's Bank of China at present, allowing them to exchange their own currencies for euros at times ⁠when financial markets ⁠seize up.

Lagarde's comments suggest these financial lifelines might one day become more widely available as part of the ECB's push to promote the international use of the single currency and make the euro zone less dependent on the US dollar for trade and investment.

"We are working ⁠to keep our swap lines fit for purpose in a more fragmented world," she told the conference. "They will be more accessible, too."

Policymakers globally have been questioning the long-term dominance of the dollar in light of US President Donald Trump's unpredictable economic policy and the United States' ballooning public debt.

Lagarde said the primary goal of the swap lines was to limit spillover of financial stress from abroad, indirectly helping the ECB ⁠control borrowing ⁠costs in the euro area.

But she added these central bank swaps make foreign investors more comfortable holding euros.

"A reserve manager who knows that euro securities can be turned into euro liquidity without a fire sale has more reason to hold them in normal times," Lagarde said.

In a similar vein, the ECB has recently opened up its EUREP facility, which allows foreign central banks to obtain euros against collateral, but only provided that it is denominated in the single currency. More than 30 countries have expressed interest in getting access.


Oil Prices Set for 3rd Straight Weekly Decline on Middle East Export Flows

Oil pumpjacks operate at an oil field run by North American Blue Energy Partners (NABEP) in Lagunillas, Venezuela, Tuesday, Nov. 17, 2026. (AP Photo/Ariana Cubillos)
TT

Oil Prices Set for 3rd Straight Weekly Decline on Middle East Export Flows

Oil pumpjacks operate at an oil field run by North American Blue Energy Partners (NABEP) in Lagunillas, Venezuela, Tuesday, Nov. 17, 2026. (AP Photo/Ariana Cubillos)

Oil prices edged down on Friday and were set for a weekly decline on strong exports from the Middle East.

Brent crude futures were down 95 cents, or 1%, to $91.03 a barrel at 0900 GMT. US West Texas Intermediate futures for December were down $1.40, or 1.7%, to $81.81 a barrel, while the more active January contract was down 83 cents, or 1%, to $81.61, Reuters reported.

Brent is on track for a 5% decline for the week and the December WTI contract for an almost 8% weekly drop as expectations of a supply surplus grew because crude ⁠shipments through the Strait ⁠of Hormuz have returned to roughly pre-war levels. This would be the benchmarks' third straight week of decline.

"This week we keep having relatively strong export flows out of the Middle East. There is also a narrative ongoing that as long as people are talking, maybe there's a deal in the making," said Aldo Spanjer, commodity strategist at BNP Paribas.

"The prices are correct if you believe that this geopolitical risk doesn't come back. I'm not in that camp who thinks ⁠this is done... I probably see a rebound," he said.

Iran's intensifying attacks on tankers transiting the Strait of Hormuz, "running at roughly one incident per day in November", still add a meaningful geopolitical risk premium to the market, according to UOB Group analysts in a client note.

OPEC+ ministers will hold a series of meetings on November 29 to decide their 2027 output policy. The group comprises the Organization of the Petroleum Exporting Countries and allies such as ⁠Russia.

Some analysts expect softness in the broader equities markets to weigh on oil prices, as Asian shares fell on Friday — heading for their worst week since 2020.

"Supply disruptions remain a risk, but near-term demand concerns tied to the AI trade unwind and broader risk-off sentiment are weighing on prices," said Saxo analysts in a note.

In Russia, crude oil output could fall again as Ukrainian attacks on refineries and export infrastructure intensify, analysts and traders say. Ukrainian drone attacks have slashed Russian oil refineries' combined crude processing volumes by 45% since late October, Reuters reported on Wednesday.