Trump Says China Will Suffer as Data Shows Trade War Hurting US

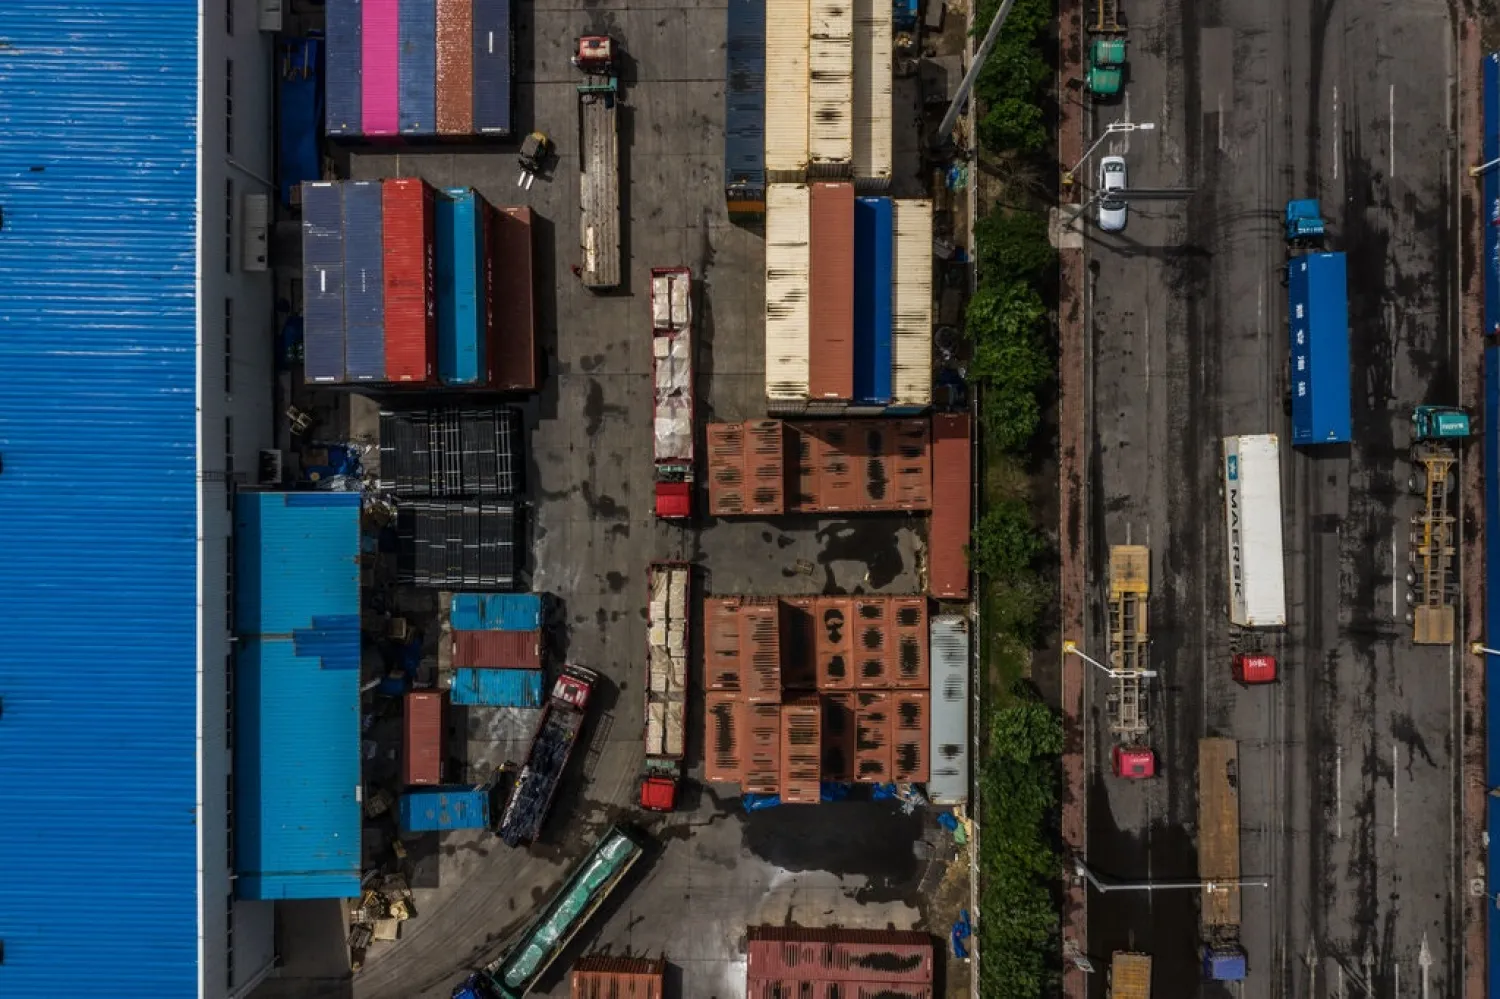
Tianjin Port in China. The manufacturing sector’s struggles are likely to increase as the United States and China escalate their trade fight.CreditCreditLam Yik Fei for The New York Times
TT

Trump Says China Will Suffer as Data Shows Trade War Hurting US

Tianjin Port in China. The manufacturing sector’s struggles are likely to increase as the United States and China escalate their trade fight.CreditCreditLam Yik Fei for The New York Times

President Trump said on Tuesday that Chinese manufacturing would “crumble” if the country did not agree to the United States’ trade terms, as newly released data showed his trade war was washing back to American shores and hurting the factories that the president has aimed to protect.

Days after new tariffs went into effect on both sides of the Pacific, a closely watched index of American manufacturing activity fell to 49.1 from 51.2, signaling a contraction in United States factory activity for the first time since 2016. The companies responding to the Institute for Supply Management survey, which the index is based on, cited shrinking export orders as a result of the trade dispute, as well as the challenge of moving supply chains out of China to avoid the tariffs.

The manufacturing sector’s struggles are likely to increase as the world’s two largest economies continue to escalate their trade fight. On Sunday, Trump placed a new 15 percent tariff on a range of consumer goods, including clothing, lawn mowers, sewing machines, food and jewelry, and Beijing retaliated by increasing tariffs on $75 billion worth of American products. China also said on Monday that it was filing a complaint at the World Trade Organization over Trump’s new tariffs.

Markets sank on weaker economic news and worries about the trade war. The S&P 500 was down about 0.9 percent, with particular weakness in industrial and energy stocks.

Prices of key industrial commodities were also lower, with futures prices for benchmark American crude oil down roughly 3 percent. Copper, considered a barometer of the health of the global industrial sector, was down a bit less than 1 percent.

The yield on the 10-year Treasury note declined to 1.45 percent, as jittery investors continued to buy government bonds, pushing prices up and yields lower. The drop in bond yields this year — the yield on the 10-year note was above 3 percent in late 2018 — suggests a broad-based cut in expectations for economic growth among investors.

“The U.S. trade war with the world has blown open a great big hole in manufacturers’ confidence,” Chris Rupkey, the chief financial economist at MUFG Union Bank, wrote in a note on Tuesday. “The manufacturing sector has officially turned down and is falling for the first time this year as the China tariffs and slowdown in exports has really started to bite.”

The president has continued to insist that pain from the trade war is falling primarily on China, not the United States. On Friday, he said American companies were leaving China in response to his tariffs, a development that put the United States in an “incredible negotiating position.” And he said any business that complained about financial pain from the tariffs was suffering from bad management, not the trade war.

On Tuesday, he warned Beijing not to try to wait for a new administration to come into office after the 2020 election, saying China’s supply chain “will crumble” and that it would be “a long time to be hemorrhaging jobs and companies on a long-shot.”

Many chief executives and trade groups say they support the president’s goal of changing China’s economic practices, particularly those that require businesses to hand over valuable technology as a condition of operating in China. But businesses have begun to express concern about the seemingly unending trade war. Many big companies, particularly those in the retail and manufacturing sectors, have downgraded sales and profit forecasts as a result of the tariffs.

The trade war’s potential to slow America’s economic expansion, including its impact on the manufacturing sector, has already prompted concern from Federal Reserve officials. The Fed cut interest rates for the first time in more than a decade in July, and officials have said they are prepared to cut them further to protect the economy against fallout from slowing global growth and trade risks.

Even some officials who did not vote in favor of July’s rate cut say economic risks have increased.

Eric Rosengren, the president of the Federal Reserve Bank of Boston and a monetary policy voter this year, indicated that he still favored waiting and watching incoming economic data before making interest rate cuts beyond the July move, which he voted against.

But he also said it was “clearly reasonable” to judge that risks to the economy were elevated. “Should those risks become a reality, the appropriate monetary policy would be to ease aggressively,” he said, suggesting that he might favor rapid interest rate cuts if economic data soured meaningfully.

The Trump administration has been pressuring China for more than two years to make a trade deal that would strengthen its protections for American intellectual property and result in large purchases of American products. But the two sides continue to have significant disagreements, including which of Trump’s tariffs should be rolled back and what kind of legal changes China must make to treat American companies more fairly.

Since talks between the two countries stalled in May, Trump has moved ahead with his threat to tax nearly everything China sends to the United States. On Sunday, the Trump administration placed a 15 percent levy on roughly $112 billion worth of Chinese goods and plans to place tariffs on roughly $160 billion worth of cellphones, laptops, clothing and toys on Dec. 15. Trump has also said the United States will raise tariffs on $250 billion worth of products to 30 percent from 25 percent on Oct. 1.

China has vowed to retaliate on Dec. 15 with more tariffs of its own.

While a deal appears far from certain, the two sides could still avert the increases and declare another cease-fire. The United States and China have discussed a meeting in Washington in September, and American and Chinese officials will both be present on the sidelines of the United Nations General Assembly meeting in New York later in the month.

Myron Brilliant, the executive vice president of the U.S. Chamber of Commerce, said the two governments would have to work to restore some trust before any conclusion to the trade war would be reached — perhaps through Chinese purchases of American agricultural goods, something Mr. Trump has long focused on.

“There’s a trust deficit between the two governments,” he said. “We need steppingstones to build confidence in the relationship so both governments are positioned to get a deal down the road.”

The New York Times


Gulf Railway Enters Implementation Phase, Targets 2030 Completion

Members of the GCC Transport and Communications Ministers Committee pose for an official photo in Manama (GCC). 
TT

Gulf Railway Enters Implementation Phase, Targets 2030 Completion

Members of the GCC Transport and Communications Ministers Committee pose for an official photo in Manama (GCC). 

Gulf Cooperation Council (GCC) countries signed an agreement in Manama on Sunday to advance a 2,117-kilometer railway linking all six member states by 2030, as shipping disruptions in the Strait of Hormuz underscore the need to diversify trade and supply routes.

The agreement establishes a common framework for building and operating the network and integrating national transport systems, amid regional tensions that have disrupted cargo movements, raised shipping and insurance costs, and highlighted the importance of alternative routes.

The Gulf railway is intended to strengthen regional logistics rather than replace maritime transport, which remains essential to Gulf and international trade.

The signing ceremony was held under the patronage and in the presence of Bahrain’s Crown Prince and Prime Minister Prince Salman bin Hamad Al Khalifa, with GCC transport ministers and Secretary-General Jasem Mohamed Albudaiwi attending.

The planned network will connect Kuwait, Saudi Arabia, Bahrain, Qatar, the United Arab Emirates and Oman, with full operations targeted for December 2030.

The agreement sets out member states’ obligations, coordination mechanisms, technical and operational standards, and safety requirements to ensure compatibility with national railway systems.

Bahrain’s Minister of Transportation and Telecommunications, Dr. Sheikh Abdulla bin Ahmed Al Khalifa, told Asharq Al-Awsat that each country would finance and implement the section within its territory.

He explained that GCC states had not signed prior agreements with international partners to finance or execute the project, although global companies could provide expertise and technical and technological services according to national requirements.

Project 55.9% Complete

Albudaiwi announced that the Gulf railway project had reached 55.9% completion, describing the agreement as a framework governing member states’ commitment, implementation procedures and the timetable for bringing the network into service.

While full operations are scheduled for December 2030, cross-border connections between neighboring countries could open individually once the necessary infrastructure and operational requirements are met.

This would allow completed sections to enter service progressively rather than waiting for the entire 2,117-kilometer network to be finished.

Projections indicate that the railway will carry approximately 6 million passengers and 200 million tons of freight in 2030, rising to more than 8 million passengers and 271 million tons by 2045.

Passenger trains are expected to reach speeds of 200 kilometers per hour, while freight services will operate at 80 to 120 kilometers per hour.

The network will connect economic and industrial centers, ports and logistics hubs across the Gulf, facilitating trade and the movement of passengers and goods while creating investment and employment opportunities in transport and related services.

National Financing and Potential Partnerships

Earlier estimates put the cost of the project’s core infrastructure at between $15.4 billion and $16 billion.

The Bahraini minister explained that these figures were under review because of rising costs for construction materials, services and building works. No revised estimate for the overall project has been announced.

Although each country will fund its own section, private-sector participation remains possible in certain components, subject to economic and financial feasibility studies.

The minister added that potential partnerships would depend on the requirements of individual sections, with no single financing or implementation model envisaged for the entire network.

Bahrain’s connection to the Gulf railway depends on the proposed King Hamad Causeway, which would link the island kingdom to Saudi Arabia through a railway alongside a road connection.

The project would connect Bahrain’s international passenger terminal with the Saudi railway network, providing a direct link to the wider GCC system.

Bahrain currently relies on the King Fahd Causeway for road transport to Saudi Arabia. Studies and procedures concerning the proposed King Hamad Causeway, including its railway component, remain underway as part of efforts to complete the cross-border connection.

Shipping Disruptions Highlight Logistics Challenges

The agreement has taken on added significance following recent disruptions to regional shipping, particularly reduced vessel traffic at Bahrain’s Khalifa bin Salman Port, which has increased reliance on road transport and alternative ports in neighboring countries.

Albudaiwi praised Saudi Arabia, the UAE and Oman for their cooperation during the period of Iranian attacks, citing logistical facilities, coordination and alternative cargo routes that helped maintain supply chains to other GCC countries.

He stressed the need for greater integration among transport systems, more diversified supply routes and stronger preparedness and coordination to manage future crises.

The GCC’s transport and storage sector recorded real growth of 5.7% in 2025, making it one of the fastest-growing non-oil economic activities, he noted.

At the 19th consultative meeting of the GCC Supreme Council in Jeddah on April 28, 2026, Gulf leaders called for a study on strengthening logistics integration among member states as part of broader efforts to develop transport networks and diversify trade and supply routes.

Rail and Maritime Transport to Work Together

Despite the renewed focus on rail connectivity amid shipping disruptions, the project is designed to complement maritime transport rather than compete with it.

Rail services could move goods from ports to industrial centers and domestic markets while providing additional distribution routes between GCC countries. Ships would continue to carry the bulk of international freight over long distances.

Integrating the railway into wider international logistics corridors would require further studies, agreements and coordination among governments and relevant authorities, beyond completing the rail infrastructure within the GCC.

The network is also expected to stimulate intra-Gulf trade, improve connections between production and consumption centers, and attract investment in transportation, logistics and related industries.

Additional employment opportunities are anticipated in construction, operations, maintenance and supporting services.

From a 2009 Proposal to Regional Implementation

The Gulf railway initiative dates to December 2009, when the GCC Supreme Council approved plans for a network connecting member states to facilitate trade, improve mobility for citizens and residents, and strengthen regional economic integration.

In December 2021, the council approved the establishment of the GCC Railways Authority to coordinate national efforts, monitor connectivity and operational requirements, and provide an institutional framework for cooperation.

Implementation has since progressed across member states, with completion exceeding 50% by May 2026.


Saudi Gold Refinery Obtains 10 Gold Exploration Licenses in Tanzania

A gold mine in Saudi Arabia (SPA) 
TT

Saudi Gold Refinery Obtains 10 Gold Exploration Licenses in Tanzania

A gold mine in Saudi Arabia (SPA) 

Saudi Gold Refinery Company (SGR) announced Sunday it has secured 10 licenses to explore gold in the Republic of Tanzania, covering a total area of nearly 1,000 square kilometers, in a move aimed at expanding the company’s mining operations outside the Kingdom.

The company said it has allocated an initial investment of $10 million to carry out exploration activities, within an ambitious plan to gradually increase total investments to $100 million. These investments will support the development, establishment, and operation of gold mines, with commercial production targeted to commence by 2030.

The announcement follows a visit to Tanzania by Faisal Suliman Al-Othaim, Deputy Chairman of the Board of Directors at SGR.

According to the company, this milestone is supported by the Ministry of Investment and the Saudi Embassy in Tanzania, highlighting the importance of strengthening Saudi investments abroad and creating new opportunities for national companies in the global mining industry.

SGR continues to advance its global expansion strategy through its international investment arm, UGM Tanzania co, which oversees its operations and investment activities in Tanzania and Ethiopia.

The company also maintains ongoing projects and business activities in Egypt and the Sultanate of Oman, while actively exploring opportunities in additional markets to further expand its global footprint and create sustainable value across the mining sector.

In the Saudi market, the company plans to develop six to ten mines before 2030, at an average rate of two mines per year. These plans are supported by the Ministry of Industry and Mineral Resources, the Saudi Industrial Development Fund, financial institutions and other relevant authorities and stakeholders.


Oil Falls as Trump Says New Iran Attacks ‘Unlikely’

A worker walks past oil pipes at a refinery in Wuhan, Hubei province March 23, 2012. (Reuters)
TT

Oil Falls as Trump Says New Iran Attacks ‘Unlikely’

A worker walks past oil pipes at a refinery in Wuhan, Hubei province March 23, 2012. (Reuters)

Oil prices fell at Monday's open after US President Donald Trump said he was highly unlikely to order new Iran attacks while talks to end the conflict make progress, despite both nations' reports of attacks on ships in or near the Strait of Hormuz.

Brent was down 84 cents, or 0.85%, to $97.48 a barrel by 0138 GMT, while West Texas Intermediate fell 32 cents, or 0.35%, to $90.51 a barrel.

The fall reversed minor gains made on Friday’s settlement as the market assessed the possibility of further US ‌strikes on Iran, ‌although Brent fell 17% last week, the ‌steepest ⁠weekly drop since the ⁠start of the COVID pandemic and the biggest in absolute terms, according to LSEG data dating back to 1988.

"It depends on whether or not they sign a very strong agreement," Trump told CNN in a phone interview. "The answer is, highly unlikely it's going to be necessary."

Trump had hinted at renewing attacks on Iran after ⁠last week's US midterm elections, but there has ‌been no sign of a large-scale ‌US military operation. Iran has said it would respond by striking US and ‌Israeli targets.

Tim Waterer, chief analyst at KCM Trade, called ‌Trump's comments "more measured" but said "the market is still waiting to see whether the midterms have produced a lasting shift in Trump’s approach to the conflict, or whether this is just another temporary change in tone."

Oil is headed ‌for a glut again as recovering Middle Eastern oil flows, rising production from other countries and ⁠weak demand have ⁠pushed global supply above consumption, JPMorgan said in a report on Friday, estimating a surplus of 1.1 million barrels per day in September, widening to 1.4 million bpd in October.

On Sunday, Iraq reached an understanding with the US to allow Iraqi oil exports through the Strait of Hormuz via a shipping lane near Oman, Foreign Minister Fuad Hussein said in an interview with Al Jazeera.

He said Iraq's losses from the Iran war and disruptions to oil exports had reached $60 billion.