Turkey's Banks Shy Away from Erdogan's 'Crazy' Canal

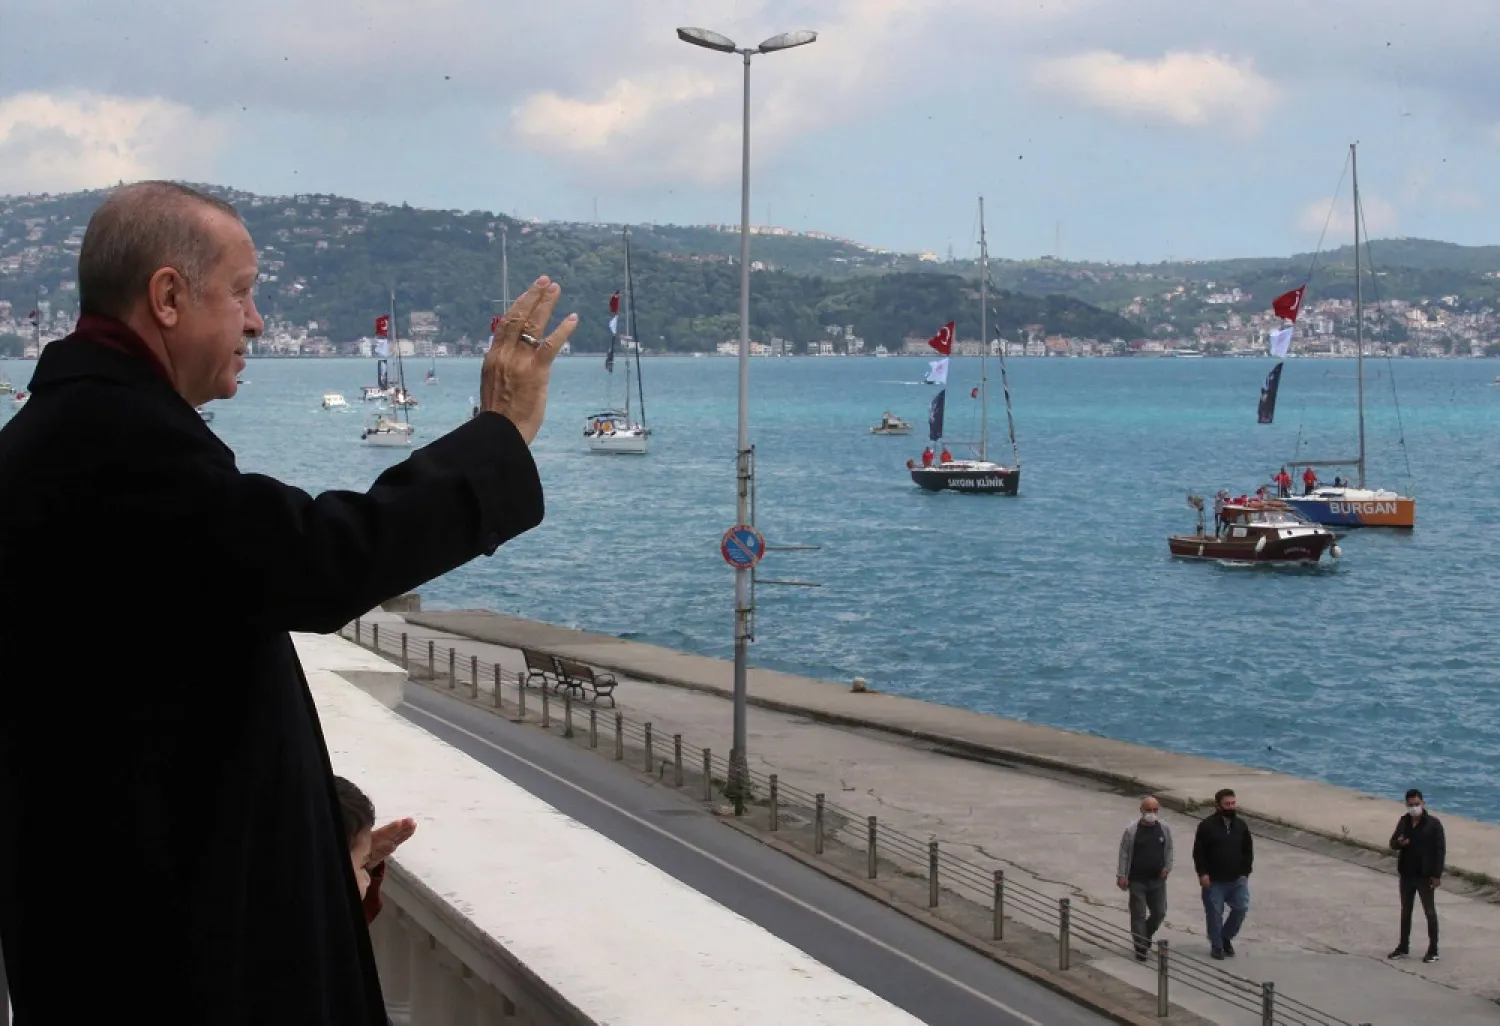
Turkey's President Recep Tayyip Erdogan salutes vessels as they sail the Bosphorus Strait in Istanbul last year. (AP)
TT

Turkey's Banks Shy Away from Erdogan's 'Crazy' Canal

Turkey's President Recep Tayyip Erdogan salutes vessels as they sail the Bosphorus Strait in Istanbul last year. (AP)

Some of Turkey's biggest banks are reluctant to finance President Recep Tayyip Erdogan's planned Istanbul canal due to environmental concerns and the investment risks hanging over the massive construction project, four senior bankers told Reuters.

Two of the sources said a global sustainability pact that six of Turkey's top banks have signed was a barrier to funding the Kanal Istanbul, which Erdogan dubbed his "crazy project" when he floated it a decade ago.

The government expects to break ground in June on the canal, which would connect the Black Sea to the north with the Marmara Sea to the south, running 45 km (28 miles) through marshland, farms and towns on the western edge of the city.

Erdogan says the canal would protect the Bosphorus Strait, which runs through the heart of Istanbul, by diverting traffic.

Yet Istanbul's mayor, engineers and, according to one poll, most citizens, oppose the project on environmental grounds, saying it would destroy a marine ecosystem and resources that supply almost a third of the city's fresh water.

Russia, meanwhile, has signaled unease about the project on security grounds as the canal would open a second passage to the Black Sea, which is home to a Russian naval fleet.

"I don't think we can take part in the funding of Kanal Istanbul," said a senior banker who requested anonymity. "It may trigger some environmental issues."

Six Turkish banks, including Garanti Bank, Is Bank and Yapi Kredi, have signed the UN-backed Principles for Responsible Banking framework which calls on signatories to avoid harming people and the planet.

"Definitely we don't want to give a loan to this kind of project because of the environmental issues," a second senior banker told Reuters, adding that signatory banks must abide by the UN-backed sustainability pact.

In 2019, the canal's price tag was estimated at 75 million lira - or $13 billion at the time - in a government report.

'Profitable project'
The reluctance of some Turkish lenders to finance the project makes it more likely state and foreign financing will have to play a bigger role for Erdogan's dream to come true.

A Finance Ministry spokesman did not immediately respond to a request for comment.

Asked whether Turkish banks would participate in the financing, Erdogan's spokesman and adviser, Ibrahim Kalin, told Reuters the project would "certainly" attract investors and creditors when tenders are held soon.

Garanti Bank declined to comment. Is Bank and Yapi Kredi did not immediately respond to requests for comment.

Denizbank and state-owned Vakifbank also declined to comment on the canal's financing while Akbank and state lenders Halkbank and Ziraat Bank did not immediately respond to requests for comment.

The cost of the canal would eclipse other mega projects such as Istanbul's vast new airport that have defined Erdogan's legacy of credit-driven growth.

Massive foreign short-term debt worth some $150 billion for banks and companies has dogged the lira and laid bare the risks of Turkey's depleted foreign exchange reserves.

A currency crisis in 2018 delayed the canal project but it is back on the agenda as the economy rebounds from the pandemic and the government approved development plans last month.

In an interview on Sunday, Erdogan's adviser Kalin said there was already interest in the bidding that would be open to all including Turkish, European, American and Chinese firms.

"It's a profitable project ... and we are positive it will move forward," he told Reuters.

'White elephant'
But for most of Turkey's banks, especially lenders with European backers and those involved in loan syndications, the risks would likely be too high, the sources said.

They said taking on such a large project could limit their capacity to carry out further loan syndications while there was also a risk the project could be torpedoed at a later stage.

"No Turkish bank, neither state nor private, could take that risk," said a former senior banker.

Turkey's environment ministry has carried out environmental assessments which cleared the way for the project to proceed.

But European backers of Turkish banks would probably not see a Turkish environmental stamp of approval as credible, the former banker said.

"This is one of those white elephants. Other than land price speculation, it is hard to see any value in it," he said.

The canal would destroy a marine ecosystem and basins that provide nearly a third of Istanbul's fresh water, according to the Union of Chambers of Turkish Engineers and Architects.

Moscow is concerned the canal might not be covered by the Montreux Convention that restricts foreign warships' access to the Black Sea through the Bosphorus Strait.

A Turkish official said in 2019 that the new canal would not be covered by the convention, which dates back to 1936.

This month, amid a build-up of Russia's navy near Ukraine, the Kremlin said President Vladimir Putin told Erdogan on a call that the convention must be observed.

A fourth banker also said that given opposition parties oppose the project, construction could halt if Erdogan's ruling AK Party is ousted. Presidential elections are set for 2023.

"The size of the project is tremendously big. It has reputational risks and loan risk," the person said. "It also still seems like government's pet project."


China, US Agree to $30 Billion Tariff Cut, AI Dialogue

WASHINGTON, DC - SEPTEMBER 25: US President Donald Trump (R) and President of China Xi Jinping (L) speak as they depart following a tour of the National Archives Museum on September 25, 2026 in Washington, DC. Win McNamee/Getty Images/AFP
TT

China, US Agree to $30 Billion Tariff Cut, AI Dialogue

WASHINGTON, DC - SEPTEMBER 25: US President Donald Trump (R) and President of China Xi Jinping (L) speak as they depart following a tour of the National Archives Museum on September 25, 2026 in Washington, DC. Win McNamee/Getty Images/AFP

China and the US have agreed to a $30 billion reciprocal tariff-reduction arrangement and to launch dialogue on AI, under an eight-point consensus reached during Chinese President Xi Jinping's visit to the US, China's Ministry of Foreign Affairs said.

The two sides recognized the work of their economic teams and endorsed steps including the establishment of a trade council, the tariff-reduction arrangement and an extension of outcomes from earlier talks in Kuala Lumpur, the ministry said.

The United ⁠States and China ⁠had earlier agreed to extend by two months a trade truce that was due to expire on November 10, allowing more time to work on a potentially bigger trade deal, US Treasury Secretary Scott Bessent said on Wednesday.

The leaders of ⁠the world's two largest economies ended a three-day summit that showcased personal diplomacy rather than big public breakthroughs. Xi has since landed in Beijing, Chinese state media Xinhua reported on Saturday.

On artificial intelligence, the two sides agreed to establish a dialogue to discuss the technology's risks and benefits, with the next round of discussion set for November, and to set up a communication channel for AI-related incidents, according to the ⁠ministry.

They ⁠also agreed to support each other in hosting the Asia-Pacific Economic Cooperation leaders' meeting and the Group of Twenty summit, with both leaders signaling their intention to attend the gatherings hosted by the other, Reuters reported.

On foreign policy, the leaders agreed that Iran should fulfil its commitment not to develop nuclear weapons, and that no country or entity should impose transit tolls on international waterways, the ministry said. They also recalled that China and the United States fought as allies in World War Two.


Gold Rises, but on Track for Weekly Loss as Fed Rate Hike Expectations Build

FILE PHOTO: A raw gold bar is displayed at Nigeria’s booth at the 8th China International Import Expo (CIIE) venue in Shanghai, China, November 5, 2025. REUTERS/Maxim Shemetov/File Photo
TT

Gold Rises, but on Track for Weekly Loss as Fed Rate Hike Expectations Build

FILE PHOTO: A raw gold bar is displayed at Nigeria’s booth at the 8th China International Import Expo (CIIE) venue in Shanghai, China, November 5, 2025. REUTERS/Maxim Shemetov/File Photo

Gold prices rose on Friday but was on track for a weekly loss, as rising US Treasury yields and growing expectations of Federal Reserve rate hikes weighed on the metal.

Spot gold was up 0.6% at $4,303.19 per ounce by 1210 GMT, but was down about 1.7% so far this week. US gold futures rose 1% to $4,339.

US and Iranian negotiators in New York are seeking a deal that would involve Tehran reopening the Strait of Hormuz and Washington lifting its economic blockade of Iran, sources close to the talks said.

"Gold finds support today as oil prices pull back on renewed hopes for a US-Iran deal," said Nikos Tzabouras, a senior market analyst at Jefferies-owned Tradu.com.

"That said, the precious metal is heading for weekly losses, as higher Fed rates and bond yields raise the opportunity cost of holding gold."

The Fed raised interest rates by a quarter-point last week, its first hike in three years, and flagged more hikes follow. Traders are pricing in a 71% chance of an October hike and a 95% chance of an increase in December, according to the CME FedWatch Tool.

Although gold is traditionally seen as a hedge against inflation, higher rates dampen demand as investors shift to yield-bearing assets.

Gold demand in India picked up modestly this week as lower prices drew in buyers ahead of the festive season.

Oil prices fell, and the dollar eased about 0.3%, making greenback-priced bullion more affordable for holders of other currencies.

"Lingering deficit fears could revive the debasement trend that drives investors toward hard assets like gold. Alongside persistent central bank demand, the precious metal has a credible case for a strong fourth-quarter recovery, should the macro winds begin to shift," said Tzabouras.

Spot silver gained 1.4% to $64.82 per ounce, platinum added 1.7% to $1,777.38 and palladium fell 0.4% to $1,269.77. All three metals were poised for weekly losses.


Dollar Falls as Oil Eases, Yen Rallies on Japan Remarks

US dollar banknotes (Reuters)
TT

Dollar Falls as Oil Eases, Yen Rallies on Japan Remarks

US dollar banknotes (Reuters)

The dollar fell on Friday as oil prices eased, but was poised for a second straight weekly advance on growing rate hike bets, while the yen rallied after Japan said Tokyo and Washington remain committed to the stance behind July's joint intervention.

The dollar was on track to snap a four-day streak of gains as crude prices fell more than 1%.

Global oil prices have eased but still they remain above $100 a barrel, maintaining upward pressure on inflation.

Comments from central bank officials flagging inflation concerns and support for more rate increases after last week's rate hike of 25 basis points have boosted market expectations for a more aggressive path of monetary policy and helped spark a jump in US Treasury yields.

"We've had like a pretty aggressive rally in the dollar over the last couple of days and maybe it's a little stretched, just taking a little breather. So I wouldn't really say that the dollar is really weakening materially today," said Eugene Epstein, head of trading and structured products at Moneycorp in Stamford, Connecticut.

"It's just a combination of those factors that you have not only a slight increase in odds of a second hike before year-end, but also just general bond yields going up and the market getting a bit concerned about that, so that's really what we have, what's been driving the dollar stronger overall."

DOLLAR INDEX POISED FOR BIGGEST DROP IN THREE WEEKS

The dollar index, which measures the dollar against five other currencies, fell 0.34% and was on track for its biggest daily percentage drop since September 3, to 100.95. The euro was up 0.2% at $1.1402 but on pace for a third straight weekly decline.

Expectations for a rate hike from the Fed at its October meeting stood at about 66%, according to CME FedWatch, up from about 58% a week earlier.

On the data front, new orders for US-manufactured capital goods increased more than expected in August and data for the prior month was revised sharply higher, pointing to another quarter of robust growth in business spending as part of artificial intelligence infrastructure is created.

In a separate report, the University of Michigan's Surveys of Consumers said its Consumer Sentiment Index ticked up to 48.1 from the prior reading of 47.8, above the 47.6 estimate of economists polled by Reuters.

Sterling strengthened 0.24% to $1.3247, supported by hawkish comments from Bank of England Governor Andrew Bailey. Yet it remained close to a three-month low hit on Thursday.

YEN STRENGTHENS AS JAPAN STEPS UP INTERVENTION WARNINGS

The Japanese yen strengthened 1.09%, on pace to snap a four-day streak of declines and its biggest daily gain against the dollar since September 7, to 157.13.

The currency rose after Japan's Finance Minister Satsuki Katayama said US President Donald Trump raised concern about yen weakness during a summit with Japanese Prime Minister Sanae Takaichi earlier this week.

Katayama said this reaffirmed the shared US-Japan stance behind July's joint intervention, adding she and Treasury Secretary Scott Bessent would stay in close contact as policymakers stepped up warnings over renewed yen weakness.

Still, the yen was on track for a second weekly fall, after markets judged the Bank of Japan's rate hike last week to a 31-year high and its latest guidance as insufficiently hawkish.

Elsewhere, the dollar strengthened 0.14% to 6.725 versus the offshore Chinese yuan, as a Trump-Xi summit in Washington showed no signs of breakthroughs at a closed-door meeting on thorny issues such as AI, trade, Taiwan and the Iran war.