MoU Aims to Invest in Saudi Education Sector

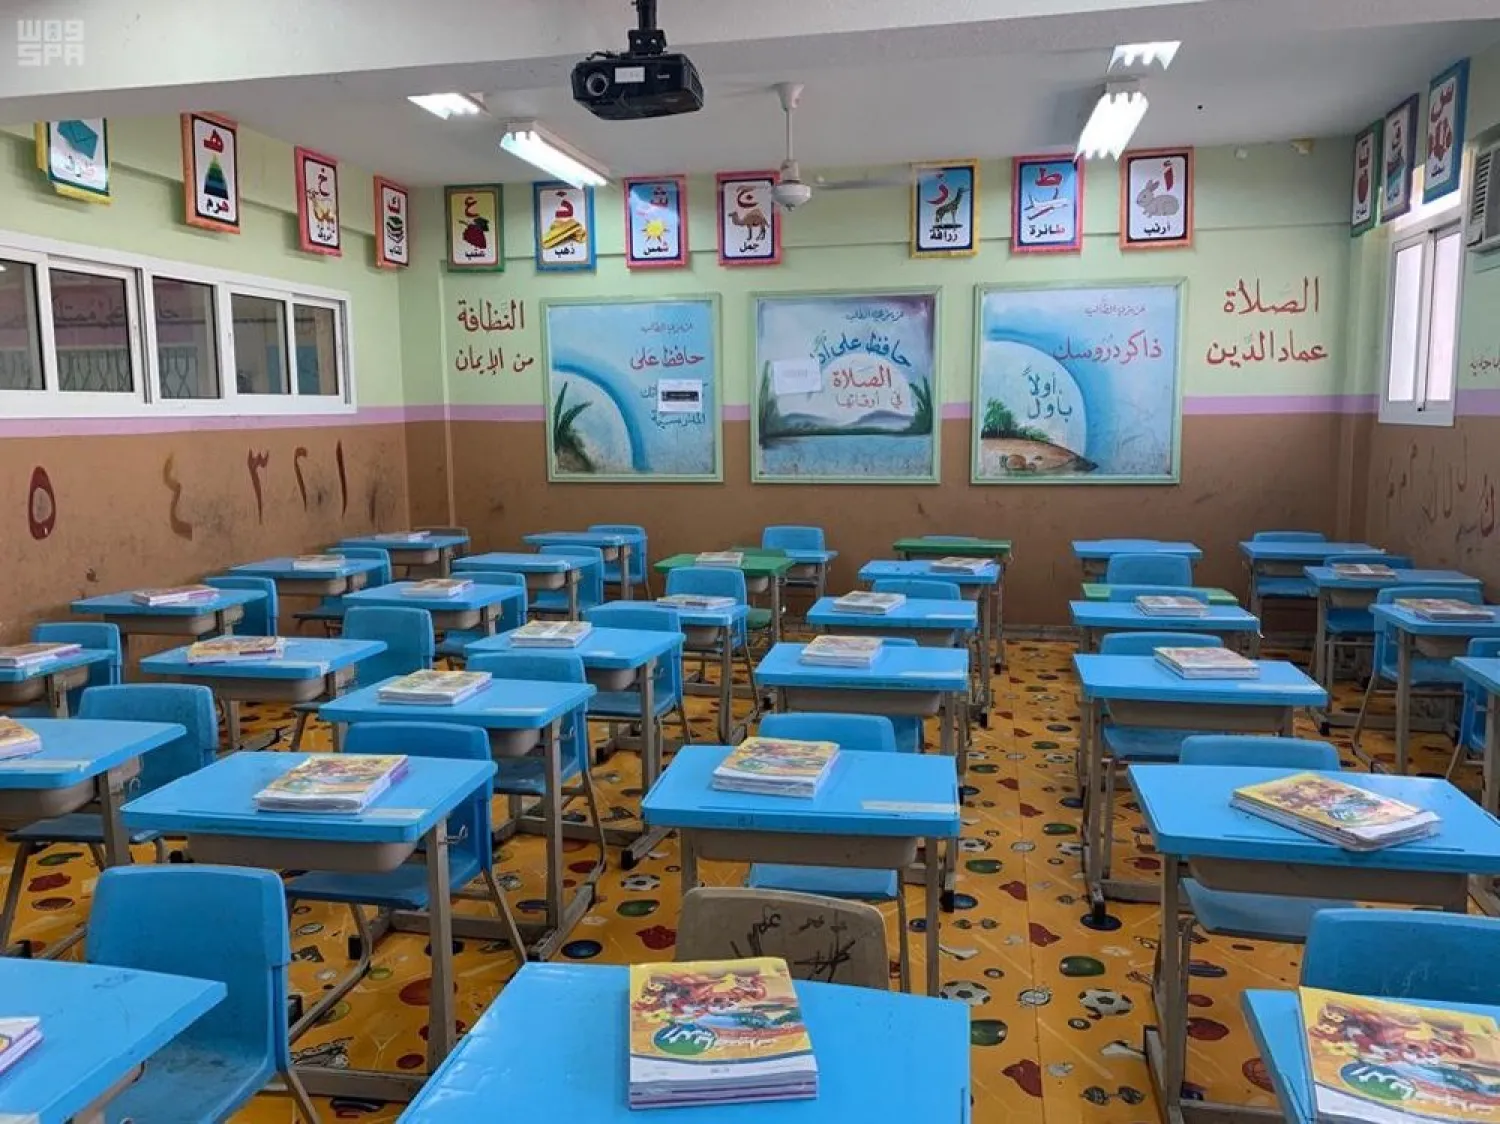
A classroom in Tabuk is readied for the new school year. (SPA)
TT

MoU Aims to Invest in Saudi Education Sector

A classroom in Tabuk is readied for the new school year. (SPA)

The Saudi Ministry of Education, represented by the General Department of Investment and Privatization, signed a memorandum of understanding (MoU) with the Projects Support Fund initiative at the Ministry of Finance.

The MoU aims to expand the scope of lending in the education sector and develop procedures to complete new and existing educational projects in line with Vision 2030.

The agreement includes cooperation in developing additional incentives for loans in the education sector to increase the investment attractiveness of significant projects and apply distinguished financial standards.

It also targets developing and improving procedures by sharing expertise, information, and business and processing funding requests, which increases the efficiency of support to increase competitiveness in the education sector.

The agreement aims to improve the environment and educational facilities, raise the competitiveness of the sector by maximizing its economic impact and provide funding for priority educational projects.

The Ministries of Education and Finance will exchange expertise in implementing joint initiatives, as per the MoU, to bolster the Ministry of Education’s role in supporting the use of local content in its projects.

The Project Support Fund is one of the initiatives of the Ministry of Finance’s stimulus packages, with a capital of SR10 billion allocated to provide financing and support for significant projects in the health, education, and real estate development sectors.


Bolivia Approves $1.9 Billion IMF Deal, Eliminates Diesel Subsidies

A person is counting dollars in La Paz, Bolivia, 10 July 2026. (EPA)
TT

Bolivia Approves $1.9 Billion IMF Deal, Eliminates Diesel Subsidies

A person is counting dollars in La Paz, Bolivia, 10 July 2026. (EPA)

Bolivian lawmakers approved a $1.9 billion loan agreement with the International Monetary Fund on Friday, delivering the conservative government a key victory in its efforts to ease the country's deep economic crisis as unions threatened renewed protests.

Just hours after Congress approved the loan, President Rodrigo Paz announced an immediate end to subsidies for the diesel powering Bolivia’s trucks, buses and tractors — a step toward meeting IMF demands. Gasoline, used mainly in private cars, would remain subsidized for now, though Paz had already scaled back that support in recent months, The Associated Press said.

The Senate ratified the IMF agreement a day after the lower house approved it, clearing the final legislative hurdle for the three-year financing program aimed at replenishing dwindling foreign reserves and stabilizing the ailing economy marked by high inflation and weak growth. The IMF first announced the staff-level agreement in July after months of negotiations with Paz’s market-friendly government, which took power last year after nearly two decades of socialist rule as part of a wave of new Latin American leaders allied with the Trump administration.

The program still requires approval from the IMF’s executive board before funds can be disbursed. Economy Minister Christian Morales told senators that the deal would give other lenders, including the World Bank and the Inter-American Development Bank, greater confidence in the government and help it secure about $5 billion in additional financing.

But the assistance is conditioned on tough economic measures, including the elimination of fuel subsidies, that threaten to reignite unrest in Bolivia, where weeks of road blockades in June and July paralyzed much of the South American nation as demonstrators demanded Paz’s resignation. Congress on Thursday extended for another 90 days a state of emergency that Paz had declared to clear roads during the protests. It allows for military intervention and the suspension of some civil liberties.

The Bolivian Workers’ Central, the country’s main labor federation, and other unions have voiced fierce opposition to the IMF loan, warning that the government spending cuts required under the deal would drive up living costs and deepen hardship for struggling families.

Although Paz’s Christian Democratic Party lacks a majority in Congress, the centrist and right-wing lawmakers that dominate both chambers rallied behind the deal. The Movement Toward Socialism, the party that dominated Bolivian politics after the former coca growers’ union leader Evo Morales won the presidency in 2005, now holds just two of the 130 seats in the lower house and none in the 36-member Senate.

Declining natural gas exports have deprived Bolivia of dollars needed to import gasoline and diesel, contributing to chronic fuel shortages that began in 2023 and have persisted under Paz. The Iran war has pushed up global fuel costs, making fuel subsidies an even greater burden on public finances.

“No one can buy something expensive and sell it cheap,” Paz said in his late-night declaration that diesel in Bolivia would now be sold at international prices.

To cushion the blow, he announced about $79 million in cash assistance for 2.9 million Bolivians, along with loans on preferential terms for truckers, small businesses and producers facing higher diesel costs. He pledged to redirect subsidy spending toward schools, hospitals and roads.


IMF Says Lebanon Economic Activity to Contract Sharply in 2026 as Conflict Weighs

FILE PHOTO: A view of the International Monetary Fund logo at its headquarters in Washington, D.C., US, November 24, 2024. REUTERS/Benoit Tessier/File Photo
TT

IMF Says Lebanon Economic Activity to Contract Sharply in 2026 as Conflict Weighs

FILE PHOTO: A view of the International Monetary Fund logo at its headquarters in Washington, D.C., US, November 24, 2024. REUTERS/Benoit Tessier/File Photo

The International Monetary Fund said on Friday that Lebanon's economic activity is expected to contract significantly in 2026 ‌as the ‌conflict in ‌the ⁠Middle East and broader ⁠regional security tensions continue to damage economic activity, infrastructure ⁠and living conditions, Reuters reported.

The ‌IMF ‌said inflation ‌remained in ‌the double digits and the country's current account deficit ‌had widened, largely due to higher ⁠energy ⁠costs, while infrastructure damage, internal displacement, and deteriorating living standards had added to economic pressures.


Oil Prices Fall on Easing Fears Over Saudi Supply Disruption

FILE PHOTO: Vessels near the Strait of Hormuz, as seen from Musandam, Oman, September 2, 2026. REUTERS/Stringer/File Photo
TT

Oil Prices Fall on Easing Fears Over Saudi Supply Disruption

FILE PHOTO: Vessels near the Strait of Hormuz, as seen from Musandam, Oman, September 2, 2026. REUTERS/Stringer/File Photo

Oil prices fell 2% on Friday, extending losses for a third straight session as easing concerns over Saudi supply disruptions outweighed anxiety about a widening of conflict across the Middle East.

Brent crude futures fell by $2.14, or 2%, to $102.68 a barrel by 0806 GMT. US West Texas Intermediate futures fell $1.83, or 1.8%, to $100.08, Reuters reported.

Benchmark Brent prices are on track for their first weekly loss in three.

Prices climbed to close to four-month highs earlier in the week after sources said crude loadings ⁠at Saudi Arabia's Red Sea export hub of Yanbu had been suspended and Riyadh cancelled some deliveries to Europe after its East-West pipeline was damaged in an attack last week.

However, prices have cooled since on reports that Saudi Arabia was seeking to restore about half the capacity of its East-West oil pipeline within days.

Saudi Arabia has sold about 60 million barrels of crude from its Gulf port of Ras Tanura inside the Strait of Hormuz for loading via ship-to-ship transfer at the Omani port of Sohar this month and next, multiple trade sources said on Friday.

The rebound in Saudi Aramco's exports from inside the Gulf to between 1 million to 1.5 million barrels per day on average, similar to or slightly higher than August's levels, has cooled global oil prices as it could make up for some of the ⁠volume lost at its port of Yanbu.

Chinese and South Korean refiners are among the top buyers of the spot supplies, while some volumes will be going to India and Japan, said the sources, who spoke on condition of anonymity.

"Recent efforts ‌to restore Saudi export capacity have reduced some of the immediate supply ‌anxiety," said Priyanka Sachdeva, head of market insights at Phillip Nova.