Price of EU Wheat Rises After First French Sale to Egypt https://english.aawsat.com/home/article/3388031/price-eu-wheat-rises-after-first-french-sale-egypt
Price of EU Wheat Rises After First French Sale to Egypt
European wheat prices rose after Egypt bought French wheat for the first time in almost a year. (Reuters)
Paris, Cairo - Asharq Al-Awsat
TT
TT
Price of EU Wheat Rises After First French Sale to Egypt
European wheat prices rose after Egypt bought French wheat for the first time in almost a year. (Reuters)
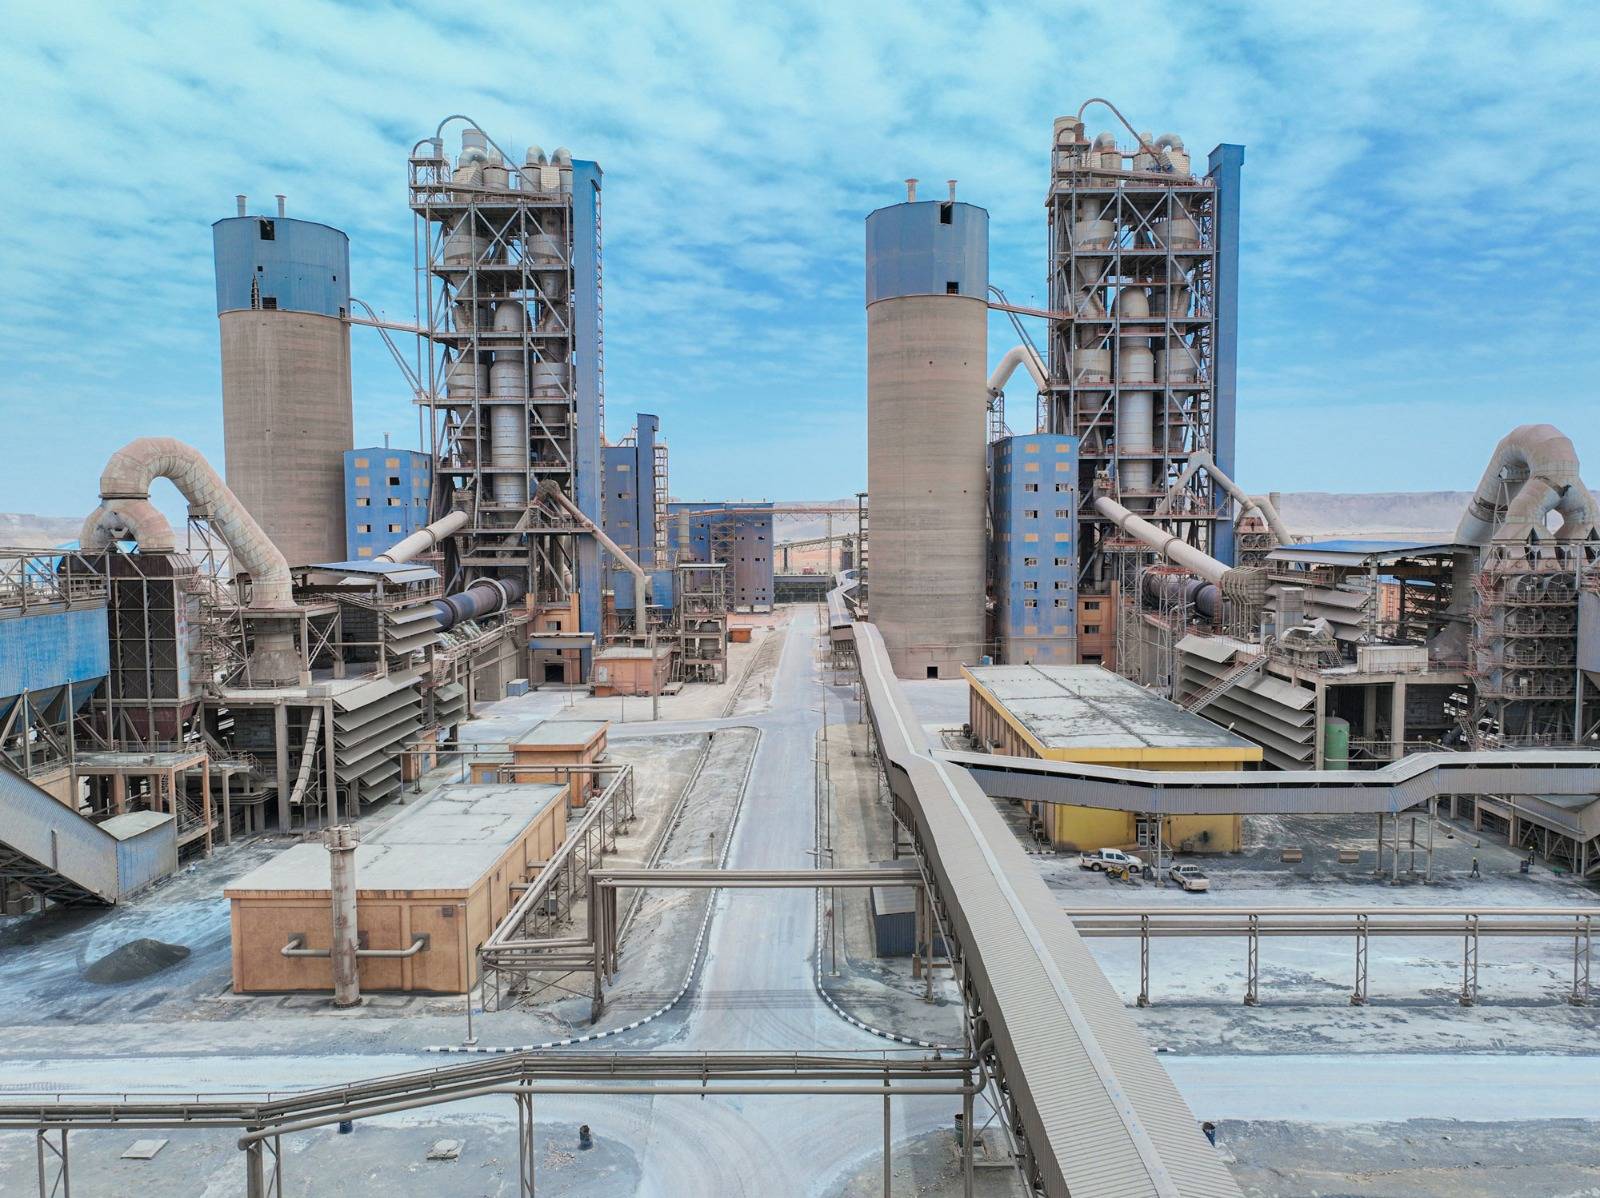
European wheat prices rose on Wednesday after Egypt’s first purchase of French wheat in almost a year raised hopes of further exports in a market that has been dominated by Black Sea origins.
Benchmark March milling wheat on Paris-based Euronext closed 0.6 percent up at 282.25 euros ($320.10) a ton.
Egypt’s state grains buyer, the General Authority for Supply Commodities (GASC), bought 300,000 tons of wheat in an international tender for shipment Feb. 15 to Mar. 3, including 60,000 tons of French wheat, it said on Wednesday.
The last time GASC bought French wheat was in early February.
Since then, the office favored cheaper offers for Black Sea wheat origins including Russia, Romania, and Ukraine.
Egypt’s government imports of wheat have amounted to 5.5 million tons in 2021, in addition to about 3.5 million tons secured locally from farmers.
The price of subsidized sugar in Egypt will increase to 10.5 Egyptian pounds ($0.6671) per kilogram from January 1, 2022, up from 8.50 pounds currently, Supply Minister Ali Moselhy said on Wednesday.
The supply ministry last week said Egypt has sufficient sugar reserves to cover 3.5 months of consumption.
Bahrain's Alba Says Produces 1.3 Million Tons Per Year of Aluminiumhttps://english.aawsat.com/business/5318928-bahrains-alba-says-produces-13-million-tons-year-aluminium
Bahrain's Alba Says Produces 1.3 Million Tons Per Year of Aluminium
The Bahraini capital (Reuters)
Aluminium Bahrain, known as Alba, is currently producing aluminium at an annualized rate of 1.3 million metric tons, versus a pre-Iran war capacity of around 1.6 million tons, its CEO said on Wednesday.
Alba, which describes itself as the world's biggest aluminium smelter on one site, shut down production lines 1, 2, and 3 following the outbreak of the war as the closure of the Strait of Hormuz restricted exports. The plant was then hit by an Iranian attack in late March.
Alba is now operating lines 4, 5 and 6 at its smelter, equivalent to 1.3 million tons per year, Ali Al Baqali told Reuters on the sidelines of the Fastmarkets Aluminium Conference in Budapest.
He described the Iranian strike as a "small, minor attack.”
"We got damages and we already repaired them. Nothing needed," Al Baqali said, adding that Alba had been covered by insurance.
Its overall capacity will return to 1.6 million tons when it completes its acquisition of French smelter Aluminium Dunkerque in the next couple of months, Al Baqali said.
To maintain production, Alba is bringing in 300 to 350 trucks carrying raw material alumina on a daily basis, the CEO said.
"We are managing to receive around 7,000 metric tons of alumina every day," Al Baqali said, describing the logistics operation as "expensive,” but offset by the high London Metal Exchange aluminium price and premiums for physical metal.
Alba is exporting metal via the Saudi port of Jeddah on the Red Sea and from Sohar in Oman, Al Baqali said, as hostilities in the Middle East continue.
Gold Gains with Fed Rate Decision in Spotlighthttps://english.aawsat.com/business/5318880-gold-gains-fed-rate-decision-spotlight
A shop attendant displays pairs of gold bracelets for Chinese weddings during a media preview of the Chow Tai Fook Jewellery Group flagship store soft opening, in Hong Kong, China, February 11, 2026. (Reuters)
TT
TT
Gold Gains with Fed Rate Decision in Spotlight
A shop attendant displays pairs of gold bracelets for Chinese weddings during a media preview of the Chow Tai Fook Jewellery Group flagship store soft opening, in Hong Kong, China, February 11, 2026. (Reuters)
Gold prices ticked up on Wednesday as oil prices eased, while market participants looked ahead to the US Federal Reserve's policy decision, with a rate hike largely priced in.
Spot gold was up 0.8% at $4,328.39 per ounce, as of 0310 GMT, after scaling a more than one-month low on Monday. US gold futures for December delivery were down 0.9% at $4,369.50.
"A hawkish Fed could pull gold down, while any soft messaging may ease bets on hikes and help the metal recover. Traders are also monitoring oil prices and developments in the Middle East," said Frank Walbaum, a market analyst at trading platform Naga.com.
Gold is often seen as an inflation hedge, but higher rates increase the opportunity cost of holding non-yielding bullion.
Oil prices fell after an unexpected build in US crude inventories, while investors assessed supply risks after Saudi Arabia suspended oil loading at its Yanbu port.
Traders are pricing in a 92.4% chance of at least a 25-basis-point US rate hike later in the day, according to CME FedWatch. The policy decision will be followed by a press conference from Fed Chair Kevin Warsh.
On the geopolitical front, Saudi Arabia air defenses destroyed a Houthi drone south of Makkah before it entered prohibited airspace over the holy city, a spokesperson for the Saudi-led military coalition in Yemen said.
Commerzbank said it was somewhat surprising that gold prices had not come under greater pressure so far. It noted that gold's resilience may be supported by persistent fiscal concerns, reflected in elevated long-term government bond yields, as well as a recent rise in US political risks.
Among other metals, spot silver rose 1.5% to $64.60 per ounce, platinum edged 0.7% higher to $1,788.25, while palladium gained 1.6% to $1,309.80.
Saudi Cement Companies Balance Investment Gains, Demand Prospectshttps://english.aawsat.com/business/5318873-saudi-cement-companies-balance-investment-gains-demand-prospects
Saudi Cement Companies Balance Investment Gains, Demand Prospects
Saudi Cement Company’s factory. (Saudi Cement Company)
Saudi Arabia’s listed cement companies maintained high profitability in the first half of 2026 despite wide disparities in performance and differing sources of growth. Combined net profit stood at about SAR 1.1 billion ($293.9 million), down a modest 2.4% from a year earlier, while the sector recorded profit growth in the second quarter.
The results show that cement and clinker sales were not the only drivers. Investment income, gains from the revaluation and disposal of some underused assets, and tighter control of expenses and financing costs supported several companies. Those farther from major demand centers faced greater pressure from transportation and logistics costs, financing burdens and excess production capacity.
While major producers, led by Yamama Cement Co., Saudi Cement Company and Eastern Province Cement, continued to lead sector profits, the results raise a more important question for the period ahead: To what extent do these profits reflect a sustainable improvement in operating activity, and how much have they benefited from investment and non-recurring items?
Thirteen companies posted first-half profits. Yamama Cement led with net profit of SAR 265.39 million, up 0.88% from SAR 263.08 million a year earlier. Saudi Cement followed with SAR 202.2 million, down 0.88% from SAR 204 million, while Eastern Province Cement ranked third, with profit rising 12.8% to SAR 141 million from SAR 125 million.
Second-quarter net profit for the sector reached SAR 508.7 million ($135.7 million), up 2.27% from SAR 497.4 million ($132.6 million) a year earlier. Nine companies reported profit growth, seven posted declines, while Al-Jouf Cement Company deepened its net losses.
Mohamed Hamdy Omar, CEO of G.WORLD, told Asharq Al-Awsat that the results presented a mixed picture: While the overall figures demonstrate the resilience of financial buffers and the ability of leading companies to adapt, they also reveal wide operational and structural disparities across the sector.
Omar identified four main factors supporting first-half profits, led by non-operating items. Cement and clinker sales were not the sole drivers of profitability, with gains from the fair-value revaluation of investments and capital gains from the disposal of some underused assets also supporting results.
Riyadh Cement Company plant. (Riyadh Cement Company)
He cited Yamama Cement as a prominent example, saying it benefited from the sale of equipment from the old plant’s production lines, as well as investment income.
Spending efficiency and financing-cost management also supported major companies. Saudi Cement and Eastern Province Cement reduced selling and distribution expenses and controlled financing costs, helping limit pressure on profit margins.
Companies based in Riyadh and the Eastern Region also benefited from proximity to major demand centers and projects, Omar said. The accelerated implementation of infrastructure projects and urban expansion provided operating volumes that helped them better absorb cost fluctuations.
Performance gap
Companies farther from major demand centers faced greater operational and logistical challenges. Omar pointed to an approximately 96.4% decline in Tabuk Cement Company’s profit and deeper losses at Al-Jouf Cement, attributing this to higher transportation and logistics costs and heavier financing and debt-servicing burdens among highly leveraged companies or those with lease-based financing structures.
Omar noted that the gap underscored the importance of geography and company size in determining competitiveness, particularly in a market characterized by excess production capacity and uneven regional demand.
He cautioned that relying on asset sales or investment portfolio revaluations to support profits was temporary and could not guarantee sustainable growth.
The real test would be a recovery in domestic demand and improvement in average selling prices per ton, he added.
Lower interest rates could ease debt-servicing burdens, potentially improving net margins and providing greater liquidity for rehabilitation and expansion.
Omar noted that mergers and acquisitions could become a more pressing strategic option as the performance gap between large and small producers widens, helping companies strengthen pricing power, reduce administrative and general expenses and address excess production capacity.
The ability to sell surplus production in neighboring regional markets will remain crucial in the second half, he stressed, alongside energy costs and feedstock-use efficiency.
لم تشترك بعد
انشئ حساباً خاصاً بك لتحصل على أخبار مخصصة لك ولتتمتع بخاصية حفظ المقالات وتتلقى نشراتنا البريدية المتنوعة