G20 Announces Global Urban Resilience Fund

U20 chair and President of the Royal Commission for Riyadh City Fahd Al-Rasheed. Photo courtesy of Urban 20 Riyadh website
TT

G20 Announces Global Urban Resilience Fund

U20 chair and President of the Royal Commission for Riyadh City Fahd Al-Rasheed. Photo courtesy of Urban 20 Riyadh website

The Urban 20, a G20 Engagement Group, announced on Friday that it is working to create a Global Urban Resilience Fund in response to the coronavirus pandemic.

The fund is the first of its type developed by cities.

“We have the opportunity right now to learn from the impact of COVID-19, to study how to build cities which are more resilient and agile,” said President of the Royal Commission for Riyadh City Fahd Al-Rasheed.

“The cities of the U20 have taken the lead to develop a fund for city action to combat the pandemic and mitigate future urban shocks. The goal of the fund is to accelerate the transmission of new learning and ideas for a more secure future for all urban residents,” he added.

The Fund comes as a response to the findings of the U20 Special Working Group (SWG) on COVID-19, which was set up by the U20 Chair city, Riyadh, together with co-chair cities Rome and Buenos Aires.

“The challenge of our times is the fight against the pandemic. A struggle that is not only a challenge to restore the best health conditions; but, more, it is remedying the economic consequences of the pandemic,” said Mayor of Rome Virginia Raggi commented.

“Cities cannot tackle this alone: solid support from states is needed, but, at the same time, it is necessary to pool resources and create new tools. The Global Urban Resilient Fund represents an intelligent way to meet these needs, and the commitment of the next Italian U20 Presidency will be to carry this forward and make it concrete.”

Horacio Rodríguez Larreta, Mayor of Buenos Aires, the founding city of the U20, said: “Local government budgets will not be enough to carry out the sustainable urban reconstruction and job creation that will need to take place in the coming years.”

“We need to use our collective voice to facilitate cities’ access to stimulus and recovery packages and to support innovative financial instruments that favor “green” financing, such as the Global Urban Resilient Fund," a statement issued by U20 quoted him as saying.

The Special Working Group brought together a further ten member cities; Amsterdam, Helsinki, Houston, Izmir, Los Angeles, Madrid, Mexico City, Rio De Janeiro, Sao Paulo and Tshwane, along with seven Knowledge Partners; University of Pennsylvania, Coalition for Urban Transition, the Chicago Council on Global Affairs, OECD, International Finance Corporation (World Bank Group), Agence Française de Développement and Université Gustave Eiffel.

The need for a cities fund arose from the Special Working Group on COVID-19 which gathered 32 case studies and surveyed 21 cities covering a population size of over 75 million, said the statement.
In its report, the Special Working Group recommended the creation of a Global Urban Resilience Fund to address the dual challenge that the pandemic crisis hit all cities, but cities are not financially empowered to respond or build resilient city infrastructure of the magnitude required.

The goals of the Fund are to act as a shared and accessible Fund for cities, governed by cities; and provide agile disaster response funds for cities for effective, transparent and rapid emergency actions; access to critical infrastructure investments that increase the resilience of cities; and financial products and instruments including grants and loans to cities while providing new opportunities for investors.

The ultimate aim is to unlock and develop new financial instruments and funding mechanisms for cities currently unavailable through international finance architecture, the statement added.


Euro Zone Yields Fall after Iran Raises Prospect of Hormuz Reopening

Euro banknotes (Reuters)
TT

Euro Zone Yields Fall after Iran Raises Prospect of Hormuz Reopening

Euro banknotes (Reuters)

Euro zone bond yields fell for a second straight day on Tuesday, hitting their lowest in almost two weeks after Iran raised the prospect of reopening the Strait of Hormuz and Washington hinted it could restart talks with Tehran, pushing oil prices lower.

Germany's 10-year bond yield, the benchmark for the bloc, fell 1 basis point to 3.44% after rising as much as 4 bps earlier in the session. It fell 7 bps on Monday as energy prices retreated.

A senior Iranian official told Reuters that the strait, which carried about a fifth of global energy supplies before the war, could reopen within seven days if the US also lifts its blockade of Iranian ports.

The official added that Iran's delegation to a UN meeting in New York this week has full authority to revive diplomacy over the conflict.

US Secretary of State Marco Rubio told NBC's "Today" show that Washington was open to speaking with Tehran.

The dip in energy prices helped pull yields lower globally after a surge in recent weeks fuelled by expectations of further interest-rate hikes to combat energy-driven inflation. Traders are pricing in around 35 bps of additional European Central Bank tightening this year, down from 40 bps on Friday.

Germany's two-year bond yield, which is sensitive to interest-rate expectations, fell 1 bp to 3.19%, following a 6-bp drop on Monday.

Rabobank senior rates strategist Lyn Graham-Taylor said lower oil prices following the Iranian comments were weighing on bond yields.

Brent crude futures were last down 1% to $100 a barrel after earlier falling to $97.40, the lowest in two weeks.


Libya's NOC Says Sharara Crude Pipeline Closure Losses at 130,000 bpd

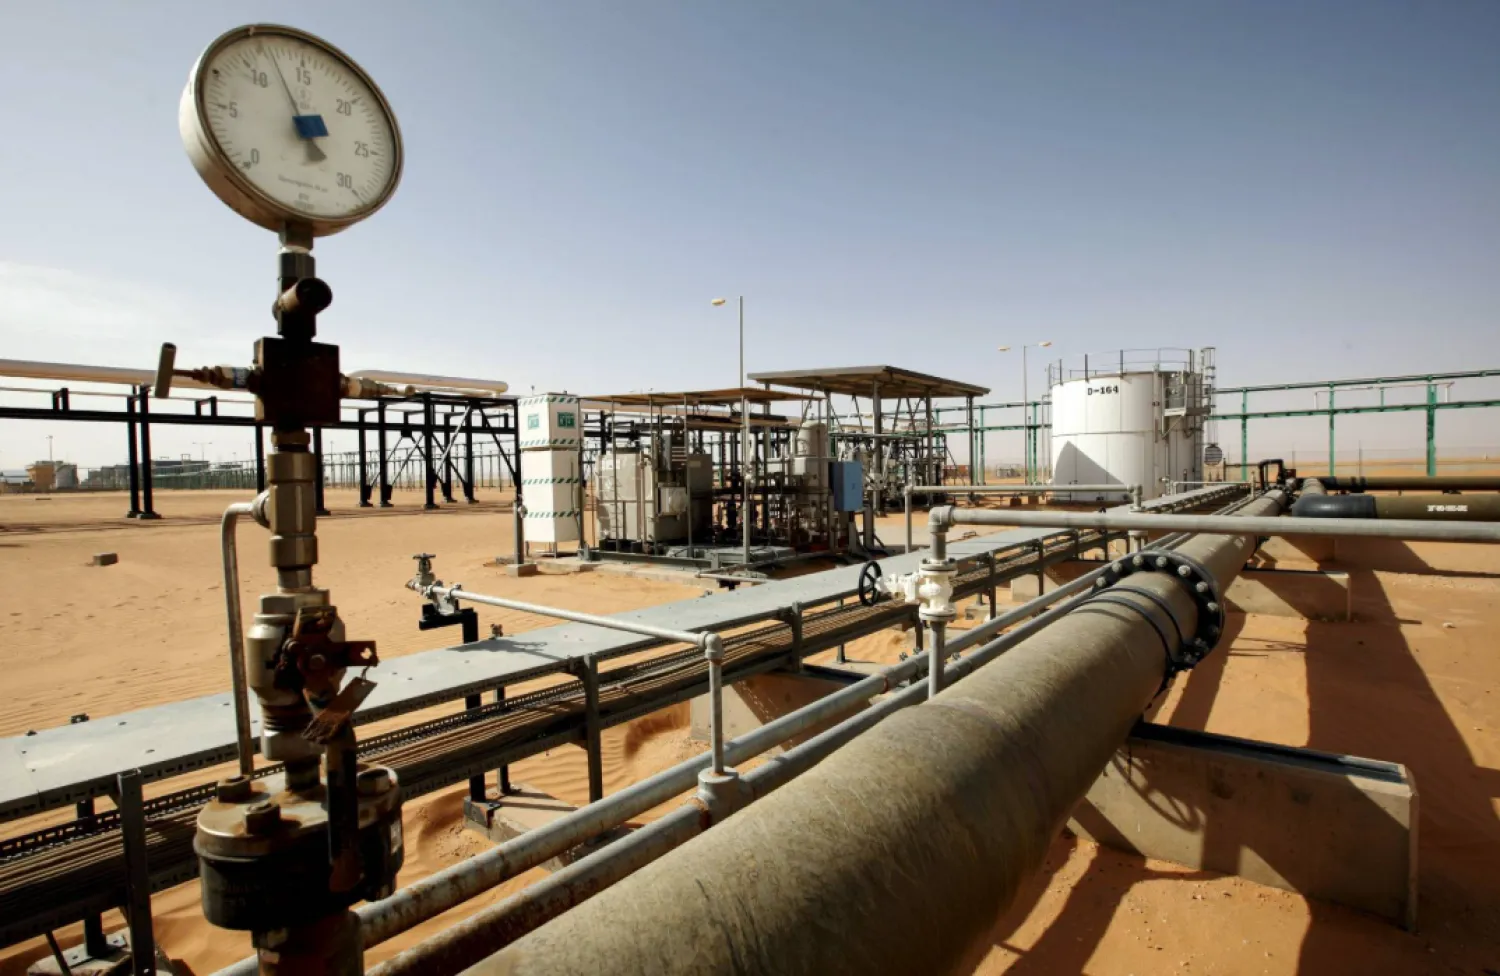
General view of the Sharara oil field in Libya (Reuters)
TT

Libya's NOC Says Sharara Crude Pipeline Closure Losses at 130,000 bpd

General view of the Sharara oil field in Libya (Reuters)

Libya's National Oil Corporation said on Tuesday that the Sharara-Zawiya crude loading pipeline closure has led to daily losses of about 130,000 barrels per day, Reuters reported.

An armed military group closed valve seven on the Sharara crude pipeline to Zawiya port on Monday, resulting in a significant decline in production at the Sharara oilfield, the National Oil Corporation said in a statement.


Sources: Saudi Arabia Restarts East-West Oil Pipeline

FILE PHOTO: A model of an oil pump is seen in front of a Saudi Arabian flag in this illustration taken January 9, 2026. REUTERS/Dado Ruvic/Illustration/File Photo
TT

Sources: Saudi Arabia Restarts East-West Oil Pipeline

FILE PHOTO: A model of an oil pump is seen in front of a Saudi Arabian flag in this illustration taken January 9, 2026. REUTERS/Dado Ruvic/Illustration/File Photo

Saudi Arabia has restarted operations at its East-West Pipeline and could resume exports from the Red Sea port of Yanbu later on Tuesday, three sources briefed on the matter said.

Drone attacks forced Saudi Arabia to shut its East-West Pipeline on September 13, halting crude loadings at the kingdom's Yanbu port.

The resumption of supplies on Tuesday helped to drive selling on global oil markets, traders said. Brent crude futures fell by more than $2 a barrel to its lowest since September 8.

Two trading sources said traders were getting ready for Saudi oil loadings by moving tankers to Egypt's Mediterranean Port Said for ship-to-ship transfers and also to Sidi Kerir.