Egypt Harvested Over 700,000 Wheat Feddan since April

Egypt's strategic wheat reserves last until the end of next January (Reuters)
TT

Egypt Harvested Over 700,000 Wheat Feddan since April

Egypt's strategic wheat reserves last until the end of next January (Reuters)

Egypt has harvested more than 700,000 feddans of local wheat since the harvest season on April 1.

Egyptian Finance Minister Mohamed Maait said the country allocated $59.69 million for a down-payment to state grain buyers to purchase wheat from local farmers.

Among the world's biggest wheat importers, Egypt is heavily reliant on shipments from Ukraine and Russia, and its government has been seeking alternative supplies from countries including India and France.

Minister of Supply Ali al-Moselhi said Egypt has 2.6 million tons of imported wheat and targets to collect 5.5-6 million tons of local grain; therefore, strategic wheat reserves can last for 6-9 months.

Meanwhile, the Food and Agriculture Organization (FAO) said Ukraine is the eighth wheat producer with about 25 million tons and ranks fifth in corn production with 3.3 million tons.

FOA said that nearly 25 million tons of grains were stuck in Ukraine with blockades at ports due to the war with Russia

Food prices remain high, despite the drop, due mainly to the combination of military conflict in Ukraine and sanctions against Russia.

The FAO's food price index was down just 0.8 percent compared to March.

FAO Deputy Director, Markets and Trade Division Josef Schmidhuber described the situation as "grotesque.”

“We see at the moment in Ukraine with nearly 25 mln tons of grain that could be exported, but that cannot leave the country simply because of lack of infrastructure, the blockade of the ports."

Another concern was that about 700,000 tons of grain may have "disappeared" in Ukraine.

Schmidhuber cautioned that there were no "statistics" about possible theft.

"There's anecdotal evidence that Russian troops have destroyed storage capacity and that they are looting the storage grain that is available," he said. "They are also stealing farm equipment."

The absence of Ukraine as a supplier of grain will put the food supply of the population of Africa in particular at risk, according to the German Kiel Institute for the World Economy (IfW).

IfW trade researcher Henrik Mahlkow explained that due to the war, Ukraine is likely to be initially cut off from the global economy after trade routes have been cut, infrastructure destroyed, and all remaining production factors are likely to be directed towards a war economy.

"As the country is one of the most important grain exporters in the world, and especially relevant for Africa. Losing Ukraine as a supplier will noticeably worsen the supply situation across the continent," said Mahlkow.

According to the institute, the consequences would also be felt in Germany, albeit far less dramatically.

The institute's economists made a trade model to simulate Africa's long-term consequences of an end of exports of Ukrainian wheat and other cereals for food production, such as corn or sorghum.

The model calculations did not include cereals used as animal feed, such as corn. Accordingly, Tunisia and Egypt, in particular, would be negatively affected.

Egypt would import over 17 percent less wheat and almost 19 percent less other cereals, while South Africa would import 7 percent less wheat and over 16 percent less other grains.


Saudi Telecom Companies' Revenues Rise to $22 Billion in 9 Months

General view of Riyadh in the early evening hours (Reuters)
TT

Saudi Telecom Companies' Revenues Rise to $22 Billion in 9 Months

General view of Riyadh in the early evening hours (Reuters)

Saudi Arabia's three listed telecom operators posted combined revenues of more than $22.2 billion (83.42 billion riyals) in the first nine months of 2026, up 3.67% from a year earlier, as growing demand for consumer and business services, an improved revenue mix and expanding subsidiary operations fueled growth.

Revenues rose from about $21.46 billion (80.47 billion riyals) a year earlier, supported by growth in carrier and operator services alongside consumer and enterprise businesses.

stc dominated the sector, generating $16 billion (60.1 billion riyals), or roughly 72% of the three operators' combined revenues, up 3.75% year-on-year.

Mobily recorded a 5.07% revenue increase to $4.05 billion (15.19 billion riyals), while Zain Saudi Arabia posted a modest 0.57% rise to $2.17 billion (8.14 billion riyals).

Four telecom companies are listed on the Saudi stock market. stc, Mobily and Zain Saudi Arabia close their financial years in December, while Etihad Atheeb Telecommunication Co. (GO) ends its fiscal year in March.

Profits fall despite revenue growth

Despite rising revenues, the three operators' combined net profit slipped 2.07% to about $3.78 billion (14.17 billion riyals) in the first nine months of 2026, down roughly 300 million riyals from 14.47 billion riyals a year earlier.

The decline was driven by stc, whose net profit fell 5.71% to 10.92 billion riyals from 11.58 billion riyals in the same period of 2025.

Its rivals fared better. Mobily's net profit climbed 7.68% to 2.71 billion riyals from about 2.51 billion riyals, while Zain Saudi Arabia recorded a 45% surge to 541 million riyals from 373 million riyals.

stc's earnings were weighed down by nonrecurring items, lower finance income and higher financing costs, even as revenues and operating profit grew. Excluding nonrecurring items in both periods, the company said net profit rose 2.6%.

Mobily benefited from stronger revenues and improved gross profit. Zain Saudi Arabia's earnings were lifted by a better revenue mix, lower financing costs and a one-off gain from the Universal Service Fund.

Strong demand, uneven profits

The results underscore a widening gap between revenue growth and profitability across Saudi Arabia's telecom sector, where financing costs, operating expenses and nonrecurring items continue to shape earnings.

Suleiman Al-Humaid Al-Khaldi, a financial and economic expert, financial markets analyst and member of the Saudi Economic Association, told Asharq Al-Awsat that the results reflected resilient demand and expanding telecom operations as Saudi Arabia accelerates its digital transformation.

He said the rise in combined revenues to 83.42 billion riyals confirmed continued business growth, even as profitability diverged among the three operators.

But higher revenues do not necessarily deliver proportionate gains in net profit, he said, pointing to financing costs, operating expenses and nonrecurring items.

With stc generating about 72% of the operators' combined revenues, its performance has an outsized impact on their overall financial results, even when rivals report stronger profits, Al-Khaldi said.

He cautioned against interpreting stc's reported earnings decline as a sign of operating weakness.

The company's operating profit rose 4.1%, while adjusted net profit grew 2.6% after excluding nonrecurring items in both periods, indicating that its core operations continued to expand and deliver positive results.

Mobily's stronger earnings reflected revenue growth and improved gross profit, while Zain Saudi Arabia benefited from a better revenue mix, lower financing costs and one-off income from the Universal Service Fund, he said.

Al-Khaldi stressed the need to distinguish recurring operating earnings from exceptional gains when assessing the sustainability of profit growth, particularly after Zain Saudi Arabia reported a third-quarter profit decline.

He said stc's underlying operations remained solid despite pressure from lower finance income, rising financing costs and differences in the impact of nonrecurring items.

Stc's share price fell from 42 riyals to 39 riyals, a decline of about 7.1% over the period under review, which Al-Khaldi said suggested relative price resilience. He cautioned, however, that the time frame mattered when comparing the stock with other Saudi blue chips.

A company's investment strength should not be judged on reported net profit alone, he said. The sustainability of operations, earnings quality and capacity to pay cash dividends were equally important, reinforcing stc's standing as a leading Saudi stock.

Looking ahead, Al-Khaldi forecast continued growth and improving profitability across the telecom sector, driven by expanding digital services and stronger demand for telecommunications and information technology solutions.

He also expected stc to deliver positive fourth-quarter and full-year 2026 results, surpassing the corresponding periods of 2025 as its core businesses continued to grow.

Rising revenues, squeezed margins

Mohamed Hamdy Omar, chief executive of G.World for Studies, said Saudi telecom operators' nine-month results exposed a clear disconnect between revenue growth and earnings.

Combined revenues rose 3.67% to 83.42 billion riyals, while net profit fell 2.16% to about 14.17 billion riyals, pointing to pressure on profit margins despite continued business expansion, he told Asharq Al-Awsat.

Omar identified three factors behind the divergence: financing costs, higher operating expenses and nonrecurring items.

First, telecoms remain a capital-intensive business. Network upgrades, wider fifth-generation (5G) coverage and investments in data centers and digital infrastructure require substantial spending, with some projects taking years to generate their targeted returns.

Second, the shift from traditional telecom services to technology-driven offerings is pushing up operating costs.

Expanding into cloud computing, cybersecurity, artificial intelligence and the Internet of Things requires investment in development, specialized talent and operations, adding near-term costs even as it strengthens long-term competitiveness.

Third, one-off items can distort reported earnings.

Omar pointed to stc's 2.6% adjusted net profit growth after excluding nonrecurring items in both periods, saying the figure highlighted the importance of separating underlying operating performance from headline profits.

The earnings at Mobily and Zain Saudi Arabia also revealed differences in how effectively operators improve their revenue mix, control costs and capitalize on business opportunities, he said.

The industry's next challenge will not simply be to generate more revenue, but to improve efficiency and turn heavy investment into cash flow and sustainable returns without eroding margins, Omar added.

Omar expects Saudi Arabia's telecom sector to maintain its growth momentum through the final quarter of 2026 and into 2027, supported by the expanding digital economy and the kingdom's accelerating technological transformation.

But the engines of growth are changing.

Rather than competing primarily through traditional connectivity services and subscriber growth, operators are increasingly turning to higher-value digital and technology offerings, he said.

Data centers, cloud computing and infrastructure supporting artificial intelligence applications stand out as major opportunities as demand rises for data processing, storage and transmission capacity.

Operators with advanced networks, extensive customer bases and established operational expertise are well positioned to capitalize on that shift, Omar said.

The enterprise and institutional market is also poised to become a major revenue driver as companies and government agencies seek more cybersecurity, cloud, Internet of Things and digital infrastructure management solutions.

Telecom operators that successfully evolve into integrated technology solutions providers will be better placed to diversify revenues and strengthen profitability, he added.

Saudi Arabia's megaprojects, expanding smart cities and growth in tourism, manufacturing, logistics and e-commerce should provide further opportunities for advanced connectivity and digital infrastructure in the coming years.

The transition will not be without risks.

Omar warned that high capital expenditure, rising financing costs, price competition in traditional services and lengthy investment payback periods could continue to weigh on profitability, particularly in data centers and artificial intelligence.

He expects telecom revenues to keep rising in the fourth quarter of 2026, but said stronger earnings would hinge on operators' ability to rein in expenses, manage financing costs and improve investment returns.

Competition in advanced digital services is likely to intensify in 2027, favoring companies that can diversify their income and make better use of existing infrastructure, he said.

Ultimately, Omar said, Saudi Arabia's telecom industry is undergoing a gradual shift from traditional connectivity toward a broader role in the data economy.

Its future competitive strength will depend less on subscriber numbers alone and more on how successfully operators turn their networks, assets and technological capabilities into higher-value digital services with sustainable profit margins.

China’s Factory Activity Shrinks in October, Third Contraction in Four Months

 Women shop for fashion accessories at a bazaar held in a popular shopping district in Beijing, Wednesday, Oct. 28, 2026. (AP)
Women shop for fashion accessories at a bazaar held in a popular shopping district in Beijing, Wednesday, Oct. 28, 2026. (AP)
TT

China’s Factory Activity Shrinks in October, Third Contraction in Four Months

 Women shop for fashion accessories at a bazaar held in a popular shopping district in Beijing, Wednesday, Oct. 28, 2026. (AP)
Women shop for fashion accessories at a bazaar held in a popular shopping district in Beijing, Wednesday, Oct. 28, 2026. (AP)

China's factory activity dropped in October, its third contraction in four months, a government survey showed on Saturday, hurt by soft demand goods at home as well as signs of weakness in exports.

Economists called on the government to do more to support growth after the figures, which highlighted how exports, which have powered higher for much of this year, may not have sufficient strength to offset long-stagnant consumer spending.

"Insufficient demand is increasing downward pressure on the economy," said Zhang Liqun, an analyst with the ‌China Federation of ‌Logistics & Purchasing.

The official manufacturing purchasing managers' index (PMI) fell to 49.3 from ‌50.1 ⁠in September, according ⁠to data from the National Bureau of Statistics. That missed a forecast for 50.0 from a Reuters poll, though the first month of a quarter is typically the weakest.

China's trade surplus with the world is on track to top last year's $1.2 trillion due to strength in exports. But in October, factory activity weakened as overseas Christmas-related orders, which were front-loaded in September, cooled. It was also hurt when consumer spending, which climbed during China's long National Day holiday in the ⁠first week of October, fizzled out afterwards.

Sub-indexes for new orders overall ‌and for new export orders both stayed in contraction ‌territory in October. Production and purchasing activity also slipped into contraction from expansion.

MORE SUBSIDIES COULD HELP

Zhang Zhiwei, ‌chief economist at Pinpoint Asset Management, said that if external demand weakens in 2027, "China ‌will need more significant policy support to boost domestic demand."

Lu Zhe, chief economist at Soochow Securities, called for expanding subsidies for mortgage interest payments "to shore up household confidence and anchor sentiment."

He added that extending subsidies for loan interest payments to investment projects would help alleviate the current shortage of viable fixed-asset ‌investments.

The non-manufacturing PMI, which covers services and construction, also dropped, to 49.7 from 50.2 in September.

The readings are compiled based on ⁠purchasing managers' reports about ⁠whether conditions improved, worsened or were unchanged in areas such as new orders, output and employment compared with the previous month. A reading above 50 signals expansion, while one below 50 indicates contraction.

Some sectors within manufacturing were doing well.

Production and new orders sub-indexes for railway, shipbuilding, aerospace equipment, and computer, communications and electronics manufacturing were all at or above 53.0, the survey showed.

AI-related firms in particular have reported strong earnings growth. Zhongji Innolight, a maker of high-speed optical modules that connect servers and switches in AI data centers, posted a near tripling in third-quarter net profit.

But the lackluster domestic market and rising costs have weighed on many old-school manufacturers and property-linked firms. Custom furniture maker Oppein Home, for example, saw net profit plunge 80% during the quarter.

China's economy is, however, expected to meet the country's 4.5-5.0% annual growth target without additional stimulus measures after third-quarter growth rebounded to 4.5% from 4.3% in April-June.


15% Capital Requirement Complicates Restructuring of Lebanese Banks

A Lebanese delegation, led by Prime Minister Nawaf Salam, meets with IMF Managing Director Kristalina Georgieva in Washington in September. (X)
TT

15% Capital Requirement Complicates Restructuring of Lebanese Banks

A Lebanese delegation, led by Prime Minister Nawaf Salam, meets with IMF Managing Director Kristalina Georgieva in Washington in September. (X)

Talks that concluded in Paris on Thursday between Lebanon’s central bank, the Banking Control Commission and representatives of Lebanese banks revealed persistent differences over banking sector restructuring and the distribution of losses, as the International Monetary Fund (IMF) insists on a 15% capital adequacy ratio for banks seeking to remain operational, to be achieved within five to seven years.

According to information obtained by Asharq Al-Awsat, the meetings were hosted by Rothschild, the international adviser to Banque du Liban (BDL), in an effort to reconcile differing approaches to the provisions of the draft Financial Regularization and Deposit Recovery Law.

The discussions produced new proposals involving relatively minor changes in form but a more substantive approach to the draft law submitted by the government to Parliament late last year. The proposals are expected to influence subsequent stages of the legislative process.

However, efforts to bridge the differences were not matched by any shift in the IMF’s position. The Fund’s delegation reportedly maintained its firm stance on limiting the use of public funds and upholding the hierarchy of loss absorption, under which bank capital, shareholders and equity holders are first in line to bear losses.

Against this backdrop, the IMF has introduced an additional requirement, informing banking executives that operating banks must restructure their capital positions to achieve a 15% capital adequacy ratio as a key condition for remaining in business.

A source familiar with the matter told Asharq Al-Awsat that the Fund had stipulated a period of five to seven years from the start of restructuring to meet the requirement.

Although the proposed ratio is substantially higher than the requirements set under Basel III standards, the IMF argues that it is necessary for the banking sector, together with BDL as its regulator, to demonstrate a serious commitment to addressing the consequences of Lebanon’s unprecedented financial crisis.

The aim is to emerge from the crisis with a financial sector in the strongest possible position, paving the way for the restoration of international confidence.

Lebanese banks, however, face considerable difficulties persuading existing shareholders to inject such large amounts of private capital within a relatively short period.

Shareholders remain reluctant to commit fresh funds before negotiations produce a final agreement with the IMF, the government meets structural reform requirements in the public sector, a medium-term fiscal plan is adopted, and the outcome of Lebanon’s Eurobond restructuring becomes clear.

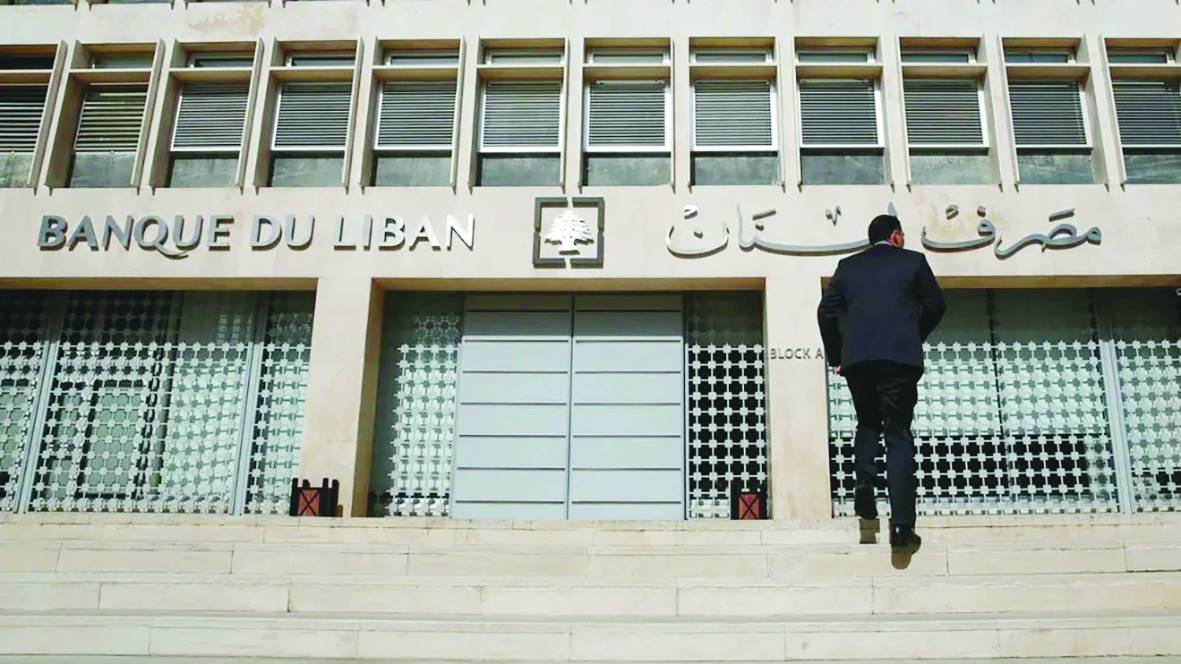
The Lebanese Central Bank building in Beirut. (AP)

What is required of banks?

An initial assessment by Asharq Al-Awsat indicates that meeting the IMF’s requirement would entail substantial cash injections and capital contributions or the attraction of new investors, a task that appears nearly impossible under current conditions.

Preliminary estimates suggest the funds required could amount to twice banks’ current capital, which has fallen sharply from levels exceeding $20 billion as a result of the Lebanese pound’s collapse.

The challenge comes as Lebanon and its economy face an exceptional contraction in investment inflows because of wars and the financial losses and heavy reconstruction costs they have left behind.

These burdens add to a financial gap that the government estimates at approximately $70 billion.

Insistence on this approach could undermine the banking sector’s prospects for recovery and its ability to contribute effectively to the broader economic rebound, given the difficulty most banks would face in injecting or attracting capital on such a scale.

Banking officials argue that the approach fails to account for the state’s role and responsibility in drawing financing from BDL’s balance sheet.

They also point out that a government decision to suspend repayment of all obligations on Lebanon’s Eurobonds deprived both commercial banks and the central bank of access to vital financial assets.

Meanwhile, a financial official noted that BDL’s handling of the consequences of the financial and monetary collapse, which have been concentrated heavily in the banking system, requires realism and a balance between two interconnected principles: ensuring a fair distribution of losses and avoiding the sacrifice of financial institutions.

This includes restructuring banks’ balance sheets and capital positions while enabling them to make the greatest possible contribution toward the gradual repayment of depositors’ claims, in accordance with the distribution mechanism established under existing central bank circulars.

Before the crises erupted, BDL imposed stringent solvency requirements on operating banks, with average ratios exceeding 15%.

Bank managements also voluntarily adhered strictly to international professional standards for assessing capital adequacy, enabling Lebanese banks to achieve leading regional positions in covering credit, market and operational risks.

Their risk management practices also included measuring and monitoring other exposures, such as interest rate risk in the banking book, credit concentration, liquidity and reputational risks.

Rothschild serves as BDL’s international adviser in negotiations concerning the financial sector, while Lazard performs the same role for Lebanon’s Finance Ministry.