OPEC+ Confirms Suspension of Oil Output Increase in First Quarter of 2026

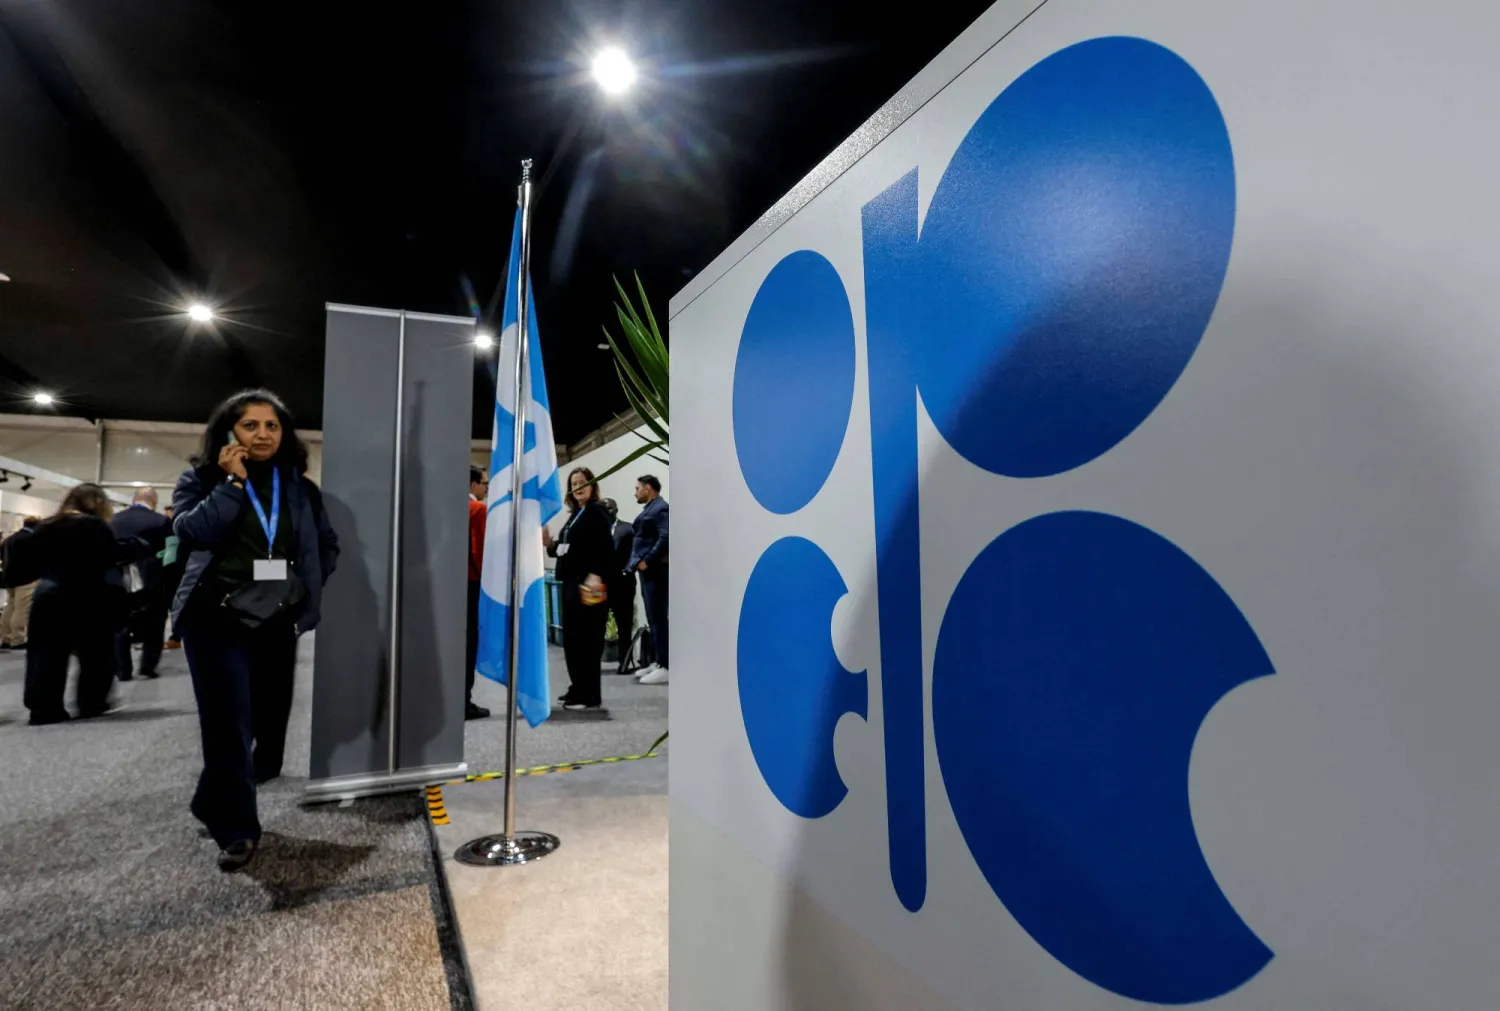
FILE PHOTO: A woman passes by a logo of Organization of the Petroleum Exporting Countries (OPEC) during the United Nations climate change conference COP29, in Baku, Azerbaijan November 13, 2024. REUTERS/Maxim Shemetov/File Photo
TT

OPEC+ Confirms Suspension of Oil Output Increase in First Quarter of 2026

FILE PHOTO: A woman passes by a logo of Organization of the Petroleum Exporting Countries (OPEC) during the United Nations climate change conference COP29, in Baku, Azerbaijan November 13, 2024. REUTERS/Maxim Shemetov/File Photo

OPEC+ countries have confirmed the suspension of the planned increase in oil production during the first quarter of 2026, as eight key producers reaffirmed their commitment to market stability amid a steady global economic outlook and what they described as healthy oil market fundamentals.

During a virtual meeting, Saudi Arabia, Russia, Iraq, the United Arab Emirates, Kuwait, Kazakhstan, Algeria, and Oman reaffirmed their decision issued on November 2, 2025, to pause the increases in January, February and March 2026, due to seasonal factors.

Their decision came a day after the arrest of Venezuelan President Nicolás Maduro, whose country holds the world’s largest oil reserves.

The alliance had agreed last November to an additional oil production increase of 137,000 barrels per day starting in December, but decided to freeze the increase planned for the first quarter due to seasonal factors.

Sunday's meeting of OPEC+ members, which pumps about half the world's oil, came after oil prices fell more than 18% in 2025 — their steepest yearly drop since 2020 — amid growing oversupply concerns.

In a statement issued following their meeting, the eight OPEC+ reaffirmed their commitment to market stability amid a steady global economic outlook and what they described as healthy oil market fundamentals.

The alliance stressed that 1.65 million barrels per day voluntary cuts may be restored in part or in full in a gradual manner, depending on future market trends.

“The countries will continue to closely monitor and assess market conditions, and in their continuous efforts to support market stability, they reaffirmed the importance of adopting a cautious approach and retaining full flexibility to continue pausing or reverse the additional voluntary production adjustments, including the previously implemented voluntary adjustments of the 2.2 million barrels per day announced in November 2023,” the statement said.

The eight countries will meet next on Feb. 1, the statement added.

The members raised oil output targets by around 2.9 million barrels per day in 2025, equal to almost 3% of world oil demand, to regain market share.

The eight members agreed in November to pause output hikes for January, February and March due to relatively low demand in the northern hemisphere winter.

OPEC has in the past managed to overcome many internal rifts, such as over the Iran-Iraq War, by prioritizing market management over political disputes.

Yet the group is facing other crises, with Russian oil exports falling due to US sanctions over its war in Ukraine, and Iran facing protests and US threats of intervention.

On Saturday, the United States captured Maduro, and US President Donald Trump said Washington would take control of the country until a transition to a new administration becomes possible, without saying how this would be achieved.

Venezuela has the world's largest oil reserves, but its oil production has plummeted due to years of mismanagement and sanctions.

Analysts said it is unlikely to see any meaningful boost to crude output for years, even if US oil majors do invest the billions of dollars in the country that Trump promised.


Saudi Arabia Issues 438 Industrial Licenses Worth $1.28 Billion in July

File photo of the Saudi capital Riyadh - File/AAWSAT
TT

Saudi Arabia Issues 438 Industrial Licenses Worth $1.28 Billion in July

File photo of the Saudi capital Riyadh - File/AAWSAT

Saudi Arabia's Ministry of Industry and Mineral Resources issued 438 new industrial licenses in July 2026, representing investments of approximately SAR 4.82 billion ($1.28 billion), while 189 factories began actual production during the same month, with investments totaling SAR 1.95 billion ($520 million), according to data from the ministry's National Industrial and Mining Information Center.

Ministry spokesperson Jarrah Al-Jarrah said the new industrial licenses are expected to create more than 3,708 jobs across various regions of the Kingdom.

He added that the factories that began production in July created 2,807 new jobs, reflecting the continued expansion of Saudi Arabia's industrial base and the growing number of factories entering operation.

The Ministry of Industry and Mineral Resources publishes monthly industrial activity indicators through the National Industrial and Mining Information Center to track new licenses, investment volumes and factories beginning production, as well as developments in the Kingdom's industrial sector.


GCC Chief Emphasizes Gulf Integration, Diversified Partnerships at IMF MENAP Meeting

Gulf Cooperation Council (GCC) Secretary-General Jasem Albudaiwi - SPA
TT

GCC Chief Emphasizes Gulf Integration, Diversified Partnerships at IMF MENAP Meeting

Gulf Cooperation Council (GCC) Secretary-General Jasem Albudaiwi - SPA

Gulf Cooperation Council (GCC) Secretary-General Jasem Albudaiwi underscored that GCC economies have demonstrated strong resilience against global economic shocks and geopolitical shifts, supported by solid fundamentals, substantial financial reserves, robust banking sectors, and prudent fiscal management.

Albudaiwi delivered his remarks during a meeting of the finance ministers and central bank governors of the Middle East, North Africa, Afghanistan, and Pakistan (MENAP) region with International Monetary Fund (IMF) Managing Director Kristalina Georgieva, held on the sidelines of the 2026 IMF and World Bank Group Annual Meetings in Bangkok, SPA reported.

Albudaiwi pointed out that recent geopolitical developments have impacted global energy production, maritime shipping, and trade flows, demonstrating the close link between Gulf stability and broader global economic security. He noted that disruptions along key energy corridors and trade routes inevitably reverberate across international markets.

Albudaiwi affirmed that the GCC economies possess the capacity to sustain recovery and growth through 2027 and beyond, propelled by strategic investments and non-oil diversification. He emphasized the necessity of balancing short-term economic responses with long-term fiscal sustainability, maintaining adequate buffers to mitigate future market volatility.

Highlighting future growth sectors, the secretary-general cited advanced industries, digital infrastructure, artificial intelligence, and human capital development, alongside empowering the private sector to expand its role in global value chains.

Concluding his address, Albudaiwi stressed that long-term resilience requires advancing Gulf economic integration, upgrading logistical corridors, and diversifying international partnerships to transform ongoing global challenges into sustainable economic opportunities.


Turkish Cenbank Says to Maintain Tight Monetary Stance Till Price Stability

Turkish Central Bank Governor Fatih Karahan speaks during a press conference in Istanbul, Türkiye, February 7, 2025. REUTERS/Dilara Senkaya
TT

Turkish Cenbank Says to Maintain Tight Monetary Stance Till Price Stability

Turkish Central Bank Governor Fatih Karahan speaks during a press conference in Istanbul, Türkiye, February 7, 2025. REUTERS/Dilara Senkaya

Turkish Central Bank Governor Fatih Karahan on Wednesday said the bank would maintain its tight monetary policy until price stability is achieved.

According to Reuters, He was speaking about Türkiye's monetary policy and macroeconomic outlook during a visit to Bangkok for a meeting of the World Bank.

Here are some details from the governor's presentation:

* Underlying inflation ⁠is moderating despite ⁠elevated energy prices
* Soft demand dampens inflationary impulses from supply shocks
* Proactive measures limit the possible contagion from trade-restricted funds
* Turkish lira preference remains strong under tight monetary policy
* The ⁠tight monetary policy stance, which will be maintained until price stability is achieved, will strengthen the disinflation process through demand, exchange rate, and expectation channels
* The Monetary Policy Committee (MPC) will determine the policy rate by taking into account realized and expected inflation and its underlying trend in a way to ensure ⁠the tightness ⁠required by the projected disinflation path in line with the interim targets
* Monetary policy decisions are made prudently on a meeting-by-meeting basis with a focus on the inflation outlook
* Monetary policy stance will be tightened in case of a significant deviation in inflation outlook from the interim targets