300,000 New Homes to Restore Market 'Balance' in Riyadh

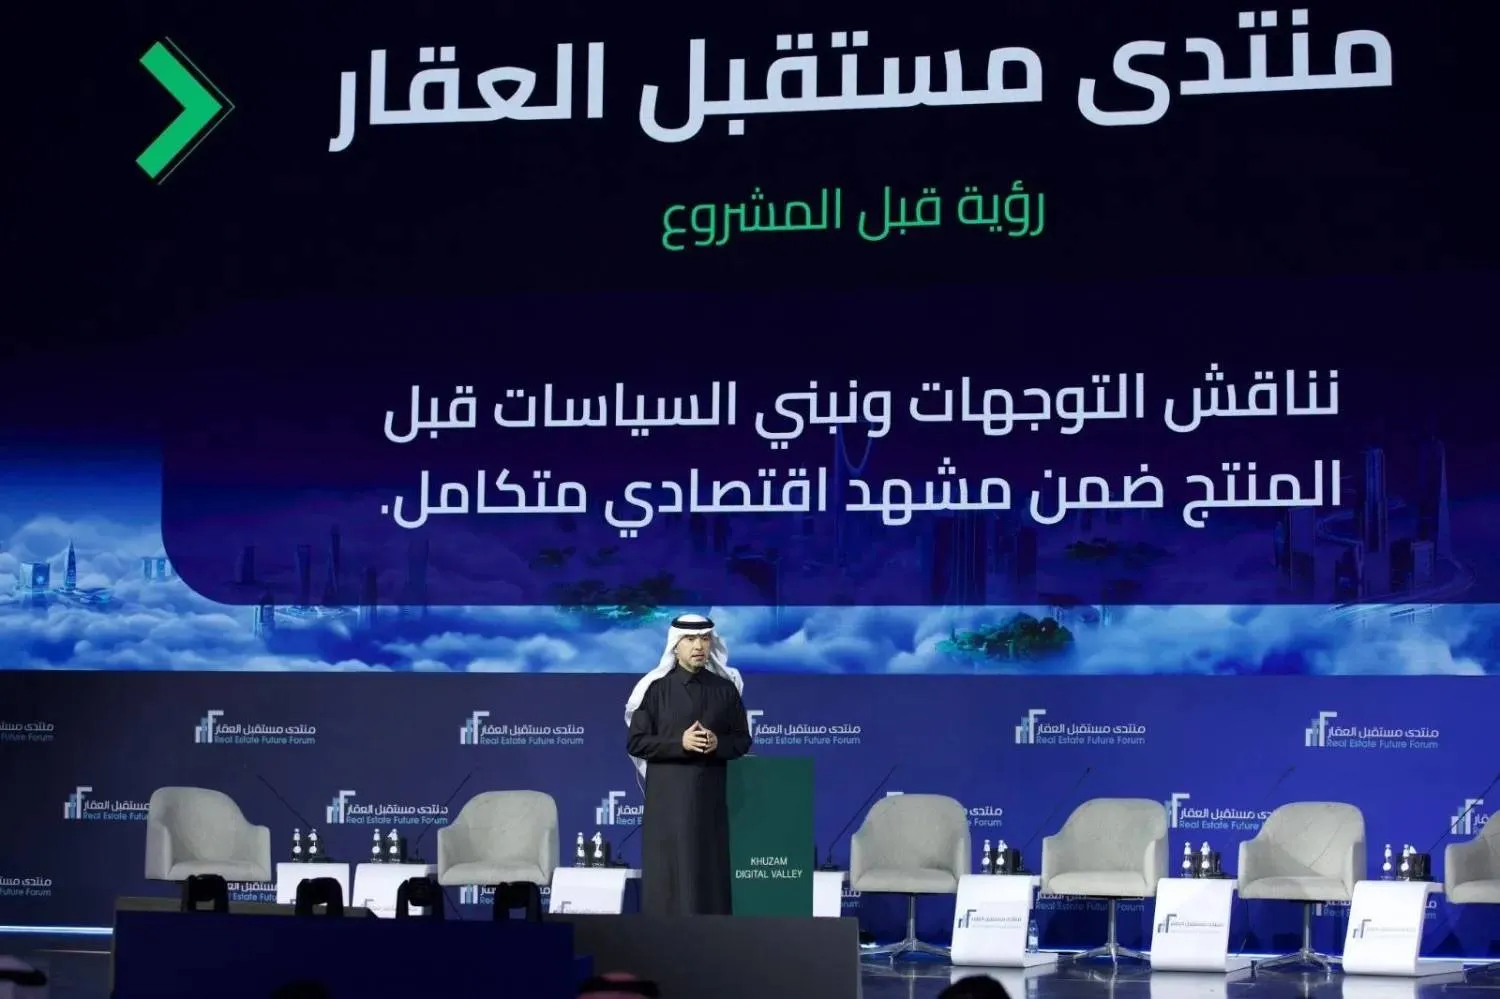
Saudi Minister of Municipalities and Housing Majed Al-Hogail speaks at Monday's forum in Riyadh. (Asharq Al-Awsat)
TT

300,000 New Homes to Restore Market 'Balance' in Riyadh

Saudi Minister of Municipalities and Housing Majed Al-Hogail speaks at Monday's forum in Riyadh. (Asharq Al-Awsat)

Saudi Arabia plans to inject more than 300,000 new housing units into Riyadh over the next three years as part of a broader government strategy to stabilize the capital’s real estate market, announced Majed Al-Hogail, Minister of Municipalities and Housing and Chairman of the Board of the General Real Estate Authority.

Speaking at the opening of the fifth edition of the Real Estate Future Forum 2026 in Riyadh on Monday, Al-Hogail said the capital already has more than 100 million square meters of developed, ready-to-build land.

The forum brought together decision-makers, experts and investors from more than 140 countries, with around 300 speakers from government, business and the public and private sectors, highlighting the growing global prominence of Saudi Arabia’s real estate industry.

Al-Hogail stressed that the Kingdom has adopted “real estate balance” as a strategic policy aimed at improving efficiency and fairness in the sector through precise regulatory tools and informed analysis of market dynamics.

He highlighted a historic surge in mortgage financing, which rose from SAR 82 billion in 2017 to nearly SAR 900 billion (about $240 billion) by 2025, making real estate finance a major pillar of the national economy, accounting for around 27 per cent of Saudi banks’ total loan portfolios.

Homeownership

On homeownership, Al-Hogail said the rate of Saudi citizens owning homes exceeded 66 percent in 2025, with more than one million beneficiaries of government housing support programs. He outlined ambitious targets to support an additional 367,000 beneficiaries and raise the homeownership rate to 70 percent by 2030.

Riyadh has over 100 million square meters of developed land ready for use and is expected to receive more than 300,000 new housing units within three years, he went on to say.

He also highlighted the role of the National Housing Company, the region’s largest real estate developer, which has delivered around 300,000 housing units across 16 cities and plans to add another 300,000 units in the next phase.

This growth, he said, reflects the maturity of the market and rising confidence among investors and citizens alike.

Real estate investment

Saudi Minister of Investment Khalid Al-Falih described real estate as a safe haven for economic stability amid global geo-economic uncertainty and volatile markets.

The real estate and construction sector forms a “solid foundation” for national growth, contributing about 13 percent of Saudi Arabia’s GDP, he stressed. This momentum is supported by large-scale investments led by the Public Investment Fund (PIF), which have exceeded $400 billion since the launch of Vision 2030.

Tourism projects and urban transformation

Saudi Minister of Tourism Ahmed Al Khateeb said the Kingdom is now “leading global change” in urban development and the creation of major tourism destinations.

Saudi Vision 2030 has transformed the concept of city design, shifting from merely serving local residents to also welcoming visitors and meeting their needs, he remarked.

He cited mega-projects such as NEOM, the Red Sea project and Diriyah as examples of this transformation, arguing that the Kingdom’s ability to develop previously untouched regions, such as Tabuk and the Red Sea islands, gives it a unique advantage in delivering architectural and technological models that inspire the world.

Quality of life

Al Khateeb also noted the launch of the Global Quality of Life Index, developed in partnership with UN-Habitat. The index is the first of its kind to measure quality of living based on comprehensive criteria, including infrastructure and essential services.

Rather than assessing happiness or education in isolation, it evaluates the overall ecosystem of services that matter to residents and visitors, focusing on accessibility, affordability and quality.

Al Khateeb stressed the importance of sustainability in the economy, employment and the environment, describing it as the most critical component of quality of life and a core responsibility embedded in national visions.

Tourism has been a key driver in reducing unemployment in Saudi Arabia to record lows comparable to OECD and G20 countries, with the sector creating 250,000 new jobs for Saudis since the launch of the national tourism strategy in 2019, he added.

Partnerships and agreements

Abdullah Al-Hammad, Chief Executive Officer of the General Real Estate Authority, said the sector has become an influential player in the global economy.

He noted that the forum coincides with the implementation of regulations allowing non-Saudis to own real estate, opening unprecedented global opportunities for the Saudi market and showcasing the Kingdom’s geographical diversity and cultural depth.

Al-Hammad added that previous editions of the forum resulted in agreements and partnerships worth more than $50 billion (SAR 187.5 billion), describing the figure as clear evidence that discussions at the forum are transforming into concrete decisions, investments and projects on the ground.


Gold Rallies as Dollar, Treasury Yields Soften after US Midterm Results

Gold chips displayed at a state-owned gold retail store in Surabaya, East Java (AFP)
TT

Gold Rallies as Dollar, Treasury Yields Soften after US Midterm Results

Gold chips displayed at a state-owned gold retail store in Surabaya, East Java (AFP)

Gold climbed to its highest level in over two weeks on Thursday as the fallout from the US midterm election results rippled through the global financial and oil markets.

Spot gold rose 1.6% to $4,124.89 per ounce by 0752 GMT. It touched $4,146.63 per ounce, its highest level since October 20, earlier in ‌the session.

Bullion ‌climbed about 3.4% on Wednesday, its biggest ‌daily gain ⁠since August 19.

US ⁠gold futures for December delivery climbed 1.5% to $4,135.40, Reuters said.

A weaker dollar and lower Treasury yields have helped gold recover above the key $4,000 level, though holding above that threshold remains crucial for the recovery outlook, said Linh Tran, market analyst at XS.com.

"If investment flows and yield movements continue to provide support, gold could stabilize ⁠above $4,000, also opening up an opportunity for a ‌recovery toward $4,200, followed by $4,400."

Oil prices ‌were slightly higher after earlier falling for a fourth day on ‌expectations that the losses US President Donald Trump's Republican Party ‌suffered in congressional elections this week may reduce the risk of further escalation of the US-Israeli war with Iran.

Lower energy prices ease inflationary pressures, reducing expectations that the central bank will keep interest rates higher ‌for longer, supporting the appeal of non-yielding bullion.

The dollar slid to its lowest in more ⁠than a ⁠month, and 10-year US Treasury yield fell to its lowest since September 10.

A weaker dollar makes greenback-priced bullion more affordable for holders of other currencies.

Market participants now await the US non-farm payrolls report on Friday to further gauge the Federal Reserve's monetary policy outlook.

Meanwhile, Citi has a 0-3 month price target of $4,500 per ounce for gold, the brokerage said on Wednesday, as it sees substantial upside potential if the Strait of Hormuz reopens and the Yemen/Saudi conflict de-escalates.

Among other metals, spot silver rose 0.8% to $52.63 per ounce, platinum gained 1.2% to $1,514.20 and palladium climbed 2.2% to $1,026.83.


Tech Hit by New AI Worries on Positive Day for Most Markets

Hong Kong stocks rallied more than three percent on a broadly healthy day for Asian markets. Leung Man Hei / AFP
TT

Tech Hit by New AI Worries on Positive Day for Most Markets

Hong Kong stocks rallied more than three percent on a broadly healthy day for Asian markets. Leung Man Hei / AFP

Tech firms tumbled Thursday as investors contemplated the outlook for the AI boom after Democrats swept the US midterms, partly on the back of growing anger over the rapid building of data centers across the country.

However, broader markets mostly rallied and oil plunged after Donald Trump's Republicans were dealt a historic defeat that was blamed on high prices, tariffs and the Iran war.

The result stoked hopes he will look to wind down the Middle East conflict, which would help temper inflation and even soften his stance on trade.

But AI-linked firms came under the cosh amid fears for planned data center construction projects as well as renewed scrutiny from newly installed Democrats on Capitol Hill.

The sector had already been in the crosshairs of investors owing to questions about the vast sums pumped into new facilities, R&D and chip development, and when any companies would see a profit.

Charu Chanana at Saxo Markets said the vote was accelerating a reassessment of AI that was already under way.

"A Democratic Congress introduces another layer of uncertainty: regulatory scrutiny," she wrote, adding that the three main risks were more oversight, data center restrictions and capital spending uncertainty.

"The congressional scrutiny could accelerate demands for AI safety standards, independent model evaluations and greater accountability for data center developers," she added.

However, she also said: "This is not the same as an outright anti-AI policy agenda. AI is strategically important for US competitiveness, particularly against China, and there remains considerable bipartisan interest in maintaining American leadership."

Chip firms were hammered in Asia, with South Korea's SK hynix off more than seven percent and Samsung 5.5 percent down.

Tokyo-listed Kioxia dived more than 13 percent and Advantest tanked 14.7 percent, while Tokyo Electron lost more than nine percent and SoftBank 6.8 percent.

US Nasdaq futures fell more than one percent.

Broader markets performed better as investors rotated into other sectors including finance, auto, mining and manufacturing names.

Seoul, the poster child of the AI-led surge in the first half of the year, shed more than five percent, while Taipei lost more than three percent. Tokyo gave up 1.8 percent.

But there were healthy gains in Hong Kong, helped by hopes for an easing of trade tensions between the US and China, with tech titans including Alibaba, JD.com and Tencent leading the way amid a shift into beaten-down regional stocks.

Shanghai, Sydney, Singapore, Wellington, Mumbai, Jakarta and Manila also advanced.

Oil continued to fall after diving more than eight percent Wednesday on the US result amid optimism Trump will seek a deal to end the Iran war, which has been a key driver of the inflation spike that has hammered US consumers.

Hopes were given a boost when Vice President JD Vance said in a social media post that the Republican defeat was due to the unpopularity of the eight-month-old conflict.

The drop in crude prices -- both main contracts are now below $100 for the first time since the start of October -- has also tempered inflation worries and, in turn, Treasury yields, which dipped again Thursday.

The lower cost of borrowing has also been helped by the prospect that gridlock on Capitol Hill would lead to less spending.

That also weighed on the dollar, which held losses against its peers in Asian trade.


Türkiye Showcases Renewables Surge, but Leaves Coal Intact

Türkiye is rapidly expanding its renewable energy capacity. But as host of COP31, the country faces growing pressure to match its clean energy ambitions with a clear commitment to phase out fossil fuels. Yasin AKGUL / AFP
TT

Türkiye Showcases Renewables Surge, but Leaves Coal Intact

Türkiye is rapidly expanding its renewable energy capacity. But as host of COP31, the country faces growing pressure to match its clean energy ambitions with a clear commitment to phase out fossil fuels. Yasin AKGUL / AFP

On a windy hillside about an hour's drive northwest of Istanbul, the Catalca power plant was one of Türkiye's first large-scale wind farms and has been feeding electricity into the grid for 18 years.

With an installed capacity of 93 megawatts, it generates 287 million kilowatt-hours of electricity a year, enough for around 115,000 households, said AFP.

"By replacing electricity that would otherwise come from fossil fuel-fired power plants, this output avoids 185,936 tons of carbon emissions each year," operator Sanko Enerji says.

Nearly two decades on, Catalca is one of nearly 300 wind farms, its giant turbines a symbol of the rapidly expanding capacity for renewable energy in Türkiye which is hosting the COP31 UN climate summit that opens in Antalya on Monday.

Last year, 43 percent of Türkiye's electricity came from clean energy sources, of which wind and solar accounted for 22 percent, according to energy think tank Ember.

With electrification emerging as one of the central themes of COP31, Türkiye has been pushing hard for it to be an implementation-focused summit that turns existing climate pledges into action.

Energy Minister Alparslan Bayraktar has outlined plans to triple Türkiye's installed solar and wind capacity from around 40 gigawatts to 120 gigawatts by 2035.

But with coal still the leading source of power generation, Türkiye is under pressure to pair its impressive renewables growth with a definitive shift away from fossil fuels.

Not only is it still building coal-fired power plants, it has yet to set a date to phase out fossil fuels.

- Coal still dominant -

"Türkiye's continued reliance on coal, alongside plans for further expansion, highlights the contradiction at the heart of its current trajectory," Duygu Kutluay of Beyond Fossil Fuels told AFP.

Embracing an electrification agenda alone did not amount to a genuine energy transition because "coal remains the country's largest source of electricity generation", she said.

Coal-fired power plants accounted for 33.5 percent of Türkiye's electricity production in 2025, energy ministry figures show, with Ember saying almost two-thirds of its coal was imported.

Plans to expand coal capacity "risk locking in further fossil-fuel dependence", she warned.

"As Türkiye increases renewable capacity, it must ensure clean electricity replaces fossil-fuel generation rather than simply meeting additional demand," Kutluay said.

The challenge is not only expanding renewables but establishing "a clear pathway to phase out coal".

Asked about Türkiye's continuing reliance on coal, Bayraktar told AFP in February that Ankara prioritized securing affordable energy supplies and reducing dependence on imports.

"Coal can initially be replaced with gas, but in the medium and long term it can be substituted with nuclear," he said.

Ibrahim Erden, president of the Turkish Wind Energy Association, said every country's transition was different with "no single path that suits everyone".

- Need for investment -

Emin Emrah Danis, chief executive of MOBEN consultancy, said Türkiye's energy policy was shaped by rising electricity demand and the need for "baseload" generation to deliver constant power around the clock.

"This is why Türkiye has invested heavily in gas- and coal-fired power plants over the past 30 years," he told AFP.

"For coal's share of power generation to fall to meaningful levels, Türkiye needs substantial investment in electricity storage and nuclear power," he said, referring to battery storage for renewable power.

Türkiye is currently putting the finishing touches on the first reactor of its Akkuyu nuclear power plant, which should be online by the start of 2027, Bayraktar told an energy summit last week.

But Türkiye's nuclear expansion, with two more plants in the pipeline, was unlikely to add enough baseload capacity to replace coal-fired electricity generation before around 2040, Danis said.

And coal would likely remain part of the energy mix for decades, with the need for baseload power and dependence on imports making a full phase-out infeasible before "the mid-2050s".

Türkiye relies heavily on imports of oil, natural gas and coal from countries like Russia, Iran and Azerbaijan.

Erden said infrastructure updates were essential to give greater place to renewables.

"We cannot simply shut down coal-fired power plants today and rely solely on wind and solar energy ... The technological and physical infrastructure is not yet capable of supporting that."

Beyond the climate argument, geopolitical tensions have also strengthened the case for domestic renewables.

"Renewables ... are not only one of the most effective tools for tackling climate change, but also an important means of strengthening energy security and reducing dependence on foreign supplies," he said.