Globe-Trotting Lebanese Lenders Face Toughest Test at Home

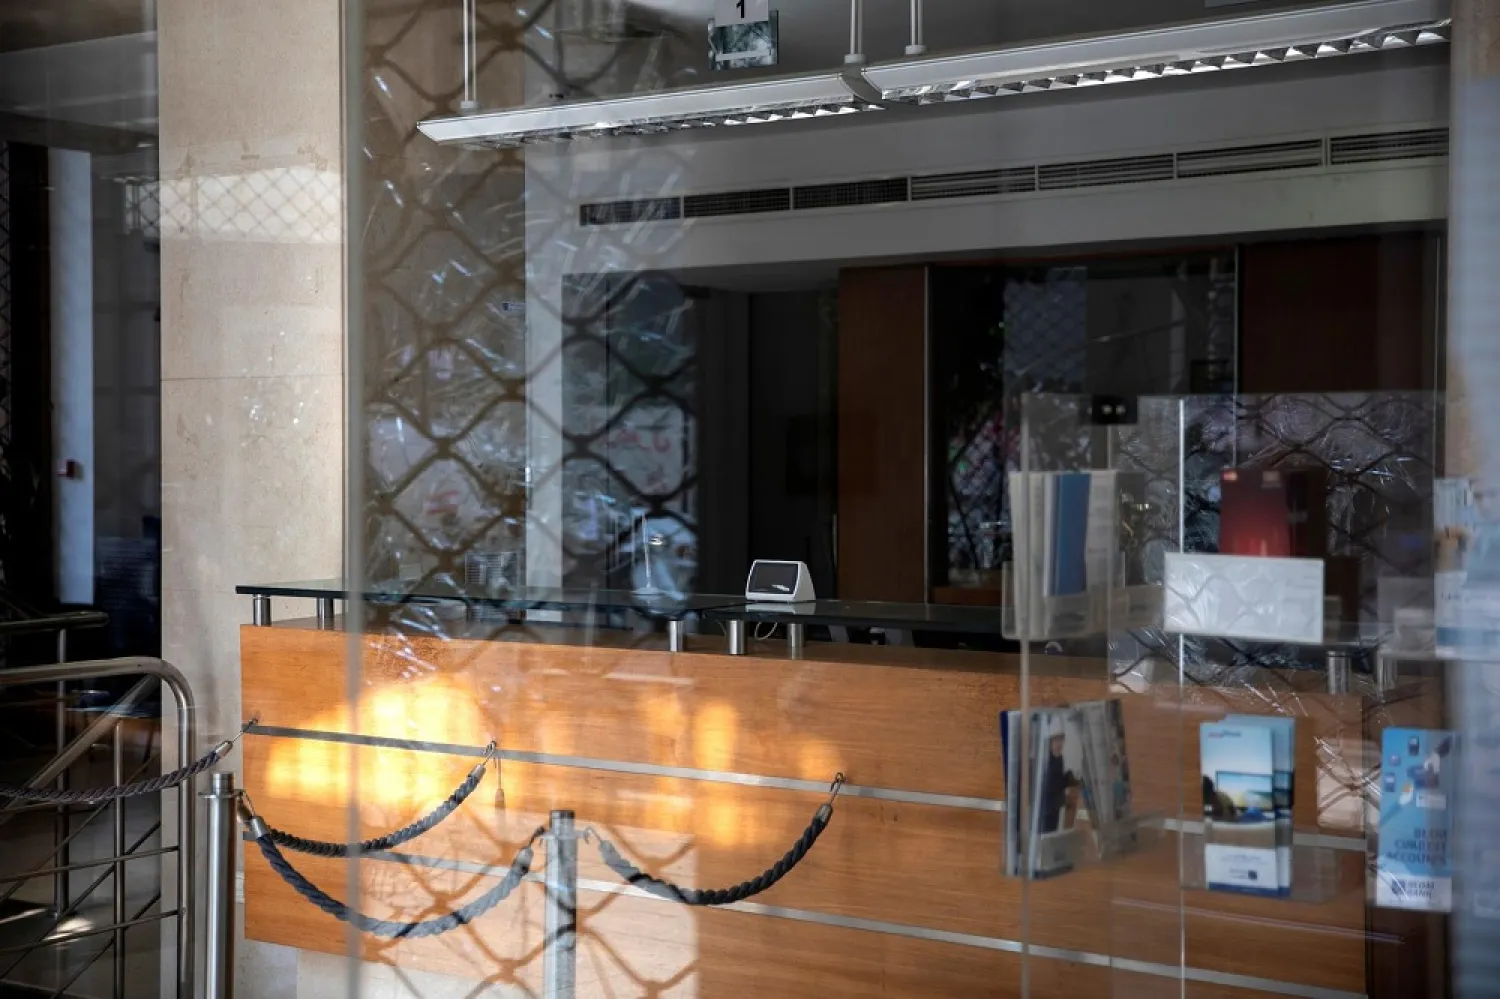
View of a closed Blom Bank branch in downtown Beirut, Lebanon, October 25, 2019. (Reuters)
TT

Globe-Trotting Lebanese Lenders Face Toughest Test at Home

View of a closed Blom Bank branch in downtown Beirut, Lebanon, October 25, 2019. (Reuters)

Lebanon’s economic crisis is a litmus test for the resilience and domestic support of its banks as well as their potential for sparking contagion abroad.

Lebanese lenders remained closed for a seventh working day on Friday, with the small, heavily indebted Mediterranean country paralyzed as hundreds of thousands of people protest over economic strife, leaving schools and businesses shut.

The government has responded by promising reforms which involve banks stumping up 5.1 trillion Lebanese pounds ($3.4 billion) toward deficit reduction in next year’s budget, partly through a rise in tax on their profits.

“These measures should weaken the banking sector as they will cut into their profit margins over the next year,” said Natasha Smirnova, portfolio manager at PineBridge Investments, pointing out the levy was just a one off for next year.

Financial services make up 8% of gross domestic product in the country of 6 million. Bank deposits to GDP stand at 243%, the third highest ratio globally after Luxembourg and Hong Kong.

“Banks have an enormous role in government funding, as they are almost their only source of financing, and the cabinet/ central bank will proceed with utmost caution so they do not hurt the sector too much,” Smirnova added, according to Reuters.

Lebanon’s unorthodox “financial engineering” relies on them drawing in FX deposits from abroad by offering high interest rates to help shore up the country’s pressurized FX reserves.

Lebanon has 66 registered lenders, with commercial banks holding just over $260 billion of assets, central bank data showed, though a handful of large players dominate.

But while banks in Lebanon have an unusually wide geographic spread due to its estimated diaspora of around 14 million, their closure so far appears to pose relatively little threat to wider financial stability.

The Lebanese have a long history of emigration and settling around the world, with large, mostly Christian, expatriate populations in Brazil and the United States in addition to Shiite communities in Africa.

“Lebanese banks have significant operations in the region, but this is mainly through a subsidiary model, where those operations are ring-fenced,” said Farouk Soussa, senior economist with Goldman Sachs. “This minimizes the risk of financial contagion either way.”

Bank Audi - Lebanon’s biggest bank by assets - operates in 11 countries including Saudi Arabia, Egypt, France and Switzerland. Its annual report showed that of its total assets of $47.2 billion, nearly 70% came from Lebanon at the end of 2018 compared to just over 60% the previous year.

Its Turkish arm Bank Odea, in which Bank Audi holds a 75% stake, accounted for nearly 13% of assets while Egypt accounted for 8.2%. However, the share of both countries in total assets had declined due to currency depreciation.

“Bank Audi’s branches and subsidiaries abroad are stand-alone entities and are therefore not affected by the crisis Lebanon is currently witnessing,” it said on Friday in response to questions from Reuters.

Blom Bank operates in around 10 countries including Britain and Romania. But of the bank’s $36.7 billion of assets at the end of 2018, nearly 83% came from Lebanon, with another 9% from MENA, including Egypt, Jordan and Iraq.

Asked what effect the crisis in Lebanon was having on its branches and subsidiaries abroad, Blom Bank said it had “witnessed an increase in its foreign operations”, without giving any further details.

Bank of Beirut in 2011 bought Australia’s Bank of Sydney, which offers mortgages, home loans and savings accounts and states on its website that deposits were covered by the Australian Government Deposit Guarantee.

Salim Sfeir, chairman of Bank of Beirut and the Association of Banks in Lebanon said he expected banking operations will fully resume once banks re-opened. Bank Audi said it was servicing and replenishing ATMs, collecting cheques deposited at smart ATMs and “processing emergency requests”.

Whenever, wherever

Many of Lebanon’s lenders focus on banking expatriates rather than being systematically entangled in the financial ecosystems of other nations.

The other factor limiting the potential repercussions of the stresses in the Lebanese banking system is that many western banks have limited exposure to the country, which was shattered by civil war between 1975 and 1990.

It now faces sluggish growth and high unemployment.

“It might make you think of Ireland where banking sector stress will completely bring down the whole economy,” said Nafez Zouk at Oxford Economics.

“But Lebanon’s banking sector is pretty plain vanilla - it is not risky, there is lot of macro-prudential regulation...it’s very, very pure and simple banking.”

Of the major western banks, Citigroup remains one of the few with a presence, with 35 staff offering corporate and investment banking as well as trade finance, the US bank’s website shows.

JPMorgan has just a handful of people based in Lebanon, who work in Treasury Services, which is part of wholesale payments.


Saudi Gold Refinery Obtains 10 Gold Exploration Licenses in Tanzania

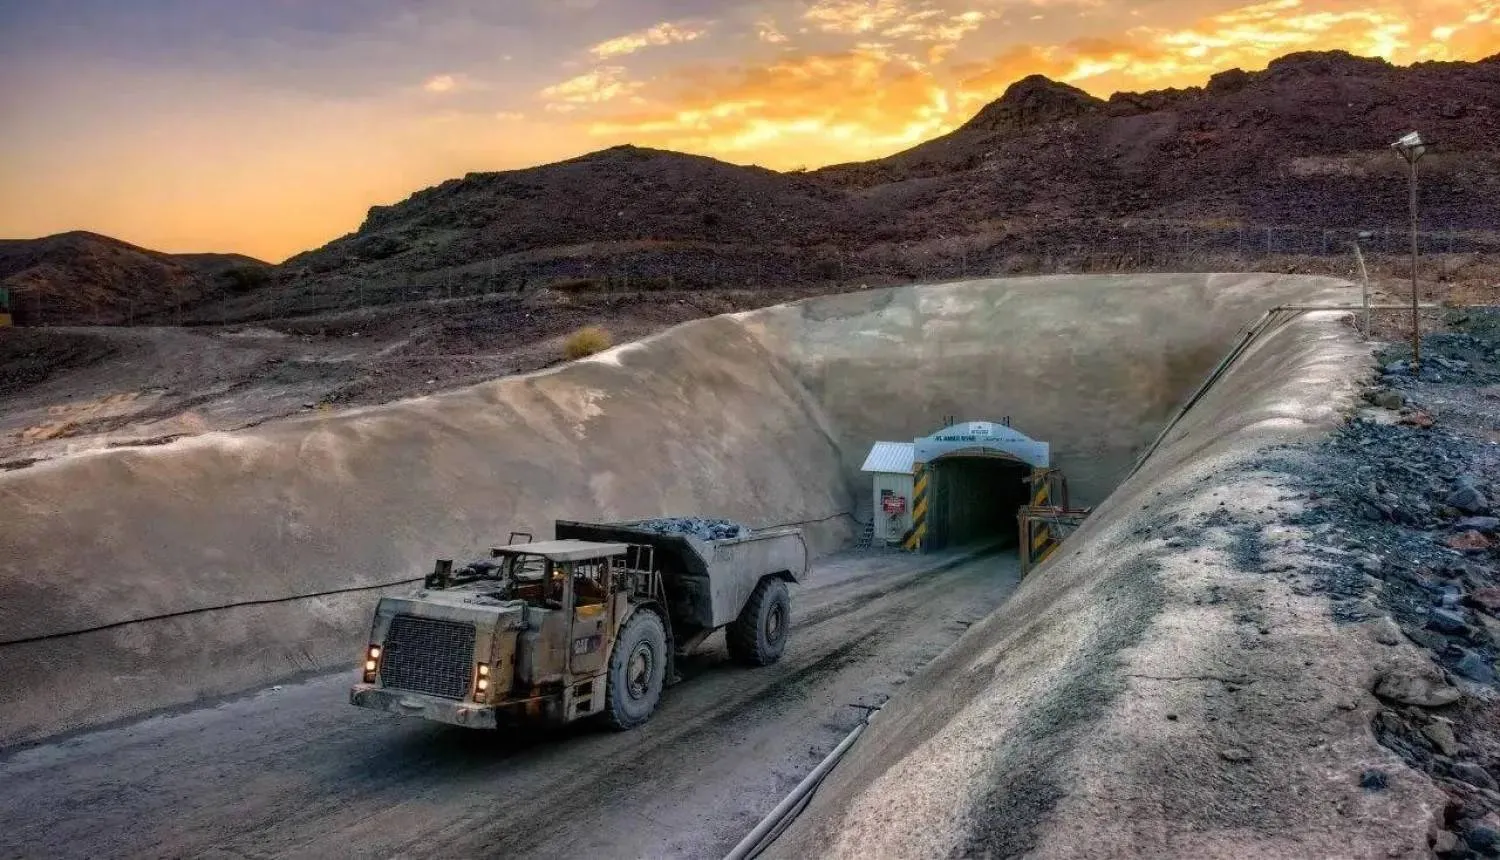
A gold mine in Saudi Arabia (SPA) 
TT

Saudi Gold Refinery Obtains 10 Gold Exploration Licenses in Tanzania

A gold mine in Saudi Arabia (SPA) 

Saudi Gold Refinery Company (SGR) announced Sunday it has secured 10 licenses to explore gold in the Republic of Tanzania, covering a total area of nearly 1,000 square kilometers, in a move aimed at expanding the company’s mining operations outside the Kingdom.

The company said it has allocated an initial investment of $10 million to carry out exploration activities, within an ambitious plan to gradually increase total investments to $100 million. These investments will support the development, establishment, and operation of gold mines, with commercial production targeted to commence by 2030.

The announcement follows a visit to Tanzania by Faisal Suliman Al-Othaim, Deputy Chairman of the Board of Directors at SGR.

According to the company, this milestone is supported by the Ministry of Investment and the Saudi Embassy in Tanzania, highlighting the importance of strengthening Saudi investments abroad and creating new opportunities for national companies in the global mining industry.

SGR continues to advance its global expansion strategy through its international investment arm, UGM Tanzania co, which oversees its operations and investment activities in Tanzania and Ethiopia.

The company also maintains ongoing projects and business activities in Egypt and the Sultanate of Oman, while actively exploring opportunities in additional markets to further expand its global footprint and create sustainable value across the mining sector.

In the Saudi market, the company plans to develop six to ten mines before 2030, at an average rate of two mines per year. These plans are supported by the Ministry of Industry and Mineral Resources, the Saudi Industrial Development Fund, financial institutions and other relevant authorities and stakeholders.


Oil Falls as Trump Says New Iran Attacks ‘Unlikely’

A worker walks past oil pipes at a refinery in Wuhan, Hubei province March 23, 2012. (Reuters)
TT

Oil Falls as Trump Says New Iran Attacks ‘Unlikely’

A worker walks past oil pipes at a refinery in Wuhan, Hubei province March 23, 2012. (Reuters)

Oil prices fell at Monday's open after US President Donald Trump said he was highly unlikely to order new Iran attacks while talks to end the conflict make progress, despite both nations' reports of attacks on ships in or near the Strait of Hormuz.

Brent was down 84 cents, or 0.85%, to $97.48 a barrel by 0138 GMT, while West Texas Intermediate fell 32 cents, or 0.35%, to $90.51 a barrel.

The fall reversed minor gains made on Friday’s settlement as the market assessed the possibility of further US ‌strikes on Iran, ‌although Brent fell 17% last week, the ‌steepest ⁠weekly drop since the ⁠start of the COVID pandemic and the biggest in absolute terms, according to LSEG data dating back to 1988.

"It depends on whether or not they sign a very strong agreement," Trump told CNN in a phone interview. "The answer is, highly unlikely it's going to be necessary."

Trump had hinted at renewing attacks on Iran after ⁠last week's US midterm elections, but there has ‌been no sign of a large-scale ‌US military operation. Iran has said it would respond by striking US and ‌Israeli targets.

Tim Waterer, chief analyst at KCM Trade, called ‌Trump's comments "more measured" but said "the market is still waiting to see whether the midterms have produced a lasting shift in Trump’s approach to the conflict, or whether this is just another temporary change in tone."

Oil is headed ‌for a glut again as recovering Middle Eastern oil flows, rising production from other countries and ⁠weak demand have ⁠pushed global supply above consumption, JPMorgan said in a report on Friday, estimating a surplus of 1.1 million barrels per day in September, widening to 1.4 million bpd in October.

On Sunday, Iraq reached an understanding with the US to allow Iraqi oil exports through the Strait of Hormuz via a shipping lane near Oman, Foreign Minister Fuad Hussein said in an interview with Al Jazeera.

He said Iraq's losses from the Iran war and disruptions to oil exports had reached $60 billion.


Bahraini Transport Minister to Asharq Al-Awsat: Each Country to Finance Its Share of Gulf Railway Project

A conceptual rendering of the Gulf railway interconnection project. (X)
TT

Bahraini Transport Minister to Asharq Al-Awsat: Each Country to Finance Its Share of Gulf Railway Project

A conceptual rendering of the Gulf railway interconnection project. (X)

The Gulf Cooperation Council (GCC) member states took a new step toward completing the railway interconnection project by signing the project's general agreement in Bahrain on Sunday. This comes as part of efforts to establish an integrated transport network linking the six nations and boosting the movement of passengers, goods, and commercial trade among them.

Bahraini Minister of Transportation and Telecommunications Dr. Sheikh Abdulla bin Ahmed Al Khalifa told Asharq Al-Awsat that each country will fund and execute the portion of the project located within its territory.

Meanwhile, the costs, fees, and expenses associated with the shared interconnection components among member states will be determined collectively, he added.

He explained that the agreement establishes a joint framework for the project's execution and operation, while defining the obligations of member states and their coordination mechanisms.

He noted that the network, which extends some 2,117 kilometers, aims to transport 6 million passengers and 200 million tons of freight by 2030, with the figures projected to rise to more than 8 million passengers and 271 million tons of freight by 2045.

The project spans from Kuwait, passing through Saudi Arabia, Bahrain, Qatar, and the UAE, all the way to Oman, with the goal of achieving full network operations by December 2030.

According to the minister, interconnection lines between adjacent countries can become operational as soon as their components are completed, without the need to wait for the entire Gulf network to be finalized.

National financing and potential partnerships

On private sector participation, Al Khalifa said that it remains one of the viable options for financing, executing, or operating certain components of the project, depending on the outcomes of economic and financial studies. He stressed that there is no unified public-private partnership model approved across the entire network.

There are currently no pre-existing agreements with specific international partners to finance or execute the project, he said. However, the expertise of global companies in the fields of design, engineering, technology, and operating systems could be utilized based on the project's needs and its various phases.

Bahraini Minister of Transportation and Telecommunications Dr. Sheikh Abdulla bin Ahmed Al Khalifa.

Concerning the project's announced completion rate, the minister explained that the 50 percent figure represents the average progress achieved across member states, and does not mean that half of the construction work for the entire Gulf network has been completed.

The project's cost estimates are currently undergoing review and updates in light of economic shifts, rising prices for materials and services, construction costs, and inflation, he revealed without specifying an updated total cost at the present time.

Returns beyond passenger and freight transport

Al Khalifa said that the economic impact of the project is not limited to facilitating passenger movement and freight transport, but extends to improving supply chain efficiency, boosting trade among GCC countries, and linking industrial centers, economic zones, and logistical hubs, as well as supporting employment and investment opportunities.

He added that determining the project's exact contribution to the gross domestic product (GDP) or estimating expected savings in time and costs remains premature, given that returns vary depending on transport routes, the nature of the cargo, and the points of origin and destination.

In light of the challenges facing maritime navigation in the region, the minister stressed that the Gulf railway network is not intended to serve as a substitute for maritime transport. Instead, it acts as a complementary route that boosts transport options and connectivity among GCC nations, increasing the resilience of supply chains against disruptions that could affect various modes of transportation.

He noted that integration between ports, roads, railways, and airports will strengthen the flexibility of the Gulf transport system, while connecting to broader international logistical corridors remains a future possibility contingent on completing studies, understandings, and coordination with the relevant countries and entities.

King Hamad Bridge to link Bahrain and Saudi Arabia

Regarding the connection between Bahrain and Saudi Arabia, Al Khalifa explained that the King Hamad Bridge project includes road lanes and railway lines, enabling the international passenger station in Bahrain to connect with the Saudi railway network and forming one of the essential components for completing the Gulf interconnection.

He added that work is underway on the privatization procedures for the King Fahd Causeway Authority, alongside completing the necessary studies and procedures to transition to the execution of the new bridge project.

Achieving the connection between Bahrain and Saudi Arabia is a fundamental requirement for operating the railway line between the two countries within the project's targeted timeframe in December 2030,e he said.