Iran Tells World to Get Ready for $200 a Barrel

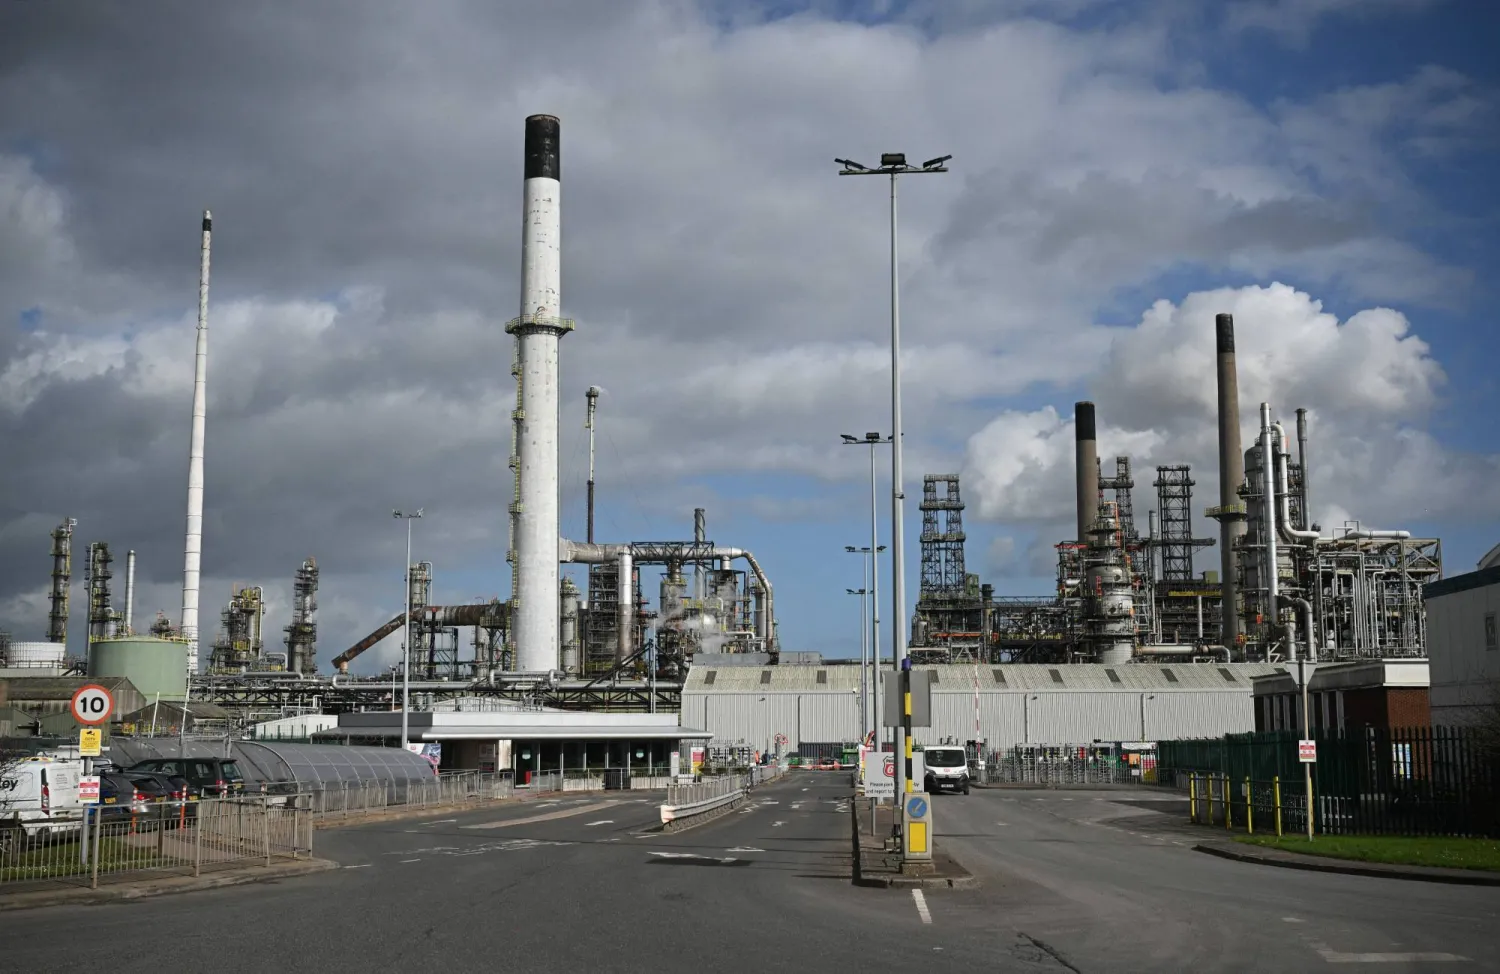
This general view shows the Humber Refinery, operated by Phillips 66, near South Killingholme, north-east England on March 11, 2026. World oil prices surged more than five percent on March 11 as the Middle East war disrupted crude exports. (Photo by Oli SCARFF / AFP)
TT

Iran Tells World to Get Ready for $200 a Barrel

This general view shows the Humber Refinery, operated by Phillips 66, near South Killingholme, north-east England on March 11, 2026. World oil prices surged more than five percent on March 11 as the Middle East war disrupted crude exports. (Photo by Oli SCARFF / AFP)

Iran's military command said on Wednesday the world should be prepared for oil to hit $200 a barrel, as three more ships came under attack in the blockaded Gulf.

Iran fired at Israel and targets across the Middle East on Wednesday, demonstrating it can still fight back and disrupt energy supplies despite what the Pentagon has described as the most intense US-Israeli strikes yet.

Oil prices that shot up earlier this week have eased and stock markets have rebounded, with investors betting for now that US President Donald Trump will find a quick way to end the war he began alongside Israel nearly two weeks ago.

But so far there has been no let-up on the ground, or any sign that ships can safely sail through the Strait of Hormuz, where a fifth of the world's oil has been blockaded behind a narrow channel along the Iranian coast in the worst disruption to energy supplies since the oil shocks of the 1970s.

"Get ready for oil to be $200 a barrel, because the oil price depends on regional security which you have destabilised," Ebrahim Zolfaqari, spokesperson for Iran's military command, said in comments addressed to the United States.

After offices of a bank in Tehran were hit overnight, Zolfaqari also said Iran would respond with attacks on banks that do business with the United States or Israel. People across the Middle East should stay 1,000 metres from banks, he added.

Bahrain's Civil Aviation Affairs said on Wednesday that several Gulf Air aircraft without passengers, and some cargo airplanes, were relocated to alternative airports to "ensure the continuity and efficiency of air operations" during the crisis.

Three more merchant ships were struck in the Gulf by unknown projectiles, according to agencies that monitor maritime security, raising the number of ships reportedly hit since the war began to 14.

Crew were evacuated from a Thai-flagged bulk freighter after an explosion caused a fire. A Japanese-flagged container ship and a Marshall Islands-flagged bulk carrier also sustained damage.

Oil prices, which shot up briefly to nearly $120 a barrel on Monday, have since settled around $90, suggesting investors are betting Trump will be able to halt the war and reopen the strait soon.

But governments are still discussing drastic action. The International Energy Agency was expected to recommend releasing 400 million barrels from global strategic reserves, a record.

That would take months and amount to just three weeks' flow through the strait.


Geopolitical Tensions Reshape Global Corporate Priorities

Container ships at a Saudi port (SPA)
TT

Geopolitical Tensions Reshape Global Corporate Priorities

Container ships at a Saudi port (SPA)

Global companies are being forced to rethink where they invest, produce and source goods as geopolitical tensions and trade disputes make cost and efficiency alone insufficient to guide business decisions.

Rivalry among major powers, mounting trade restrictions and supply chain disruptions are prompting businesses to reassess their markets, suppliers and exposure to risks beyond national borders.

The shift marks a gradual retreat from an economic model built on maximizing efficiency through global production networks toward one that prioritizes security, resilience and the ability to weather crises.

Diversifying suppliers and markets is no longer simply a growth strategy. It has become a safeguard against dependence on specific sources and an increasingly volatile global environment, even if that means higher costs.

The scale of the shift is evident in the International Chamber of Commerce's 2026 survey, released by the World Chambers Federation. It found that 70% of chambers of commerce worldwide ranked geopolitical tensions as a leading business challenge, up 14 percentage points from 2025.

Political risks have now overtaken tariffs and inflation as the biggest concern for businesses and markets.

Trade risks force a rethink of priorities

Uncertainty is no longer confined to conflict zones. It is spreading across economies and weighing on business conditions, according to the survey, a copy of which was obtained by Asharq Al-Awsat.

Chambers of commerce in 61% of the countries surveyed said the trade environment was hurting their operations in 2026.

Trade uncertainty topped the list of concerns, cited by 70% of chambers, followed by tariffs at 63% and import and export restrictions at 39%.

The figures highlight the mounting pressure on businesses as trade barriers rise and fears of retaliation threaten the flow of goods and investment.

The fallout goes beyond international trade, driving up production costs and prices.

Chambers in nearly nine out of 10 countries reported rising prices, while those in eight out of 10 expected inflationary pressures to persist, indicating that businesses and markets are absorbing some of the costs of trade disruptions.

Companies are responding by redrawing their trade networks rather than relying on a narrow pool of suppliers and markets.

Export diversification emerged as the leading strategy, favored by 73% of respondents, followed by switching to alternative suppliers at 64%.

Relocating production, meanwhile, continued to lose favor, suggesting companies would rather strengthen and diversify existing networks than move manufacturing operations on a large scale.

Cautious optimism amid rising risks

Despite the mounting challenges, the business outlook is far from uniformly gloomy.

Chambers of commerce rated economic conditions as good, very good or excellent in more than half the countries surveyed. Only 10% or fewer of the countries received poor or very poor ratings.

Expectations for business activity also improved.

Chambers in six out of 10 countries anticipated an increase in activity, up from five out of 10 in the 2025 survey.

The findings suggest businesses are not necessarily pulling back. Instead, they are adapting to new risks and reorganizing operations to sustain growth in a more volatile environment.

AI emerges as economic opportunity and geopolitical battleground

The forces reshaping global business extend well beyond trade and supply chains. Technology has become another arena of economic and geopolitical competition.

Artificial intelligence is at the center of that shift.

As companies race to harness AI to boost productivity, the technology is also becoming closely tied to countries' ability to secure advanced chips, infrastructure, data centers and the computing power needed to develop it.

The survey showed AI adoption accelerating sharply. The share of chambers reporting widespread use of the technology reached 32%, nearly tripling since 2024.

Optimism about its potential remains strong.

More than 93% of participating chambers expected the AI boom to continue, while around 90% believed it would improve productivity.

But enthusiasm for efficiency gains is accompanied by growing concern over jobs.

Around 40% of chambers expected AI to have a positive impact on employment. Yet half of respondents anticipated a decline in office-based jobs, compared with 32% who expected losses in manual occupations.

Chambers in emerging economies were generally more optimistic about AI's employment impact than those in advanced economies.

Those concerns are unfolding alongside an intensifying global contest for technological leadership.

The survey revealed a growing perception of China as the frontrunner in the AI race.

Half of participating chambers ranked China as the most advanced country in the field, compared with 38% that chose the United States — a view shared even by some respondents in North America.


China, US Discuss Tariffs, Farm Trade at First Trade Council Meeting

US and Chinese flags are seen in this illustration taken March 20, 2025. (Reuters)
TT

China, US Discuss Tariffs, Farm Trade at First Trade Council Meeting

US and Chinese flags are seen in this illustration taken March 20, 2025. (Reuters)

China and the United States held their first trade council meeting under a bilateral economic and trade consultation mechanism via ‌video link ‌on Friday, China's ‌commerce ⁠ministry said on ⁠Saturday.

The two sides held "candid, in-depth and constructive discussions" on implementing outcomes ⁠from previous trade consultations, ‌including ‌tariffs, a reciprocal ‌tariff-reduction arrangement involving $30 ‌billion on each side, agricultural trade and other issues of ‌note, the ministry said.

Both sides will ⁠continue ⁠to use the council to address trade concerns, expand cooperation and reduce outstanding issues, it added.


IMF Says More Work Needed on Lebanon Reforms

A man walks past Lebanon's Central Bank headquarters in Beirut on November 10, 2026. (AFP)
TT

IMF Says More Work Needed on Lebanon Reforms

A man walks past Lebanon's Central Bank headquarters in Beirut on November 10, 2026. (AFP)

The International Monetary Fund said on Friday that more work was needed to reach an agreement on restructuring Lebanon's banking sector, one of the steps towards unlocking billions of dollars in financial assistance.

An IMF staff-level agreement reached in April 2022 laid out conditions to unlock assistance, including a law on the distribution of losses in the banking sector, known as the financial gap law, which parliament has still not voted on.

In a statement at the end of meetings that began on Tuesday, the IMF said "there was progress in further clarifying the approaches under consideration by the Banque du Liban (BdL) and the Government regarding banking sector reform, the draft financial regulation law and the recovery of deposits, and aligning them with international standards".

It however noted that "further work is needed to reach an agreement on a strategy for an effective and durable restructuring of Lebanon's banking sector, leading to a sound and resilient system".

The cabinet submitted a draft of the law to parliament in 2025, but the text is contested by the banking sector and political parties, preventing a vote.

Differences over estimates of losses and their distribution have stalled negotiations with the IMF.

In 2022, the government estimated losses resulting from the 2019 financial crisis at around $70 billion, a figure believed to have increased over the last seven years during which the crisis has remained unresolved.

Lebanese Finance Minister Yassin Jaber said during a news conference that he hoped to "achieve progress that would allow us to reach an agreement on a program with the IMF and sign it during the first quarter of next year, and by its end at the latest".

Lebanon's economic crisis, which the World Bank has ranked among the worst since 1850, has deprived depositors of access to all of their funds, destroyed confidence in the banking sector and led to greater reliance on cash liquidity in various economic and commercial activities.